

Third-party liability for plant and machinery
- Compulsory on public roads
- Also during work
- Cables and pipes separately
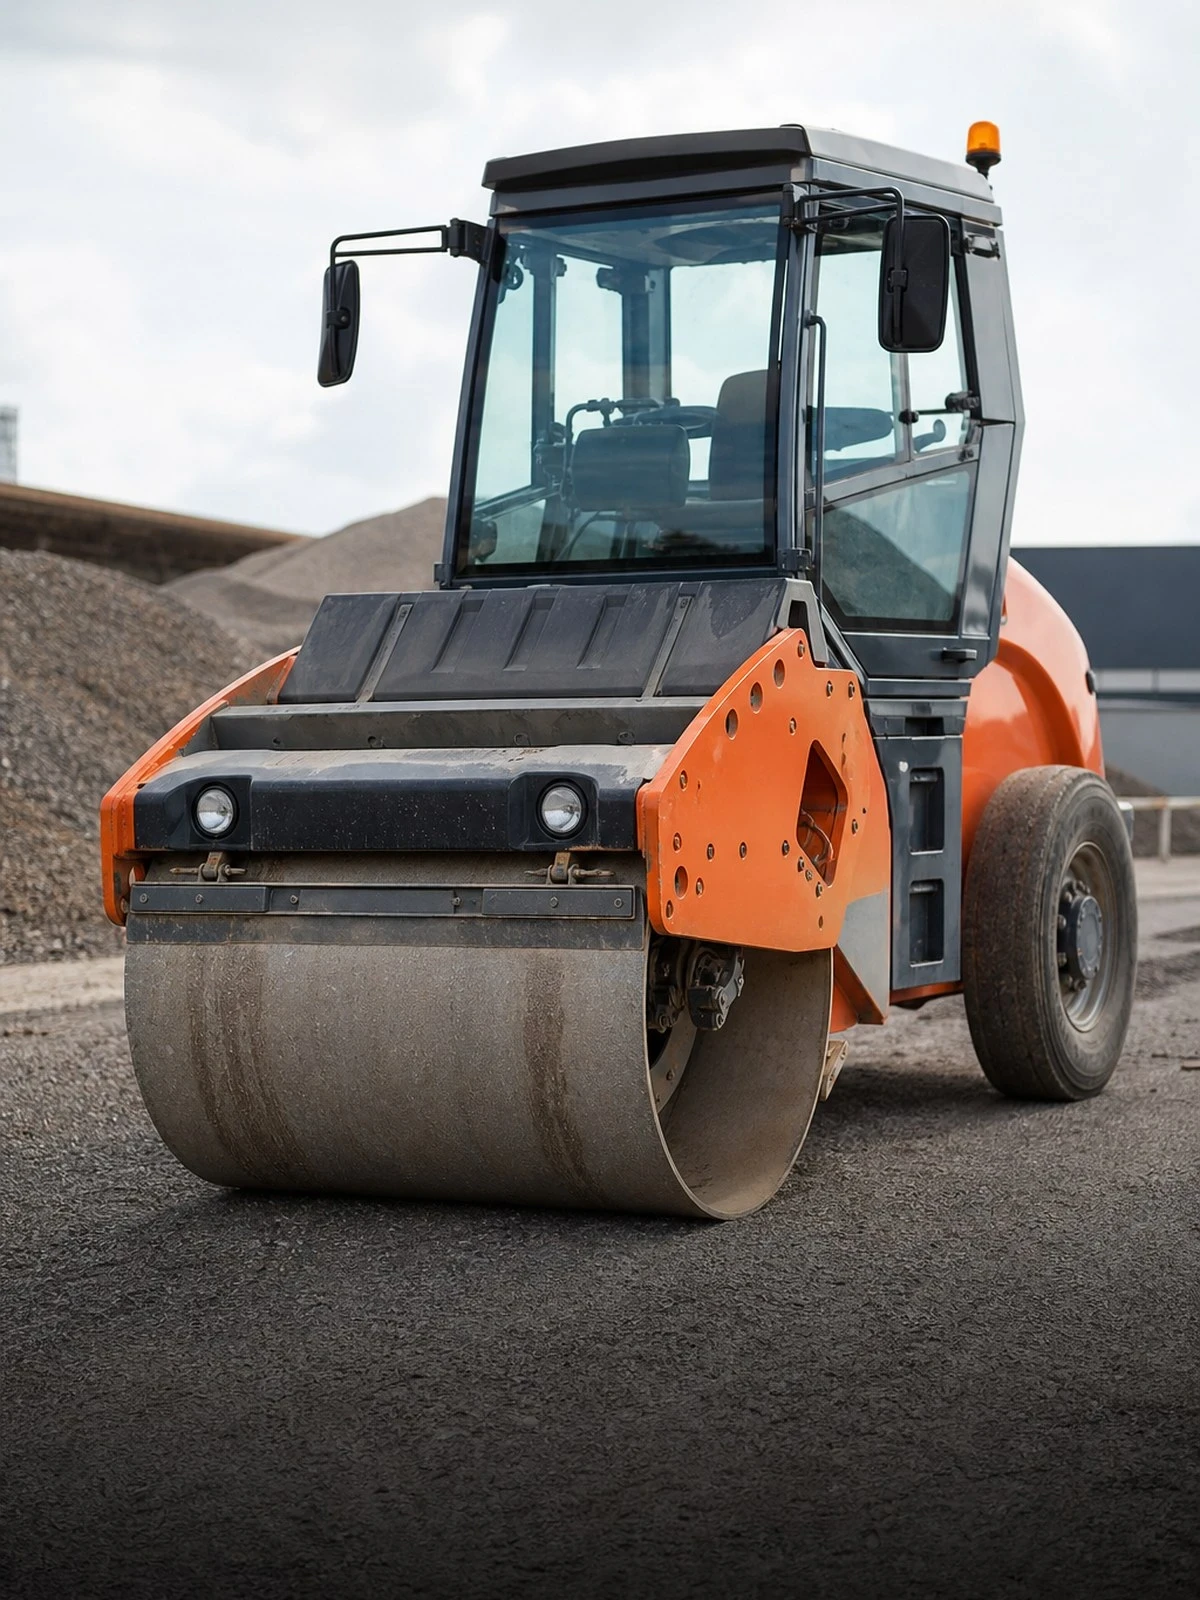
A roller almost always works on or alongside the public road. That makes third-party liability cover compulsory in practically every case and puts vibration damage high on the risk list.
This page in another language: Nederlands
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
A self-propelled roller is a motor vehicle within the meaning of the WAM. Because road works by definition take place on or beside the public road, third-party liability insurance under Article 2 of the Dutch Motor Insurance Liability Act (WAM) is always compulsory. That obligation exists with or without a registration number and applies even where the machine stays inside a coned-off working area that forms part of the public road.
The own-damage cover relates to the roller itself: collision, rolling off an embankment or verge, fire, storm and theft from the work site. In addition there is the distinction that recurs on every equipment policy. Damage on the roller is own damage. Damage through the roller to someone else is liability, and that divides into damage while driving and damage arising from the work.
With a roller that second category is the biggest risk. Vibration damage to adjoining buildings, cables, pipes or paving arises from the work and not from driving, and is therefore assessed on the public and employers' liability insurance. Many AVB policies also have their own exclusion or module for it.
We compare your plant and machinery insurance across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
 Plant and machinery insurance
 Compare
 Get covered
The policy has a compulsory third-party liability layer, an own-damage layer and modules covering transport and the driver.
Damage you cause to others with the machine.
Damage to the machine, the body and the attachments.
What you add separately.
What is covered
| Situation | Third-party liability for plant and machinery | Own-damage cover |
|---|---|---|
| Damage to a building or a parked car next to the site | Yes | No |
| Theft of the machine from the building site | No | Provided that |
| Fire and storm damage | No | Yes |
| Inherent defect in the hydraulics or the engine | No | Provided that |
| Damage to the item you are working on with the machine | No | No |
| Wear and deferred maintenance | No | No |
Mobile plant is a motor vehicle within the meaning of the WAM and needs third-party liability insurance on public roads; non-mobile plant does not. Damage to cables and pipes is generally only covered if the excavation notification has been made and the trial trenches have been dug. The item you work on with the machine falls under the care, custody and control exclusion.
What is actually covered, including exclusions, limits and the excess, is set out in the policy conditions and the insurance card (verzekeringskaart) that you receive before you take out cover.
Insurers weigh these details differently. That is where your saving is.
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
You call or email someone who knows your file. No menu options, no changing call centres.
We cancel your old policy and align the start date, so you are never a day without cover.
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
Customers rate our service on four aspects: personal service, service delivery, availability and the outcome. The reviews are collected and published by NH1816 and come from customers who have actually taken out a policy with Finass Advies B.V. or reported a claim.
Four points that determine whether the policy actually pays out after a claim.
Cracks in a facade, subsided paving or a broken pipe next to the working area are not vehicle damage but damage arising from the activity. That claim is assessed on the AVB, and many AVB policies exclude vibration and compaction damage or require a separate module for it. Before work starts, have the pre-condition survey or structural survey recorded. Without that record it is virtually impossible to establish afterwards which damage was caused by your work.
A roller stands amid passing traffic, cyclists and pedestrians. The WAM cover is therefore not a formality but the layer that is actually called upon. Also pay attention to the cordoning: if it has not been set up in accordance with the arrangements with the highway authority, that can weigh in the question of liability where there is injury. Photograph the cordon and the traffic measures at the start of every working area.
The following, among others, are outside the cover: wear and tear and ageing, including normal wear of drums and tyres; an mechanical or electrical failure without an external cause, such as a failed vibration unit; damage caused by overloading or incorrect use, for example vibrating on ground the machine is not intended for; damage to the the load or the workpiece, and therefore also to the asphalt or sand bed you are compacting; operation by someone without the required certification; and damage caused by intent or recklessness under Article 7:952 of the Dutch Civil Code.
If the roller drives itself to the next section, the ordinary cover applies. If it goes on a trailer or low-loader, it is cargo and damage during loading, lashing, transport and unloading often falls outside own-damage cover. Arrange a transit module for that. Report a loss as soon as is reasonably possible; Article 7:941 of the Dutch Civil Code requires you to do so and a late report can cost you your cover.
This is what people ask us most.
Third-party liability cover is compulsory as soon as the roller uses the public road as a motor vehicle, and with road works that is almost always the case. Article 2 WAM imposes that requirement, without a registration number as well. Own-damage cover is not compulsory by law, but financiers and leasing companies often do require it for as long as the machine has not been paid off.
Not on the plant and machinery policy. It is damage arising from the work and is assessed on the public and employers' liability insurance. Many AVB policies, however, exclude vibration and compaction damage or cover it only through a separate module. Ask about this explicitly and have a structural pre-condition survey carried out beforehand.
A pre-condition survey is a structural inspection of the surrounding buildings before work begins, usually with photographs and crack widths. Without that survey it cannot be established afterwards whether a crack was caused by your work or already existed. Insurers and clients ask for one almost without exception for compaction work in built-up areas.
Only if he is authorised and certified and works with your permission. If the required certification is missing, an own-damage claim can be refused. With a third-party liability claim the insurer usually does pay the injured party, because the WAM protects that third party, but it can then recover the amount paid from you. Keep the certificates.
If it drives itself, the ordinary cover applies. If it goes on a trailer or low-loader, it is cargo and damage during loading, transport and unloading often falls outside own-damage cover. A transit module or own-account transport cover exists for that. If you move between working areas daily, arrange this in advance.
Every situation is different. For these situations we have a separate page.
Request a quote without obligation. We set the WAM obligation, the own-damage conditions and how they dovetail with the AVB side by side.
Prefer to call? 072 - 509 24 56, weekdays 09:00–17:00.
Claim on the road? Emergency line 06 - 55 20 40 72.
Finass Verzekert is a trading name of Finass Advies B.V. We advise on and arrange non-life insurance on the basis of an objective analysis of several insurers, and receive commission for this from the insurer, which is included in the premium. You pay no separate advice fee. Before you take out cover, we establish your wishes and needs.
You will find our licence, KvK and Kifid details and our complaints procedure at the foot of every page.
This page was compiled by Finass Verzekert (LinkedIn). Last updated on .
The information on this page is general in nature and is not personal advice.
Maandag- Vrijdag: 09:00- 17:00
We use cookies and similar technologies to improve your experience on our website.