

Liability
- Injury to pedestrians and cyclists
- Damage to parked cars
- Inside buildings too
- No cover for the vehicle itself
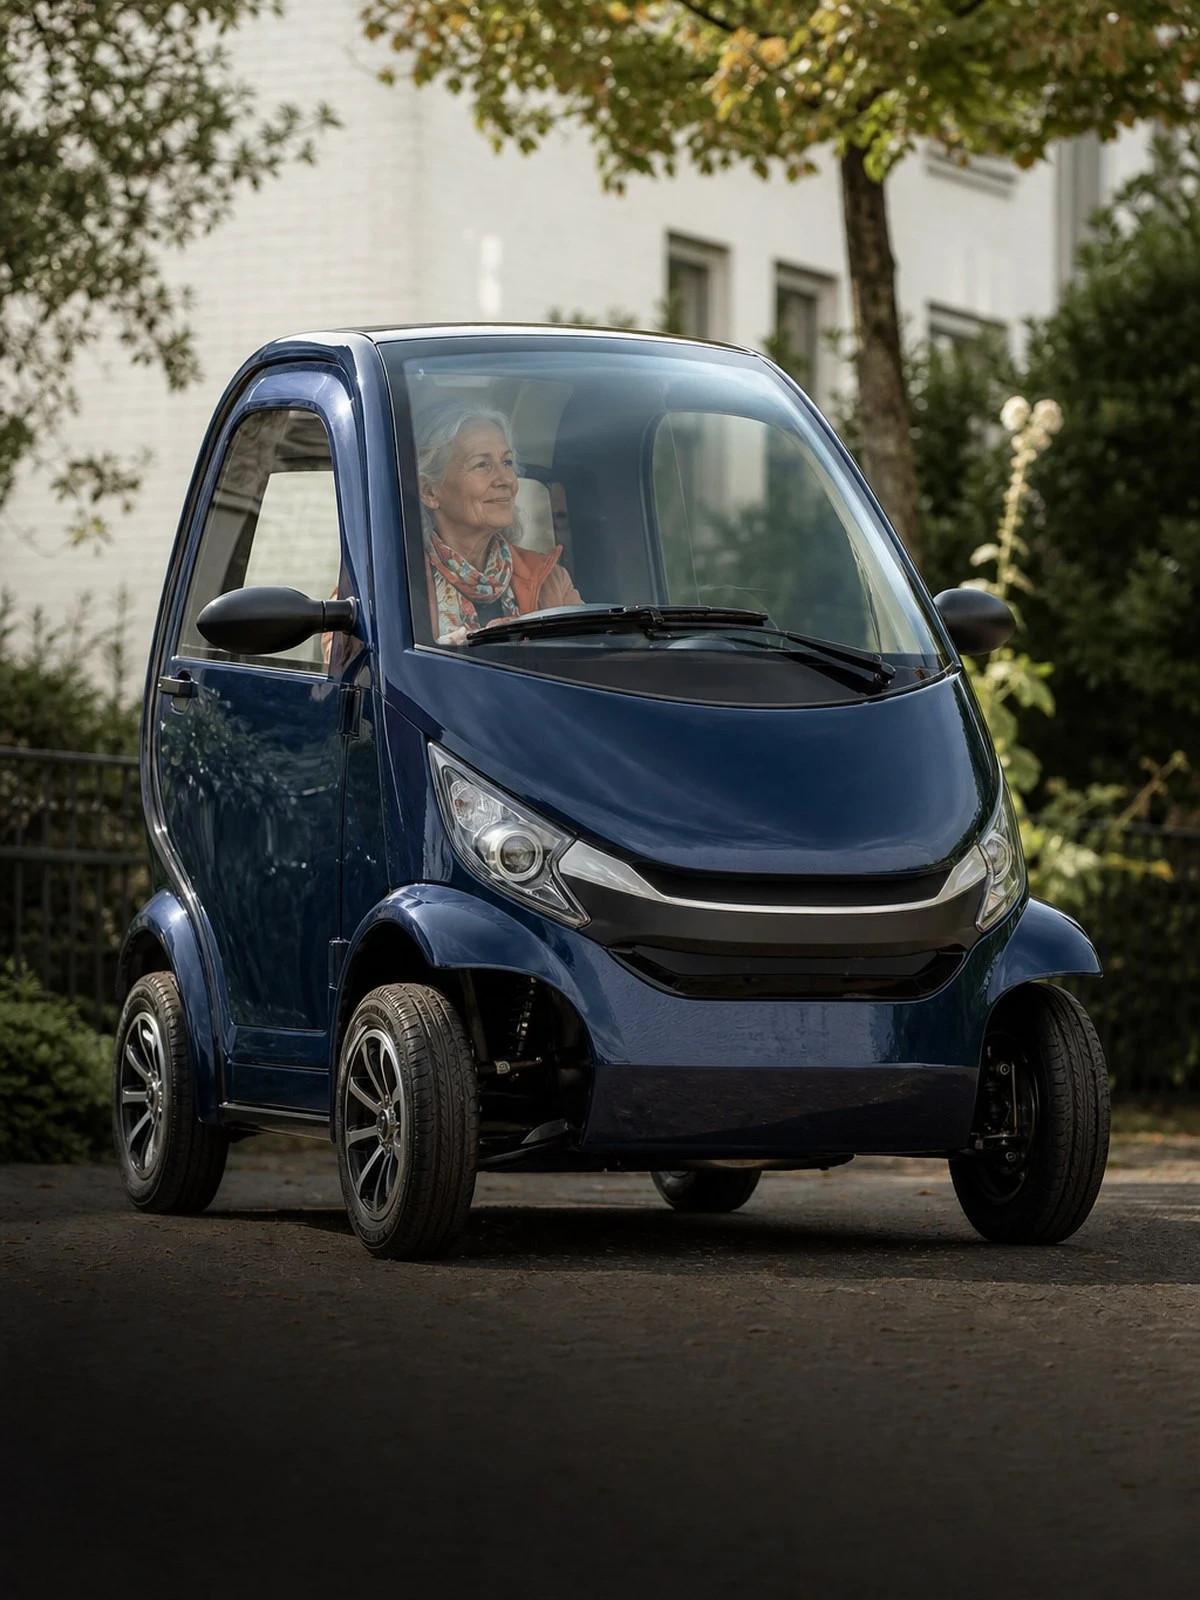
A covered or enclosed mobility scooter has a cabin with windows, doors and sometimes heating. That increases comfort, but also the value and the cost of repairs after a loss.
This page in another language: Nederlands
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
A covered mobility scooter is and remains a disabled person's vehicle. A model with a limited design speed does not require registration and generally falls outside the insurance obligation of Article 2 of the Dutch Motor Insurance Liability Act (WAM). There are, however, faster enclosed versions registered as a moped; for those vehicles the insurance obligation does apply, with the licence requirement that goes with it. Look at the vehicle's papers, not at its appearance: a cabin does not make a mobility scooter a car, but it can mean a different category.
The difference from an open model lies mainly in the own-damage risk. The cabin consists of windows, doors, hinges and plastic panels, often supplemented by a windscreen wiper, heating and lights. Those parts are vulnerable and are not always available separately. A collision that is limited in itself, or a cracked window, therefore leads to a higher repair bill than on an open mobility scooter, and the vehicle is more quickly an economic total loss.
Set against that, an enclosed model is better protected from the weather and keeps the electronics dry. Insurers take that into account, but because of the higher value they often set stricter requirements for storage and security. A cabin model also does not fit in every storage room, which determines whether own-damage cover is available at a reasonable premium.
We compare your moped insurance across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
 Moped insurance
 Compare
 Get covered
Three levels of cover, with the situations that arise most often on cabin models set out beneath them.
Damage you cause to someone else with the mobility scooter.
A fixed list of events beyond your influence, including glass damage.
Damage to your own mobility scooter through your own doing or without a third party involved is also excluded.
What is covered
| Situation | Liability | Comprehensive |
|---|---|---|
| Damage you cause to someone else | Yes | Yes |
| A cracked or broken cabin window | No | Yes |
| Theft from a locked storage place | No | Yes |
| Damage to the heating or windscreen wiper after an accident | No | Provided that |
| Leaks and damp damage from worn seals | No | No |
| Damage during a speed or skill trial | No | No |
What is actually covered, including exclusions, limits and the excess, is set out in the policy conditions and the insurance card (verzekeringskaart) that you receive before you take out cover.
Insurers weigh these details differently. That is where your saving is.
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
You call or email someone who knows your file. No menu options, no changing call centres.
We cancel your old policy and align the start date, so you are never a day without cover.
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
Customers rate our service on four aspects: personal service, service delivery, availability and the outcome. The reviews are collected and published by NH1816 and come from customers who have actually taken out a policy with Finass Advies B.V. or reported a claim.
Four points that determine whether the policy fits this type of vehicle.
Enclosed mobility scooters are sometimes confused with small cars or light quadricycles. What decides the matter is how the vehicle is built and registered: a disabled person's vehicle without a registration comes under a mobility scooter policy, while a model registered as a moped comes under the insurance obligation of Article 2 of the Dutch Motor Insurance Liability Act (WAM) with the licence and registration rules that go with it. Check that before you buy. A policy on the wrong basis will not stand up after a loss.
The cabin is the most expensive part of the vehicle. Windows, doors, hinges and plastic panels are vulnerable and often available only through the importer. So check whether glass damage is arranged separately and whether an excess applies to it. Also check whether separate fittings such as heating, a windscreen wiper or extra lights are stated on the policy schedule. What has not been declared is generally not paid after a loss.
The following, among others, are outside the cover: theft without the prescribed security or from an unlocked place; use off-road, on the beach or in the dunes where the policy gives no cover; taking part in speed or skill trials; and, on a registered model, riding without a valid licence for that category. Also excluded are leaks through perished seals, rust, wear, loss of battery capacity and damage through intent or recklessness (Article 7:952 of the Dutch Civil Code) are excluded.
A cabin model is taller and wider than an open mobility scooter and does not fit in every storage room. Insurers tie own-damage cover to a a locked storage space; if you cannot provide one, report that when you apply rather than after the event. On taking out the policy, the duty of disclosure under Article 7:928 of the Dutch Civil Code and a breach of it can void the payout (Article 7:930 of the Dutch Civil Code). You report a claim as soon as reasonably possible (Article 7:941 of the Dutch Civil Code).
This is what people ask us most.
No. A light quadricycle (brommobiel) is a moped on four wheels with a moped registration and a design speed of 45 kilometres per hour. An enclosed mobility scooter is a disability vehicle with a much lower speed and generally without a registration. Both have a cabin, but they come under different rules and different policies. The vehicle's papers are decisive, not its appearance.
Under third party, fire and theft and comprehensive cover it generally is, but the conditions differ widely. Some insurers have a separate glass section with its own excess, others pay for glass damage only as part of a covered event. Because cabin windows are often available only through the importer, the bill can run high. Ask about this point expressly before you take out the policy.
More often than on an open mobility scooter. The purchase value is higher and the cabin consists of parts that are expensive and sometimes hard to obtain, so the vehicle is more quickly an economic total loss after a collision. As the market value falls, third party, fire and theft, or liability cover alone, becomes more attractive. Assess that each year against the current value.
Report that when you apply. For own-damage cover, insurers often require the vehicle to stand in a locked space. If you cannot meet that requirement, the result is a higher premium, a higher excess or liability cover only. If you conceal it and the mobility scooter is stolen from the street, no payment follows.
Only if you declared those fittings when you applied and they are stated on the policy schedule. Adaptations that increase the value must be reported; fittings that have not been reported are generally not paid after a loss. Also ask about the maximum payment for accessories, because that is almost always capped at a fixed amount per event.
Every situation is different. For these situations we have a separate page.
Request a quotation without obligation. We check the version, the glass cover and the storage requirements.
Prefer to call? 072 - 509 24 56, weekdays 09:00–17:00.
Claim on the road? Emergency line 06 - 55 20 40 72.
Finass Verzekert is a trading name of Finass Advies B.V. We advise on and arrange non-life insurance on the basis of an objective analysis of several insurers, and receive commission for this from the insurer, which is included in the premium. You pay no separate advice fee. Before you take out cover, we establish your wishes and needs.
You will find our licence, KvK and Kifid details and our complaints procedure at the foot of every page.
This page was compiled by Finass Verzekert (LinkedIn). Last updated on .
The information on this page is general in nature and is not personal advice.
Maandag- Vrijdag: 09:00- 17:00
We use cookies and similar technologies to improve your experience on our website.