

Insuring your KTM
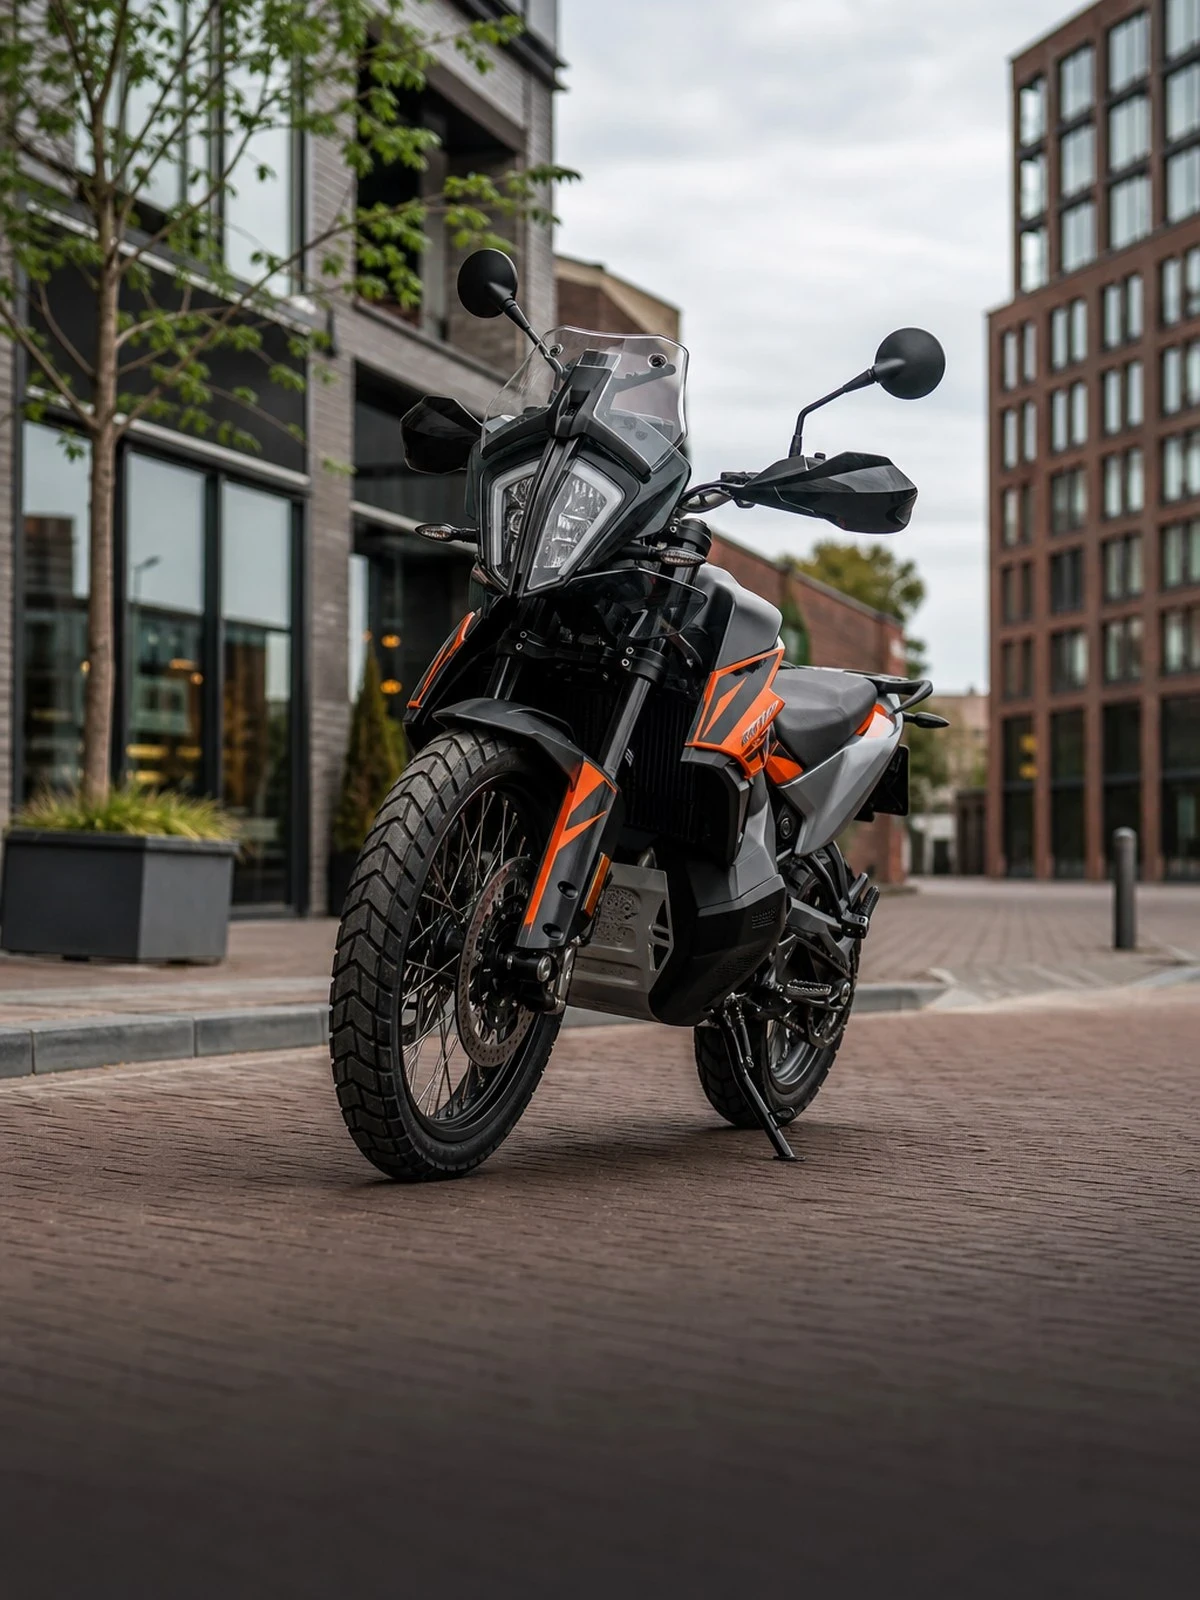
KTM builds machines that are as much at home on an unpaved track as on the motorway. It is precisely that dual purpose that raises the question, when a claim is made, of where the machine was being ridden at the time.
- Several insurers compared objectively
- 9.5 customer rating for a new policy
- AFM licence 12016589
- Personal 072 - 509 24 56, weekdays 9–17
This page in another language: Nederlands
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
- We compare the offerings of several insurers
- An adviser checks whether the cover suits your situation
- We arrange the switch, including cancellation
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
- Independent advice
- Several insurers
- Switching arranged
- Help with claims
In brief
For a registered machine the ordinary duty to insure applies: Article 2 of the Dutch Motor Insurance Liability Act (WAM) requires at least third-party liability cover for as long as the registration is live and has not been suspended. That also applies to an enduro or supermoto that spends most of the year in the shed. The forms of cover themselves are set out under motorcycle insurance cover; you compare through motorcycle insurance.
A motocross machine without a registration is a different story. It is not subject to the duty to insure, but that also means it is insured nowhere. If you hit someone on a site, you are liable under Article 6:162 of the Dutch Civil Code, and your personal liability insurance (AVP) is no help: it expressly excludes damage involving motor vehicles. For organised training, cover usually runs through the organisation or through a separate events solution.
The third point is the structure. A different exhaust, altered mapping, a different sprocket set or a raised seat changes the machine from the factory specification. Report that on the application or when the change is made. If after a loss the power output turns out to differ from what was stated, that feeds through into the settlement under Articles 7:928 and 7:930 DCC, even where the modification had nothing to do with the accident.
This page deals with one situation. The full overview is on Compare motorcycle insurance.
Independent, personal, sorted quickly
We compare your motorcycle insurance across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
 Motorcycle insurance
 Compare
 Get covered
Why arrange it through Finass Verzekert?
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
Independent
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
One fixed adviser
You call or email someone who knows your file. No menu options, no changing call centres.
Switching without hassle
We cancel your old policy and align the start date, so you are never a day without cover.
Help with claims
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
What to look out for
Four points that are different on an off-road machine from an ordinary road bike.
The line between road and off-road
On the public road, including an unpaved track open to everyone, your policy applies. If you ride on a closed site, a motocross track or a circuit, cover is almost always excluded, even where it is practice and not a competition. Trail and touring runs on public roads are included, provided the route is legal.
Without a registration you are uninsured, not exempt
A machine without a registration does not have to carry third-party liability cover, but that only means the obligation is absent. If you cause injury to someone else, you bear that personally. The personal liability insurance excludes motor vehicles, so it does not step in. For own damage and theft from the shed, separate cover for the object is needed.
Modifications and unapproved parts
An exhaust without type approval or a change in power output makes the machine differ from the registration data. Besides the risk of a claim being declined, an incorrect statement of the power output can also mean that your licence category no longer matches. Keep invoices and approval certificates for fitted parts with the vehicle papers.
Transport on a trailer
Many riders take the machine to the starting point on a trailer. If it falls off on the way, that is not a road accident involving the machine itself; own-damage cover under the motorcycle policy by no means always pays for it. Liability for damage the trailer causes to others runs through the towing vehicle; see trailer insurance.
What does your premium depend on?
- Power and engine capacity: determines the rating group and the licence category
- Type of machine: an adventure model is assessed differently from a supermoto
- Market value or agreed valuation: including fitted and declared parts
- Age and how long you have held a licence: young riders with little experience pay more
- Storage and security: off-road machines are light and therefore prone to theft
- Use and mileage: daily commuting is weighed differently from weekend rides
Insurers weigh these details differently. That is where your saving is.
What is covered
| Situation | Third-party liability | Comprehensive |
|---|---|---|
| You hit a parked car while manoeuvring in a car park | Yes | Yes |
| You slide out on a bend and damage the tank and fairing panels | No | Yes |
| The machine is stolen from your garage despite an ART lock | No | Yes |
| Helmet and motorcycle clothing are unusable after a fall | No | Provided that |
| Theft from winter storage while the insurance is suspended | No | Provided that |
| Damage to the machine during a training day on a circuit | No | No |
While the registration is suspended, own-damage cover continues only where that has been expressly agreed.
Frequently asked questions
This is what people ask us most.
Am I insured on an enduro or motocross site?
Almost never. Policies exclude riding on a closed site, a track or a circuit, even where you are only practising and nobody else is riding. Both the damage to your own machine and liability towards others therefore fall outside the cover. If you ride off-road regularly, ask the organisation what cover applies there.
My KTM has no registration. Do I have to insure it?
The duty to insure under Article 2 of the Dutch Motor Insurance Liability Act (WAM) applies to registered motor vehicles used on the public road. Without a registration that duty does not exist, but you are then covered nowhere. You bear liability for injury you cause on a site yourself, because personal liability insurance excludes motor vehicles. Theft from the shed also calls for a separate solution.
I have fitted a different exhaust. Do I have to report it?
Yes. Report every modification that changes the power output, the value or the specification. If you do not and, when a claim is made, the machine turns out to differ from what was stated, the insurer can reduce or refuse payment under Articles 7:928 and 7:930 of the Dutch Civil Code. Keep the invoices, so that the fitted parts also count in the valuation.
Is my machine insured while being transported on a trailer?
Not as a matter of course. During transport the machine is not taking part in traffic as a motor vehicle; damage caused by it coming loose or falling off the trailer is excluded under many own-damage policies, or paid only on a limited basis. Check this in advance. Damage your trailer causes to third parties runs in principle with the insurance of the towing vehicle.
Every situation is different. For these situations we have a separate page.
- Compare motorcycle insuranceThe main page
- KTM motorcycle insuranceSports machines, premium class, off-road use
- Insuring your Honda motorcycleDriving licence category, accessories, imports
- Choosing motorcycle insurance that suits your motorcycleForm of cover, licence category, modifications
- Insuring a self-employed professional's motorcycleBusiness use, your own injury, storage
- Insuring your motorcycleThird-party liability compulsory, own-damage cover, theft protection
- Insuring a DucatiSporting, high list price, maintenance