

Basic cover
- Fire & lightning strike
- Burglary & theft at home
- Explosion & smoke
- Water damage at home
Commercial fine art insurance covers works hanging in an office, practice or institution, including the moments when they come down for transport, restoration or a loan.
This page in another language: Nederlands
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
This insurance is intended for organisations that own art or hold it in their care: offices with a collection, institutions, galleries, collectors with a corporate structure and parties that receive works on loan. The cover is comprehensive property cover on named items and goes further than business contents insurance, which usually includes art only to a limited extent.
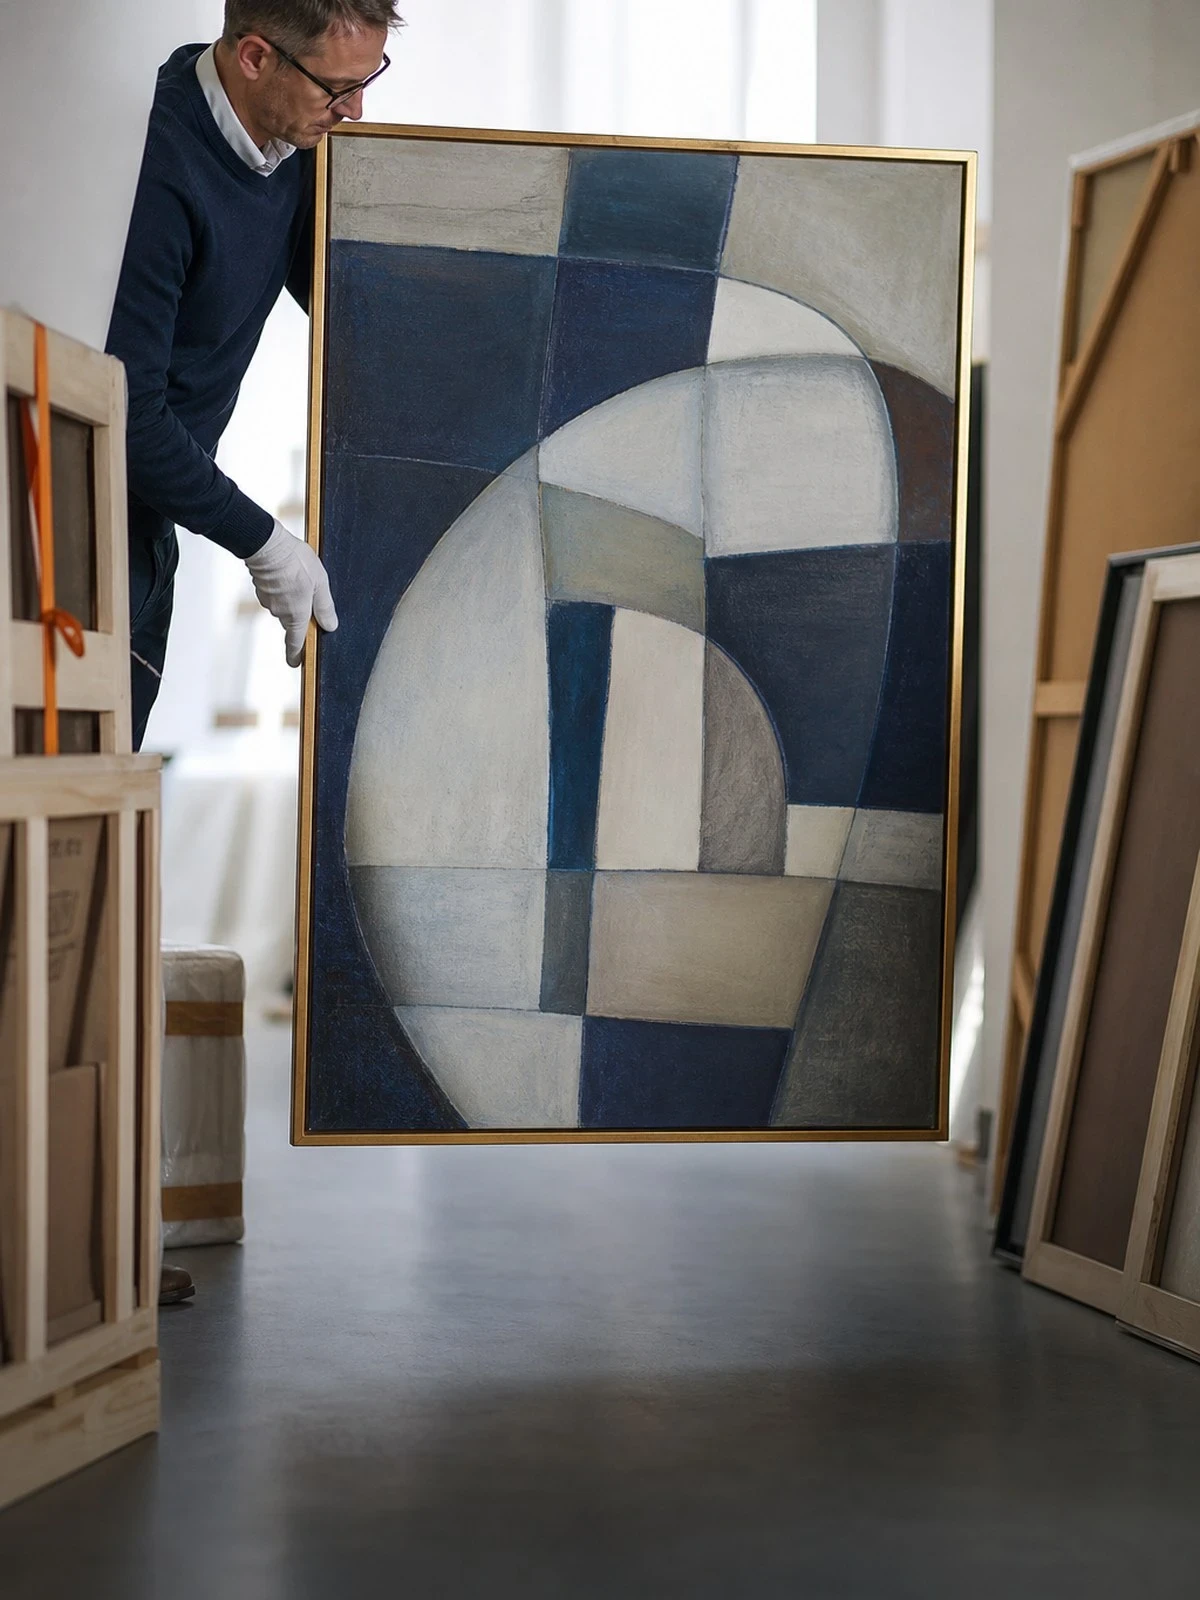
What is distinctive is that the cover moves with the work. Packing, transport, temporary storage, exhibition elsewhere and the journey back all fall within the same policy, provided this is properly arranged in advance. This product also has an element that is not found elsewhere: payment for loss of value after damage has been repaired.
We set Hienfeld's structure alongside that of other providers and look at the valuation period, the requirements for carriers and restorers and the cover during loans. See also our page on musical instrument insurance.
We compare your valuables insurance across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
 Valuables insurance
 Compare
 Get covered
The structure of the cover in three parts, with an overview per situation below.
The basic cover insures the core of your commercial fine art insurance. We show what Hienfeld and other insurers offer within it.
As well as the basic cover, also protection against loss, damage and theft away from home, including from external causes.
The most complete cover. We compare Hienfeld's extended version with the market.
What is covered
| Situation | Extended | Comprehensive |
|---|---|---|
| Fire, smoke and water damage in the home | Yes | Yes |
| Theft after forced entry | Yes | Yes |
| Knocks and falls at home | No | Yes |
| Loss or theft away from home | Provided that | Provided that |
| Damage during transport, repair or exhibition | Provided that | Provided that |
| Wear, shrinkage, damp and insect damage | No | No |
A home contents policy has sub-limits: for jewellery, audiovisual equipment and collections a lower limit applies than for the rest of the contents. If your items exceed that, you insure them separately on a valuables policy, usually on the basis of a valuation (7:960 DCC). Underinsurance leads to a proportionately lower payout.
What we do
| What we do | At Finass | Direct with Hienfeld |
|---|---|---|
| Comparison across several insurers | Yes | No |
| Advice based on your own situation | Yes | Sometimes |
| One point of contact for claims | Yes | Sometimes |
| Cancellation with your current insurer arranged | Yes | No |
| We determine whether Hienfeld is the best choice | Yes | No |
| Advice fees for you as a customer | No | No |
This overview concerns our service, not the cover. What is actually covered is set out in the policy conditions and on the insurer's insurance card (verzekeringskaart); you receive both before you take out cover.
Insurers weigh these details differently. That is where your saving is.
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
You call or email someone who knows your file. No menu options, no changing call centres.
We cancel your old policy and align the start date, so you are never a day without cover.
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
Customers rate our service on four aspects: personal service, service delivery, availability and the outcome. The reviews are collected and published by NH1816 and come from customers who have actually taken out a policy with Finass Advies B.V. or reported a claim.
Four points that make the difference between a policy that pays out and one that does not.
The cover runs from the moment a work comes off the wall until it hangs again: packing, transport, storage, exhibition and return. The condition is almost always that a specialist art carrier is engaged and that the packing is suited to it. If you carry the work yourself or use an ordinary carrier, the cover during that journey often lapses entirely, even though the work is otherwise on the policy.
After damage, a restored work usually fetches less than it did before, even where the restoration is technically successful. That difference can only be claimed if the policy includes loss in value. Insurers also require restoration to be carried out by a restorer they accept. If you set someone to work yourself, the claim lapses, including for the cost of the repair itself.
The insured value follows from a valuation per item or per collection. Under Article 7:960 of the Dutch Civil Code a valid agreed value valuation binds the insurer to the amount established. The valuation has a term; once it expires, settlement is at market value. New purchases only fall under the policy after being declared. So ask for an arrangement for new acquisitions with a notification period and an interim limit.
Inherent defect and inherent fragility fall outside: craquelure, fading from light, drying out, the acidification of paper and the disintegration of materials that simply tend that way. Gradual climatic effects, unskilled handling or restoration, and a fall in value through the market are also excluded. Damage during building work without prior notification is regularly refused, as is theft without signs of forced entry where works are on open display.
This is what people ask us most.
Yes, provided this has been arranged in advance. The cover runs nail to nail: packing, transport, storage, exhibition and return. Almost always the requirement applies that a specialist art carrier is engaged. If you arrange the transport yourself or through an ordinary courier service, there is usually no cover during that journey, whatever else is on the policy.
That difference is called loss in value and can only be claimed where the policy includes that element. Without that cover you are paid only the restoration costs. The further condition applies that the restoration was carried out by a restorer the insurer accepts. If you set someone to work yourself, payment of the repair costs can lapse as well.
Yes. A policy covers the items that have been declared and valued. A newly acquired work only falls under it once declared. So agree an arrangement for new acquisitions, with a notification period and an interim limit within which a purchase is automatically covered. Also keep track of the term of the valuations, because an expired valuation takes you back to market value.
That calls for a separate arrangement. If a work hangs in a hall, waiting area or restaurant, there is more risk of being touched, of vandalism and of removal without forced entry. Insurers impose requirements for that: barriers, secured hanging systems, cameras or supervision. Without those measures, theft without signs of forced entry from an open display is often excluded.
Every situation is different. For these situations we have a separate page.
Request a quote without obligation. We will look at which insurer best matches your activities and your risk.
Prefer to call? 072 - 509 24 56, weekdays 09:00–17:00.
Claim on the road? Emergency line 06 - 55 20 40 72.
Finass Verzekert is a trading name of Finass Advies B.V. We advise on and arrange non-life insurance on the basis of an objective analysis of several insurers, and receive commission for this from the insurer, which is included in the premium. You pay no separate advice fee. Before you take out cover, we establish your wishes and needs.
You will find our licence, KvK and Kifid details and our complaints procedure at the foot of every page.
This page was compiled by Finass Verzekert (LinkedIn). Last updated on .
The information on this page is general in nature and is not personal advice.
Maandag- Vrijdag: 09:00- 17:00
We use cookies and similar technologies to improve your experience on our website.