

Fine art insurance
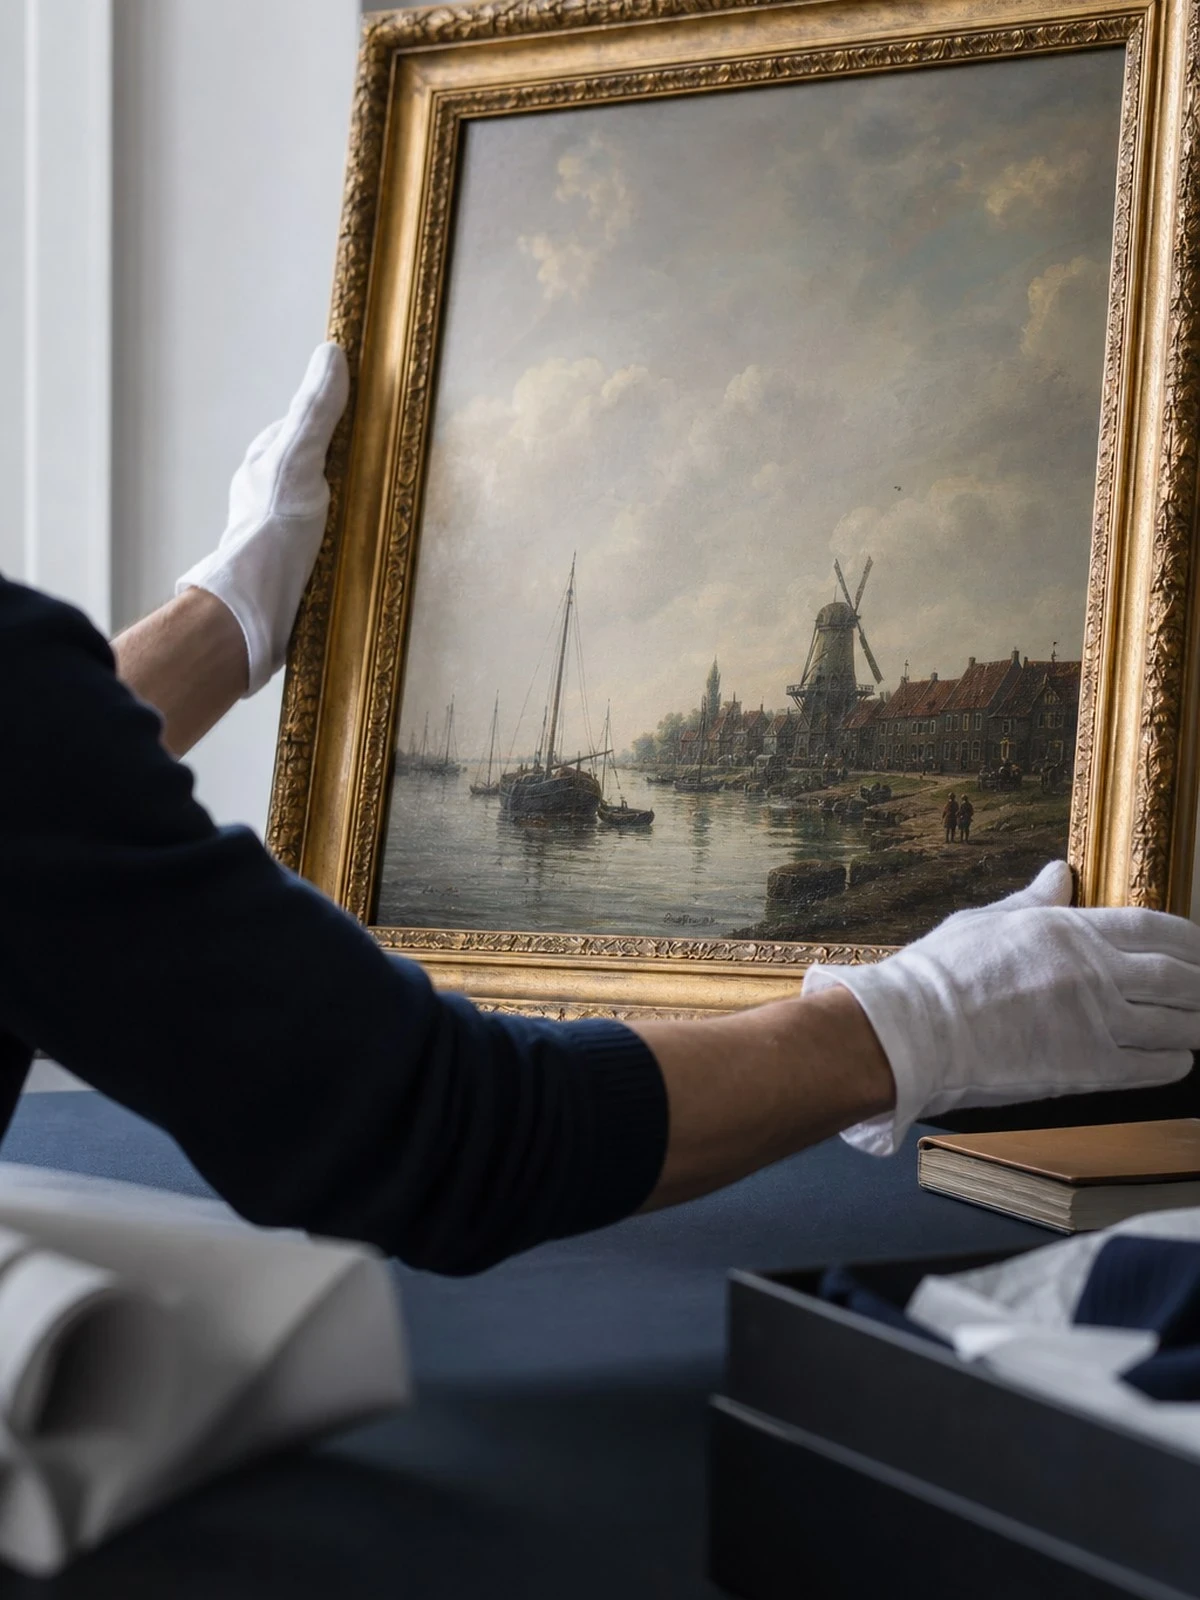
A painting that tears is rarely a total loss. It is repaired and worth less afterwards. Whether that residual value is paid for is determined by fine art insurance, not by the home contents policy.
- Several insurers compared objectively
- 9.5 customer rating for a new policy
- AFM licence 12016589
- Personal 072 - 509 24 56, weekdays 9–17
This page in another language: Nederlands
The calculator and the quote form below are in Dutch. Prefer to do this in English? Email info@finassverzekert.nl or call 072 - 509 24 56 and we will take it from there.
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
- We compare the offerings of several insurers
- An adviser checks whether the cover suits your situation
- We arrange the switch, including cancellation
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
- Independent advice
- Several insurers
- Switching arranged
- Help with claims
In brief
Art differs from ordinary home contents on one point that governs the whole policy: the item cannot be replaced. A damaged sofa is replaced, a damaged canvas is restored. That is why fine art insurance turns on two concepts that do not appear on a home contents policy: the agreed value and the loss of value after repair. The latter is the difference between the value before the damage and the value of the restored work. Without that provision the insurer pays the restorer and you bear the loss in value yourself.
The home contents insurance usually has a sub-limitfor art and antiques: a maximum amount for the whole category together, regardless of what you actually own. Above that amount there is no cover, even if the total sum insured is generous. Work that out before you arrange anything else. The background is set out under valuables on the home contents policy and to the valuables insurance.
A valuation by a recognised expert fixes the value in advance. That works within the limit of Article 7:960 of the Dutch Civil Code: a payment may not leave you in a clearly better position. A valuation has a period of validity, usually a few years. Once it expires, you fall back on the value at the time of the loss and the argument starts after all. See also establishing the value for the insurance.
This page deals with one situation. The full overview is on Compare valuables insurance.
Independent, personal, sorted quickly
We compare your valuables insurance across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
 Valuables insurance
 Compare
 Get covered
Why arrange it through Finass Verzekert?
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
Independent
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
One fixed adviser
You call or email someone who knows your file. No menu options, no changing call centres.
Switching without hassle
We cancel your old policy and align the start date, so you are never a day without cover.
Help with claims
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
What to look out for
Four provisions that are more often decisive in art claims than the sum insured.
Comprehensive is not the same as everything covered
Comprehensive cover works with an open description: what is not excluded is covered. That is wider than a policy with a list of events, which does not include a frame that has fallen off the wall or a plinth that has been knocked over. But the exclusions remain, and with art it is precisely those that determine the outcome.
Inherent defect and the nature of the material
Craquelure in an old paint layer, oxidation of silver, ink that fades or veneer lifting are inherent defect and excluded as standard. The same applies to gradual effects of light, damp and changes in temperature. A work hanging above an open fire or next to underfloor heating loses quality through where it is placed. That is not a sudden event.
Restoration, framing and cleaning
Damage that arises during treatment is almost always excluded: cleaning, reframing, relining or retouching. If something goes wrong at the restorer's, that is a matter between you and his liability insurance. Set out in writing in advance who insures the item during that period and at what value.
The market value falls: that is not damage
Insurance pays for damage to the item, not for a fall in value through the market or through doubt about an attribution. If a work turns out to be attributable to another hand, nothing has been damaged and so there is nothing to pay. Deliberately caused damage remains excluded under Article 7:952 of the Dutch Civil Code.
What does your premium depend on?
- Total insured value: the collection as a whole, not per work
- Type of works: paper and textiles are more fragile than bronze
- Security of the home: alarm, monitored or not, and locks and fittings
- Climate and hanging: damp, light and how works are fixed
- Area of cover: in the house only, or elsewhere and while travelling as well
- Basis of value: a valuation, purchase invoice or a fixed sum insured
Insurers weigh these details differently. That is where your saving is.
What is covered
| Situation | Extended | Comprehensive |
|---|---|---|
| A burglary in which two paintings are taken from the living room | Yes | Yes |
| A leak from the flat above damages a work on paper | Yes | Yes |
| A guest knocks a ceramic off its plinth during a dinner | No | Yes |
| A work is damaged during the move to your second home | Provided that | Yes |
| A bronze sculpture disappears from the back garden | No | Provided that |
| Your work is damaged while on loan to a museum | No | Provided that |
Above the sub-limit on your home contents policy, none of these rules applies any longer without separate art cover.
Frequently asked questions
This is what people ask us most.
Do I need a separate policy or is my home contents insurance enough?
That depends on the sub-limit for art and antiques on your home contents policy and on what you own. If the total value stays well below it and everything hangs at home, home contents insurance is often enough. As soon as you go above the sub-limit, want cover away from the home or want loss in value after repair paid for, separate art or valuables cover is needed.
What exactly does loss in value after repair mean?
A restored work is usually worth less than the same work without a damage history. The insurer then pays the restoration costs plus the difference in value, provided the policy has that provision. Have it set out who establishes that difference and at what point. Without that clause the restorer's invoice is all you are paid.
Do I have to have a valuation carried out?
For works of any significance, yes. A valuation report from a recognised expert fixes the value bindingly and prevents you from having to prove what a work was worth when a loss occurs. For recently purchased works a purchase invoice may be enough. State on the application what you have and how it has been valued; Article 7:928 of the Dutch Civil Code requires you to declare it correctly.
Is theft of a work from my home always covered?
Only if the security conditions on the policy schedule have been met. With collections, insurers impose requirements on locks and fittings, the alarm and sometimes on how works are fixed to the wall. If the alarm was not switched on or a prescribed measure was missing, the payment can be reduced or refused. Report a theft to the police and the insurer at once; Article 7:941 of the Dutch Civil Code requires timely notification.
Every situation is different. For these situations we have a separate page.
- Compare valuables insuranceThe main page
- Art insurance through HienfeldCollection at home, sculptures outdoors, building work
- Renaissance insurance through HienfeldAntiques and interiors, repairability, clauses
- Insuring fine artTransport, loans, storage
- Art on home contents or valuables insuranceValuation, transport, climate and hanging
- Insuring artProvenance, transport, climate
- Compare exclusive valuables insuranceValuation, safe clause, worldwide
- Insuring jewellery, art and watchesValuation, safe clause, worldwide cover