

Liability
- Cables and pipes
- Damage to crops or buildings
- Injury to bystanders
With a classic tractor everything turns on the amount stated on the policy schedule: a restored tractor is worth more than its market value, and that difference has to be recorded in advance.
This page in another language: Nederlands
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
A classic tractor is an enthusiast's vehicle that does few hours and rarely does any real work. Its insurance therefore differs from that of working plant: the basis is not replacement value but an agreed value, and use is limited in the policy to runs, parades and events.
That valuation is not a formality. An expert's report that meets Article 7:960 of the Dutch Civil Code fixes the value in a binding way and prevents the argument about underinsurance that would otherwise follow a fire or a theft. Without a valuation the insurer pays the market value, and that bears no relation to the restoration that has gone into it.
On the public road a classic is subject to the insurance obligation under Article 2 of the Dutch Motor Insurance Liability Act (WAM)as well, and agricultural vehicles now have to be registered with the RDW (the Dutch vehicle authority). If the tractor stays in the barn and only comes out on your own land, that obligation falls away but the risk of fire, theft and liability remains.
We compare your classic car insurance across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
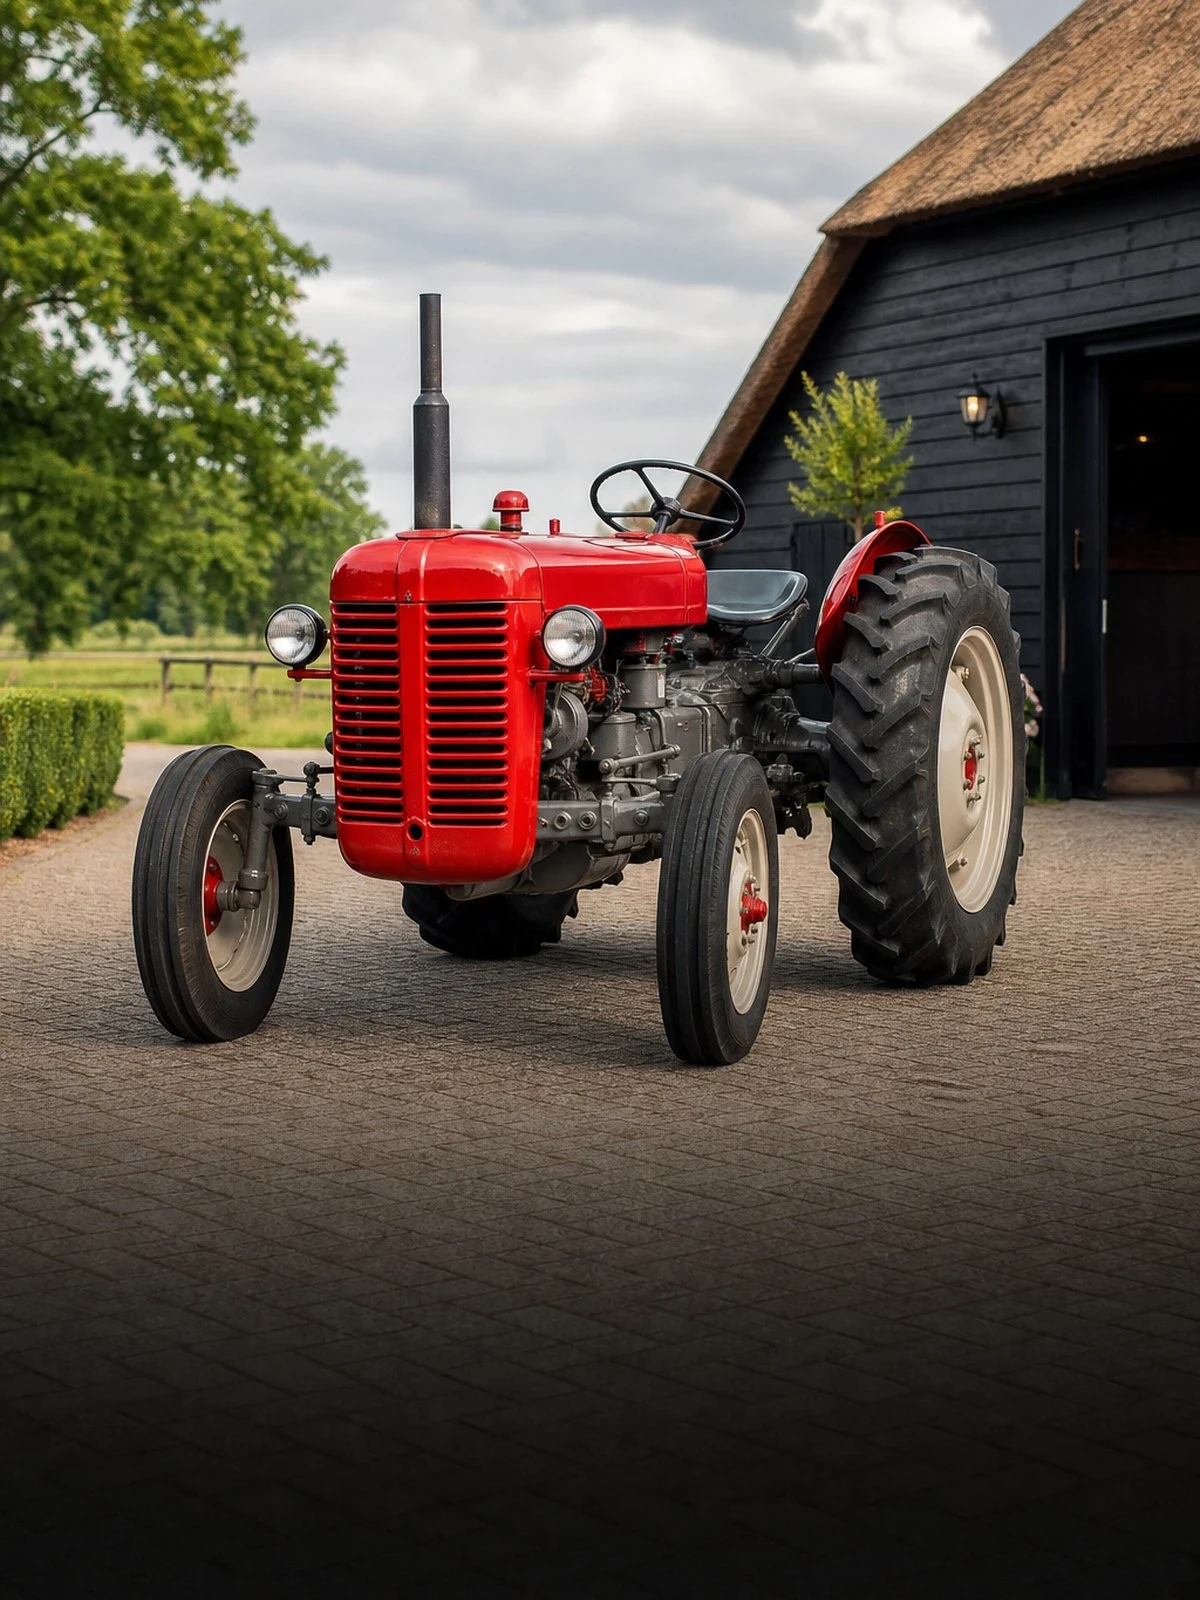 Classic car insurance
 Compare
 Get covered
The structure of the cover in three parts, with an overview per situation below.
Damage you cause to others with the machine.
Damage, theft and usually inherent defect as well.
What matters besides the machine itself.
What is covered
| Situation | Liability | Own-damage cover |
|---|---|---|
| Damage to crops, buildings or pipes and cables | Yes | No |
| Theft of the machine | No | Sometimes |
| Fire or storm damage | No | Yes |
| Inherent defect or operating error | No | Sometimes |
| Blades, teeth and tyres worn out | No | No |
| Deferred maintenance | No | No |
This overview is general in nature and is not personal advice. What is actually covered, including exclusions, limits and the excess, is set out in the policy conditions and the insurance card (verzekeringskaart) of the insurer; you receive both before you take out cover. Taking out cover without advice? Then read what execution only means for you.
Insurers weigh these details differently. That is where your saving is.
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
You call or email someone who knows your file. No menu options, no changing call centres.
We cancel your old policy and align the start date, so you are never a day without cover.
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
Customers rate our service on four aspects: personal service, service delivery, availability and the outcome. The reviews are collected and published by NH1816 and come from customers who have actually taken out a policy with Finass Advies B.V. or reported a claim.
Four points that make the difference between a policy that pays out and one that does not.
An original tractor with a documented restoration represents an enthusiast's value that has nothing to do with the book value. Have it established by a recognised valuer and attach the report to the policy; under Article 7:960 of the Dutch Civil Code the insurer is bound by it and there is no room for argument afterwards. Repeat the valuation periodically, because many insurers no longer accept an expired report.
The favourable terms of an enthusiast policy hang on the agreement that the tractor is not used as a working machine. Groundwork, contract work, hire and tractor pulling or other competitions are excluded. Regular use as a second yard vehicle also falls outside what this cover is intended for. If the use changes, report it; concealment falls under Article 7:930 of the Dutch Civil Code and can reduce the payment proportionately or remove it altogether.
The biggest risk is not the road but the barn. Fire in a shed with hay or straw, and theft of loose parts such as brass fittings, an original bonnet or a rare set of lamps, are the usual claims. Insurers ask about the storage location and whether it can be locked and include that as a condition. If the tractor is somewhere other than declared at the time of the loss, that affects the cover.
Corrosion, seized pistons, leaking oil seals and the consequences of a failed overhaul are not a sudden event and remain excluded. The same applies to damage while working on the machine, welding and running it up in a workshop, and to parts damaged during transport to an event on a trailer. If you want that transport covered, it is a separate arrangement on the policy schedule.
For higher values, insurers require a tracker and agreements on where the machine is kept outside working hours.
Blades, teeth, cutting edges, tracks and tyres are wearing parts and are not insured anywhere; only sudden damage is covered. Deferred maintenance is also a ground for exclusion. A demonstrable maintenance regime with a logbook is therefore not only good management but also strengthens your position in a claim.
This is what people ask us most.
Without a valuation the insurer pays the market value, and for a restored tractor that is far below what you have in it. A report that meets Article 7:960 of the Dutch Civil Code binds the insurer to the amount established, so that no argument about underinsurance arises after a fire or a theft. Have the report renewed in good time, because an expired valuation falls back to market value.
Not on this policy. Taking part in competitions, manoeuvring tests and tractor pulling is excluded as standard, as is tuning the engine for it. If damage arises during or immediately around such an event, it is refused, and liability for injury to spectators can fall outside the cover as well. Organisers arrange separate event insurance for that.
The tractor remains covered against fire and theft at the storage location declared, but damage arising during the work itself, such as weld damage, a wrongly fitted part or a failed engine overhaul, is excluded. That is an inherent defect and not a sudden event from outside. Spare parts you keep separately have to be declared separately if you want them included.
The insurance obligation for motor vehicles does not then apply, but fire and theft are precisely the most common losses in storage. Your home contents or buildings insurance does not cover the tractor: motor vehicles are excluded there. Limited own-damage cover with fire and theft is therefore usual even for a collection tractor standing still, whether or not it ever goes on the road.
Every situation is different. For these situations we have a separate page.
Request a quote without obligation. We will look at which insurer best matches your activities and your risk.
Prefer to call? 072 - 509 24 56, weekdays 09:00–17:00.
Claim on the road? Emergency line 06 - 55 20 40 72.
Finass Verzekert is a trading name of Finass Advies B.V. We advise on and arrange non-life insurance on the basis of an objective analysis of several insurers, and receive commission for this from the insurer, which is included in the premium. You pay no separate advice fee. Before you take out cover, we establish your wishes and needs.
You will find our licence, KvK and Kifid details and our complaints procedure at the foot of every page.
This page was compiled by Finass Verzekert (LinkedIn). Last updated on .
The information on this page is general in nature and is not personal advice.
Maandag- Vrijdag: 09:00- 17:00
We use cookies and similar technologies to improve your experience on our website.