

Business contents
- At replacement value as new
- Fire, water and burglary
- Tenant's improvements separately
In a construction business the contents rarely stand still: plant shuttles between the warehouse, the trailer and the site, while the policy in principle covers only the address.
This page in another language: Nederlands
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
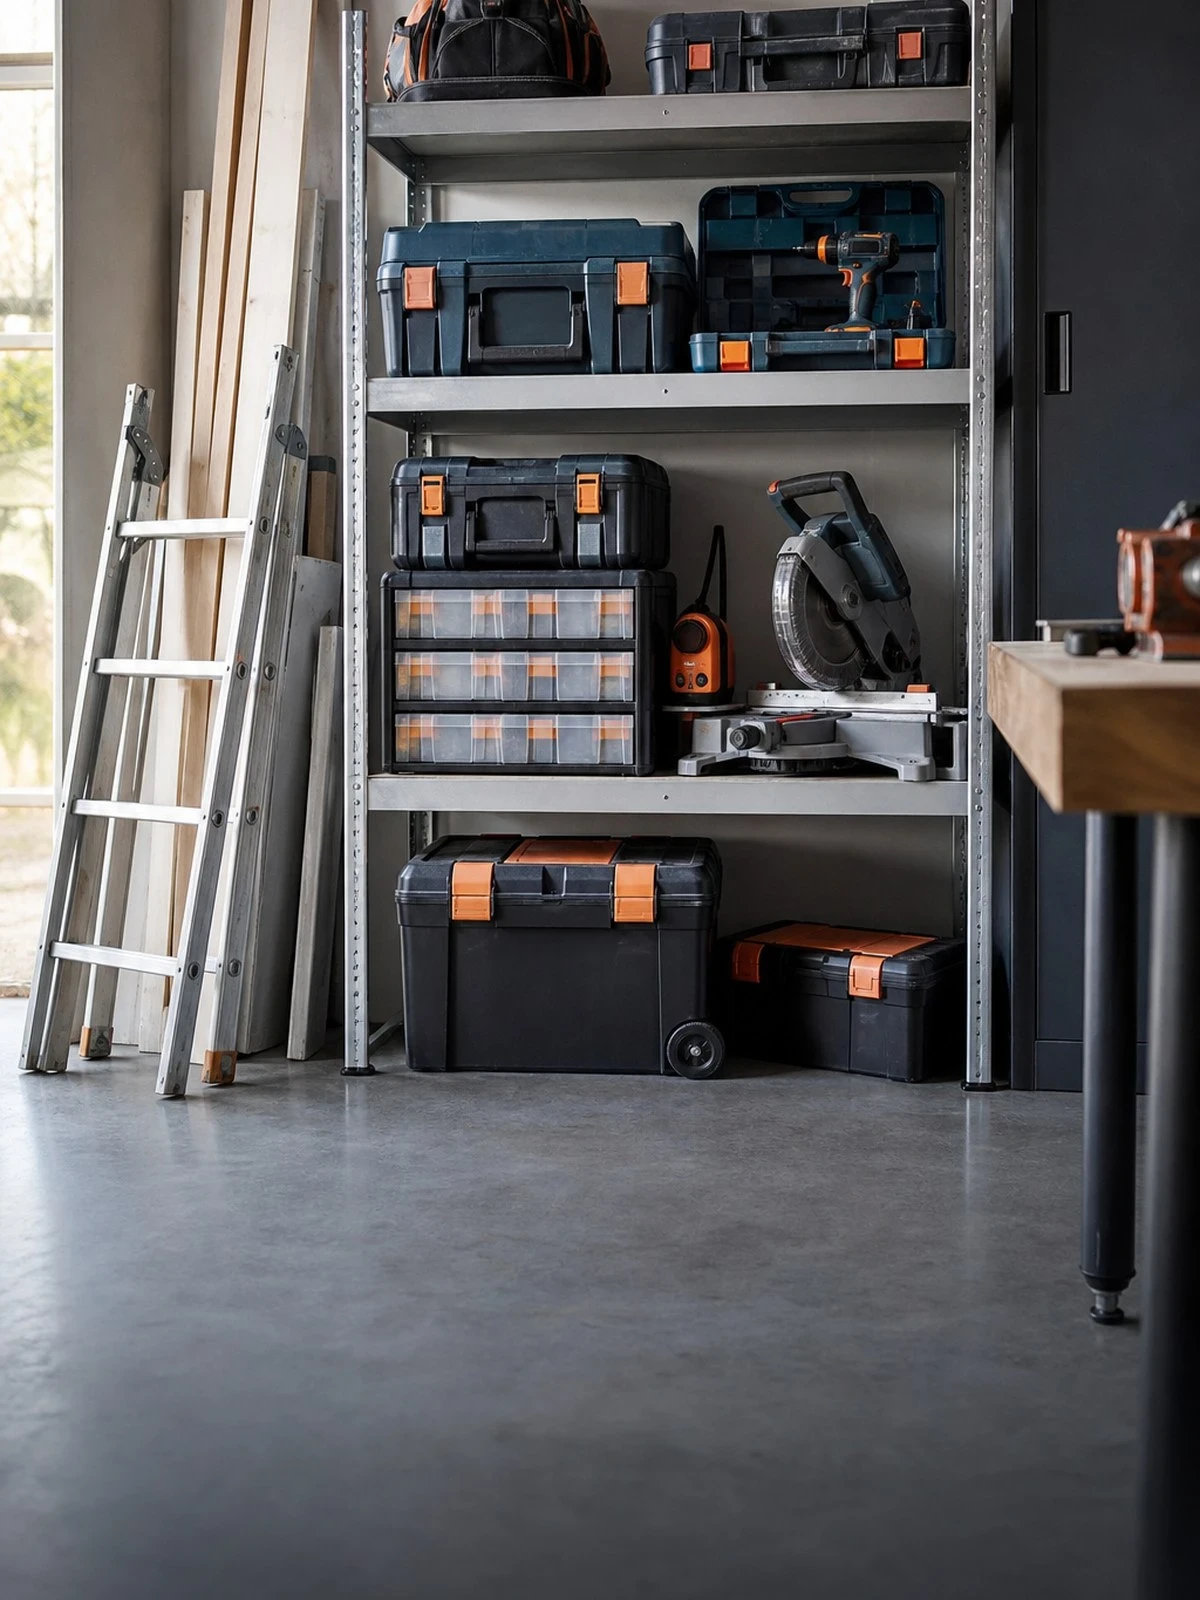
The business contents of a construction business includes the workshop machinery, scaffolding and shoring, formwork, boxed and hand tools, the workbenches and the fit-out of the office and site hut. The goods are the building materials you keep in stock. The insured address is the warehouse or the business site; anything not there is not automatically covered by the policy.
That is the point where this insurance falls short more often for a construction business than for a shop or an office. Plant on site, in the trailer or in a temporary storage container needs separate cover away from the address. The works in progress themselves do not belong here but on a Construction all risks (CAR) insurance; check that dividing line, otherwise you pay twice or not at all.
Standard exclusions are theft without signs of forced entry from an open warehouse or container, plant standing in the open air, wear and tear and inherent defect of a machine, and plant you hire or lease from someone else. Report claims within the period stated in the conditions and report the matter to the police; that duty to notify is set out in Article 7:941 of the Dutch Civil Code.
We compare your business contents insurance across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
 Business contents insurance
 Compare
 Get covered
The structure of the cover in three parts, with an overview per situation below.
Machinery, equipment, furniture and fixed fittings.
Trading stock, raw materials and finished products.
What is excluded as standard.
What is covered
| Situation | Business contents | Goods |
|---|---|---|
| Fire and smoke damage | Yes | Yes |
| Burglary with signs of forced entry | Yes | Yes |
| Water damage from a burst pipe | Yes | Yes |
| Customers' property being worked on | No | No |
| Spoilage due to refrigeration failure | Sometimes | Sometimes |
| Wear and deferred maintenance | No | No |
This overview is general in nature and is not personal advice. What is actually covered, including exclusions, limits and the excess, is set out in the policy conditions and the insurance card (verzekeringskaart) of the insurer; you receive both before you take out cover. Taking out cover without advice? Then read what execution only means for you.
Insurers weigh these details differently. That is where your saving is.
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
You call or email someone who knows your file. No menu options, no changing call centres.
We cancel your old policy and align the start date, so you are never a day without cover.
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
Customers rate our service on four aspects: personal service, service delivery, availability and the outcome. The reviews are collected and published by NH1816 and come from customers who have actually taken out a policy with Finass Advies B.V. or reported a claim.
Four points that make the difference between a policy that pays out and one that does not.
Construction plant is readily saleable, neither identifiable nor registered, and goes in a single van load. Insurers therefore look at the burglary resistance of the roller door and the sectional door, at the fencing around the site, at outdoor lighting and at an alarm connected to a monitoring centre. Anyone keeping copper, cable and cordless tools in the warehouse faces stricter requirements. Theft leaving no signs of forced entry is almost never paid for.
Construction all risks (CAR) insurance covers the works in progress and usually also ancillary materials, site huts and temporary facilities on the job. Your business contents insurance covers the business address. Between the two there is a seam: tools you take to the job. Arrange expressly which policy carries them, because when a loss occurs both insurers point at each other and you are caught in between.
If you hire a telehandler, a plate compactor or an access platform, that is not your own business contents but plant in your in your care. Almost every hire contract places the risk with the hirer, while the care, custody and control exclusion in your liability insurance takes it out again. Arrange a separate section for hired plant or have the hire company confirm in writing that it keeps the risk.
Outside the cover remain wear and tear and inherent defect of machinery, plant standing unprotected in the open air, fuel and oil in tanks including the soil contamination that follows, and money. A machine you overloaded yourself is also not an insured loss. Update the sum insured after every major purchase: with underinsurance payment is proportionate, even for small claims.
This is what people ask us most.
Not automatically. Business contents insurance covers the business address stated. For plant on the job you need cover away from the address, or a separate plant policy. Even then requirements apply: storage in a locked container or hut, demonstrable forced entry in the event of theft and sometimes a maximum per event. Check this before you set up the first site.
CAR insurance is about the work you produce: the structure under construction, the materials incorporated in it and the damage arising during construction. Business contents insurance is about your own business assets at your own address. They do not overlap and they do not automatically complement each other either. The seam between them is for you to close.
Look at the hire contract first. Hire companies almost always place the risk of damage, theft and loss with the hirer. Your liability insurance in fact excludes items in your care, custody and control. So you need a separate section for hired plant, or written confirmation that the hire company keeps the risk itself.
Usually not. Almost all property policies require demonstrable signs of forced entry to the premises or the storage space in the event of theft. If plant disappears without those signs, it is treated as a disappearance and not as covered theft. Always report it to the police immediately and notify the claim within the period stated in your conditions. That follows from Article 7:941 of the Dutch Civil Code.
Every situation is different. For these situations we have a separate page.
Request a quote without obligation. We will look at which insurer best matches your activities and your risk.
Prefer to call? 072 - 509 24 56, weekdays 09:00–17:00.
Claim on the road? Emergency line 06 - 55 20 40 72.
Finass Verzekert is a trading name of Finass Advies B.V. We advise on and arrange non-life insurance on the basis of an objective analysis of several insurers, and receive commission for this from the insurer, which is included in the premium. You pay no separate advice fee. Before you take out cover, we establish your wishes and needs.
You will find our licence, KvK and Kifid details and our complaints procedure at the foot of every page.
This page was compiled by Finass Verzekert (LinkedIn). Last updated on .
The information on this page is general in nature and is not personal advice.
Maandag- Vrijdag: 09:00- 17:00
We use cookies and similar technologies to improve your experience on our website.