

Independent
- Several providers compared
- Advice follows your situation
- AFM licence 12016589
This policy insures the cargo itself at its actual value and is therefore independent of whether the carrier is liable and whether there is anything to recover from him.
This page in another language: Nederlands
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
Goods in transit insurance is a property policy on the consignment, not on the carrier. If the cargo is damaged or disappears on the way, the policy pays without first having to establish who made a mistake. That is the essential difference from carriers' liability insurance, which only comes into play if the carrier falls short and which is also limited by law.
That limitation works per kilogram. Under the CMR Convention, international road carriage is limited to 8.33 SDR per kilogram; under the AVC conditions a fixed amount per kilogram applies. For light, valuable consignments such as instruments, electronics or medical equipment, such a weight limit covers only part of the invoice value. Anyone who does not insure the difference bears it themselves.
When setting up this cover we look at each route: which conditions apply, whether cover runs from address to address or only starts once the wheels are turning, whether interim storage and transhipment are included, and whether your own journeys fit better under own goods in transit insurance. See also the general explanation of goods in transit insurance.
We compare your goods-in-transit insurance across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
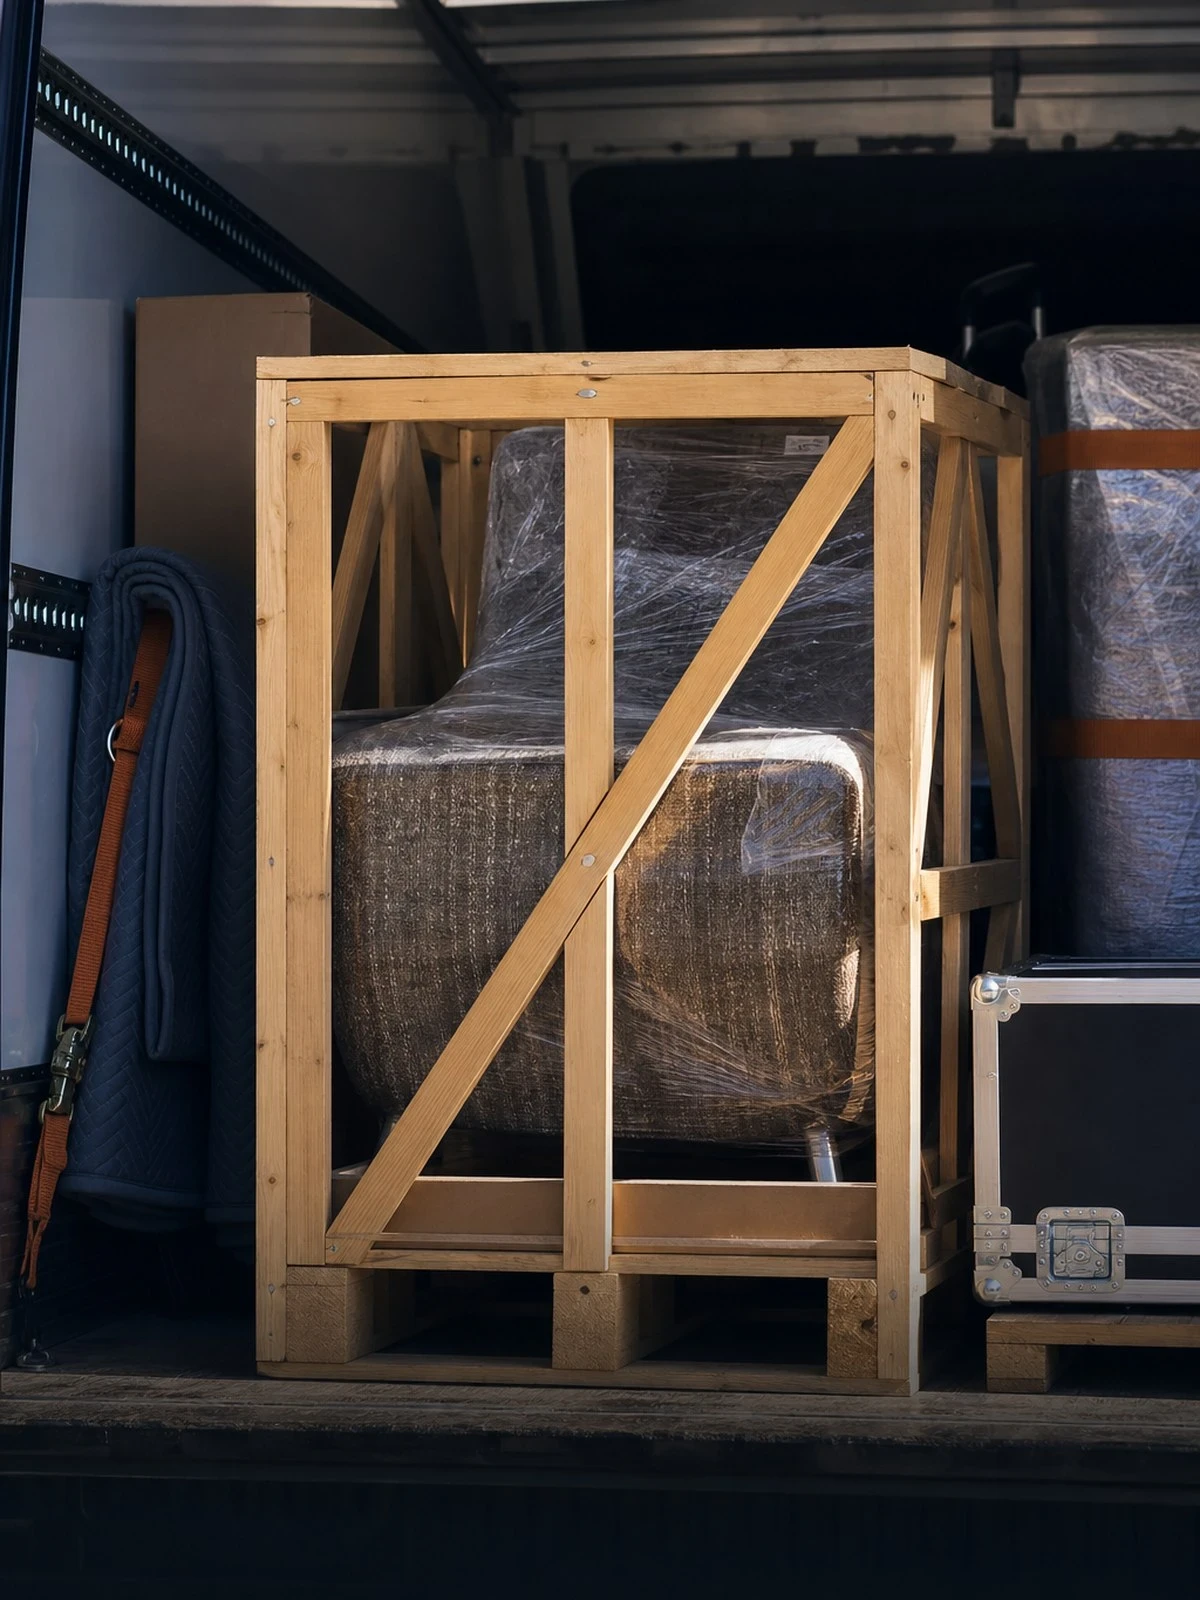 Goods-in-transit insurance
 Compare
 Get covered
The structure of the cover in three parts, with an overview per situation below.
We are not tied to any single company.
From assessment to policy.
What really matters.
What is covered
| What we look at | Explanation |
|---|---|
| Does the cover suit your activities | Yes |
| Sum insured and excess | Yes |
| Exclusions and clauses | Yes |
| Fit with your other policies | Yes |
| Premium in relation to the conditions | Yes |
| Comparing on premium alone | No |
This overview is general in nature and is not personal advice. What is actually covered, including exclusions, limits and the excess, is set out in the policy conditions and the insurance card (verzekeringskaart) of the insurer; you receive both before you take out cover. Taking out cover without advice? Then read what execution only means for you.
Insurers weigh these details differently. That is where your saving is.
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
You call or email someone who knows your file. No menu options, no changing call centres.
We cancel your old policy and align the start date, so you are never a day without cover.
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
Customers rate our service on four aspects: personal service, service delivery, availability and the outcome. The reviews are collected and published by NH1816 and come from customers who have actually taken out a policy with Finass Advies B.V. or reported a claim.
Four points that make the difference between a policy that pays out and one that does not.
In a contract of sale the risk passes from seller to buyer at an agreed moment. That delivery term determines who has an interest in the cargo during the journey and therefore who should arrange the transit cover. When it comes to it both parties assume the other has dealt with it. Record for each customer or supplier what has been agreed, before the first consignment goes out.
With this product the period of cover matters more than the sum insured. Some conditions run from the moment the goods are taken up until delivery at the final address, including loading, unloading and normal interim storage. Others cover only the period during which the cargo is in the vehicle. If a trailer stands on a yard over a weekend, or a consignment spends a night in a transhipment warehouse, that distinction becomes visible at once.
Visible damage or a shortage has to be noted on the consignment note at delivery. The consignee reports non-visible damage within the period set by the carriage conditions. Without that note it is hard to establish later that the damage arose in transit. Also report to the insurer as soon as possible, as Article 7:941 of the Dutch Civil Code requires, and keep the packaging and the pallet available for the surveyor.
Outside the cover are loss caused by the nature or an inherent defect of the goods themselves, unsound or unsuitable packaging, and normal wear and tear or loss of weight in transit. Delay loss and consequential loss are excluded as well: a lost day's production or a cancelled order is not paid for. Money and securities also stay outside it, as do intent and recklessness on the part of the insured under Article 7:952 of the Dutch Civil Code.
This is what people ask us most.
His insurance covers his liability, limited per kilogram and only where he is at fault. In cases of force majeure, a collision for which a third party is liable, or theft despite normal care, you are left with the loss. This policy insures the goods themselves and pays the actual value, regardless of fault.
That depends on the conditions chosen. Cover from address to address includes normal interim storage that forms part of the carriage; long-term storage in a distribution centre or with a third party is usually a separate risk. We agree in advance what counts as a normal part of the journey and what you have to arrange separately.
Only if the policy allows it. Many conditions exclude theft from unattended vehicles outside a guarded site, or set requirements as to an alarm, a locked load space and where the vehicle stands. If you drive fixed routes with expensive cargo, we put that situation to the insurer in advance and have those requirements set down in black and white.
For non-visible damage a notification period applies under the carriage conditions. If that is met, the file can usually still be pursued. With visible damage and no note on the consignment note it becomes harder, because delivery then counts as having been made undamaged. Always report to us straight away, even if you are not yet sure who is liable.
Every situation is different. For these situations we have a separate page.
Request a quote without obligation. We will look at which insurer best matches your activities and your risk.
Prefer to call? 072 - 509 24 56, weekdays 09:00–17:00.
Claim on the road? Emergency line 06 - 55 20 40 72.
Finass Verzekert is a trading name of Finass Advies B.V. We advise on and arrange non-life insurance on the basis of an objective analysis of several insurers, and receive commission for this from the insurer, which is included in the premium. You pay no separate advice fee. Before you take out cover, we establish your wishes and needs.
You will find our licence, KvK and Kifid details and our complaints procedure at the foot of every page.
This page was compiled by Finass Verzekert (LinkedIn). Last updated on .
The information on this page is general in nature and is not personal advice.
Maandag- Vrijdag: 09:00- 17:00
We use cookies and similar technologies to improve your experience on our website.