

Independent
- Several providers compared
- Advice follows your situation
- AFM licence 12016589
Environmental damage insurance pays for the clean-up and remediation of contamination, including on your own site, which is exactly where a liability policy by definition never reaches.
This page in another language: Nederlands
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
This is not a liability policy but a first-party policy. Payment does not depend on whether anyone made a mistake: as soon as an insured event causes contamination, the clean-up costs are met. Your public and employers' liability insurance works the other way round: it pays for third-party losses for which you are liable under Article 6:162 of the Dutch Civil Code, and it does not cover the cleaning of your own soil.
Cover depends on an identifiable cause: fire, explosion, a lightning strike, storm, a collision, or a tank, pipe or storage vessel springing a leak. Contamination that has built up gradually over the years falls outside it. The policy is built up in sections: your own site, third-party sites where you carry out work, and sometimes the transport in between.
We arrange two things when the policy is taken out. The first is the baseline situation: whatever is already in the ground before the policy starts is excluded, so the insurer often asks for a soil survey. The second is how the policy fits with your AVB and, if you are building, with the Construction all risks (CAR) insurance, so that no gap opens up between those policies.
We compare your environmental damage insurance across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
 Environmental damage insurance
 Compare
 Get covered
The structure of the cover in three parts, with an overview per situation below.
We are not tied to any single company.
From assessment to policy.
What really matters.
What is covered
| What we look at | Explanation |
|---|---|
| Does the cover suit your activities | Yes |
| Sum insured and excess | Yes |
| Exclusions and clauses | Yes |
| Fit with your other policies | Yes |
| Premium in relation to the conditions | Yes |
| Comparing on premium alone | No |
This overview is general in nature and is not personal advice. What is actually covered, including exclusions, limits and the excess, is set out in the policy conditions and the insurance card (verzekeringskaart) of the insurer; you receive both before you take out cover. Taking out cover without advice? Then read what execution only means for you.
Insurers weigh these details differently. That is where your saving is.
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
You call or email someone who knows your file. No menu options, no changing call centres.
We cancel your old policy and align the start date, so you are never a day without cover.
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
Customers rate our service on four aspects: personal service, service delivery, availability and the outcome. The reviews are collected and published by NH1816 and come from customers who have actually taken out a policy with Finass Advies B.V. or reported a claim.
Four points that make the difference between a policy that pays out and one that does not.
If contamination spreads from your site to the plot next door or into a ditch, your liability insurer has a say. If the pollution stays within your own boundary there is no injured third party and therefore no liability, while the authorities can still require a clean-up. Your buildings insurance (opstalverzekering) is no help either: it pays for the building, not the ground beneath it. This policy fills precisely that gap.
In a fire, contaminated firefighting water ends up in the soil, the sewer or the surface water. If you store oil, paint, solvents, fertiliser or waste, those costs can exceed the fire damage itself, while the fire policy pays only for the building and the contents. The water authority or the local council can also recover the cost of cleaning the sewer system from you. For storage of this kind, environmental damage cover environmental damage cover is a basic requirement, not an extension.
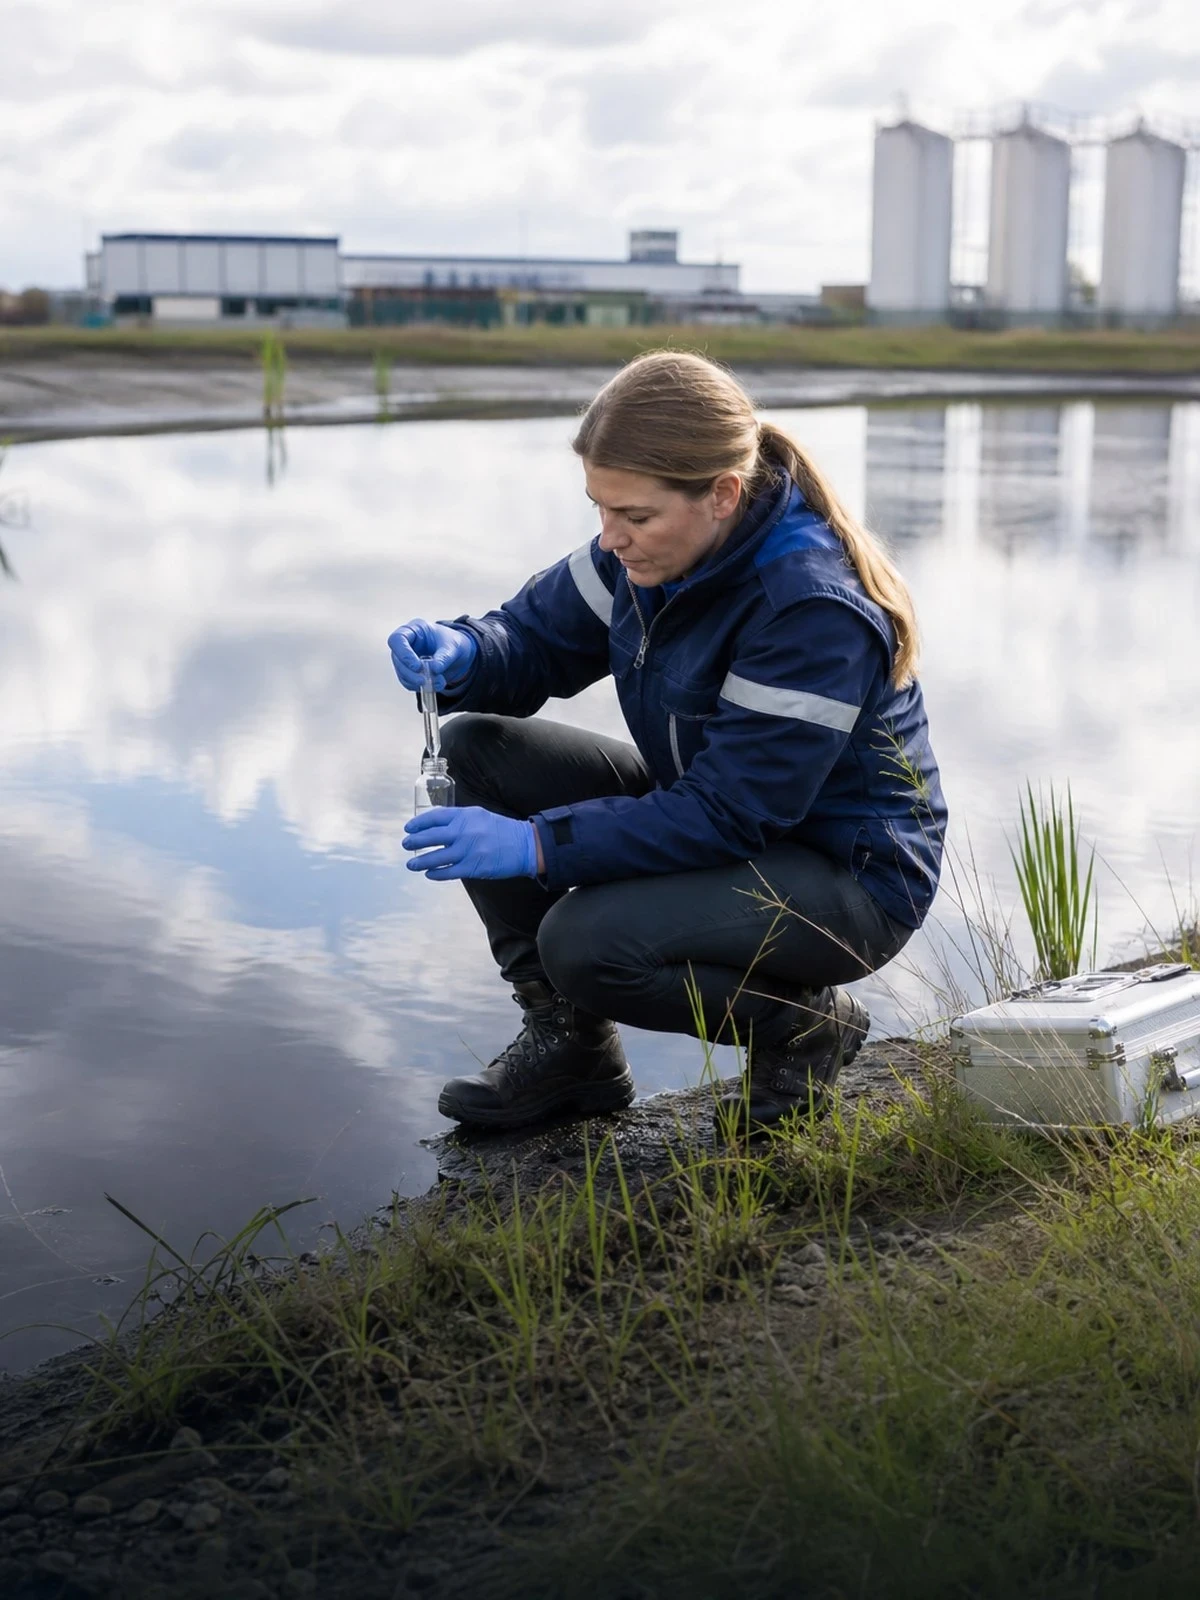
For underground and above-ground tanks, insurers set requirements for certification, periodic inspection and leak detection. If a valid inspection certificate is missing, or a tank was not installed in line with the applicable assessment guideline, cover for that installation can lapse. The same applies to liquid-tight floors and drip trays at storage areas. Have inspection dates recorded and keep the reports; after a loss they are the first thing you will be asked for.
Excluded are contamination that was already present at inception or that arose gradually, known defects you have not put right, and asbestos built into buildings. Fines and penalty payments imposed by an environmental agency cannot be insured, nor can intent or deliberate breach of a permit condition, in view of Article 7:952 of the Dutch Civil Code. Loss of turnover during the clean-up is covered only under a separate extension.
This is what people ask us most.
Only in so far as a third party suffers loss and you are liable for it. Contamination on your own site does not create liability, while the authorities can still enforce a clean-up. Many liability policies also exclude environmental damage altogether. This policy was designed for exactly that situation and works without any need to establish fault.
It is a soil survey that records what is already in the ground at inception. Without that measurement it is impossible, after a loss, to establish what is new and what was already there, and the risk stays with you. Insurers ask for one above all where there is high-risk storage, on older sites and when a business is taken over.
In principle he is liable and you approach his insurer. If he turns out to be uninsured or denies responsibility, your own environmental damage cover can advance the cost of the clean-up and then seek recovery. For work you carry out at a client's premises you need the third-party sites section. Without it, only your own address is covered.
No. Administrative fines and penalty payments are by their nature uninsurable, because insuring them would remove their punitive effect. What is covered are the costs of investigation, clean-up and reinstatement arising from the enforcement decision, plus the costs you incur to mitigate the loss and prevent further spread. So report any enforcement notice immediately.
Every situation is different. For these situations we have a separate page.
Request a quote without obligation. We will look at which insurer best matches your activities and your risk.
Prefer to call? 072 - 509 24 56, weekdays 09:00–17:00.
Claim on the road? Emergency line 06 - 55 20 40 72.
Finass Verzekert is a trading name of Finass Advies B.V. We advise on and arrange non-life insurance on the basis of an objective analysis of several insurers, and receive commission for this from the insurer, which is included in the premium. You pay no separate advice fee. Before you take out cover, we establish your wishes and needs.
You will find our licence, KvK and Kifid details and our complaints procedure at the foot of every page.
This page was compiled by Finass Verzekert (LinkedIn). Last updated on .
The information on this page is general in nature and is not personal advice.
Maandag- Vrijdag: 09:00- 17:00
We use cookies and similar technologies to improve your experience on our website.