

Clean-up of your own site
- Soil investigation, remediation plan and supervision by an expert
- Excavating, removing and backfilling soil, including asbestos removal
- Pumping up and treating groundwater
As the owner of let commercial property, you are left with a contaminated site if the tenant caused the damage and can no longer be held to account.
This page in another language: Nederlands
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
Business quote request. A no-obligation request: nothing is taken out automatically. After sending you receive a reference number and a confirmation by e-mail.
Additional questions follow per chosen insurance.
Additional questions follow per chosen insurance.
Additional questions follow per chosen insurance.
Additional questions follow per chosen insurance.
For owners of and investors in commercial property, soil contamination directly affects the value of a building. A tenant whose tank leaks, firefighting water containing combustion residues after a fire or a burst oil pipe in a workshop can lead to investigation and remediation. Since the Omgevingswet (Environment and Planning Act), the duty of care has been linked to activities: under Article 2.11 of the Besluit activiteiten leefomgeving (Environmental Activities Decree), anyone carrying out an environmentally harmful activity must prevent and undo contamination, and the municipality is in principle the competent authority. If that polluter is bankrupt or has disappeared, the problem is yours as owner: a contaminated site is difficult to let, finance and sell.
Unlike our general page on environmental damage insurance, which concerns your own business, here the policy is in the owner's name. Environmental damage insurance (milieuschadeverzekering, MSV) is a first-party insurance: it pays remediation costs at the insured location without liability first having to be established. You choose between basic cover (fire, lightning, explosion), extended perils cover and top cover.
Note two exclusions that weigh heavily for landlords: Avéro Achmea's conditions exclude activities of landlords and co-tenants unless otherwise agreed, as well as damage caused by underground storage in tanks. We review the use and soil data for each property and tailor the policy accordingly.
We compare your environmental damage insurance across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
 Environmental damage insurance
 Compare
 Get covered
The cover for your property depends on the use by tenants, the condition of the soil at the start and the location in relation to neighbours and surface water.
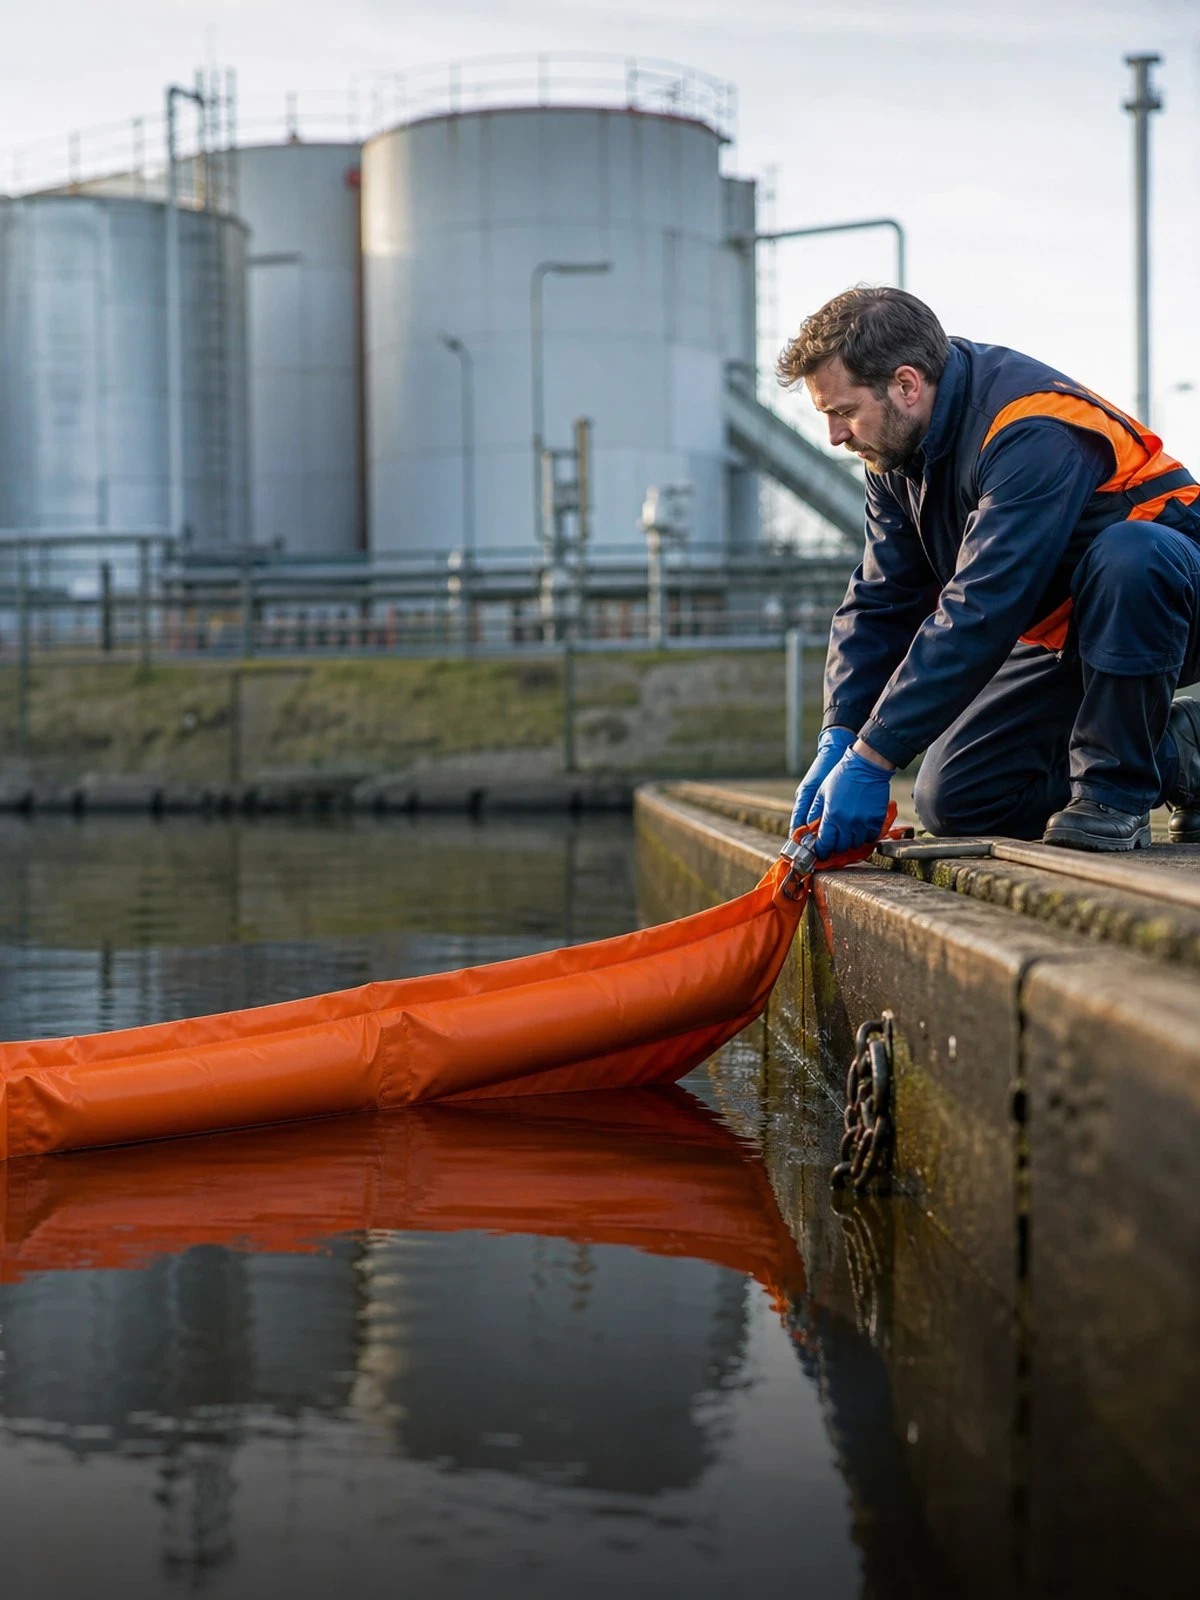
Investigation and remediation of soil, groundwater and surface water at the insured address after a covered emission.
Contamination that has spread from your site to land or water belonging to others, often with a separate limit.
Costs alongside remediation that are often overlooked with property.
What is covered
| Situation | Basic | Extended |
|---|---|---|
| Sudden leak from an above-ground tank | Yes | Yes |
| Soil contamination after fire and firefighting water | Yes | Yes |
| Gradually leaking underground pipe | No | Provided that |
| Contamination running on to the neighbour's plot | Provided that | Yes |
| Contamination that was already there at purchase | No | No |
| Fall in the value of the plot after clean-up | No | No |
Which locations, substances and installations are actually included is set out in the policy conditions and on the policy schedule. The activities stated per address are decisive in that.
Insurers weigh these details differently. That is where your saving is.
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
You call or email someone who knows your file. No menu options, no changing call centres.
We cancel your old policy and align the start date, so you are never a day without cover.
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
Customers rate our service on four aspects: personal service, service delivery, availability and the outcome. The reviews are collected and published by NH1816 and come from customers who have actually taken out a policy with Finass Advies B.V. or reported a claim.
Four points for owners of commercial property.
The lease often states that the tenant is liable for contamination it causes. That agreement is worth little if the tenant goes bankrupt or has no environmental damage insurance of its own. An MSV in the owner's name then pays for remediation of your own site, and the insurer can seek recovery from the polluter. Do read the exclusions: at Avéro Achmea, activities of landlords and co-tenants are excluded unless otherwise agreed. For a let property, use by tenants must therefore be expressly included in the policy. Also ask every tenant with an environmental risk for a copy of its own policy schedule.
An MSV does not cover contamination that was already present. Insurers therefore often ask at the start for an exploratory soil investigation in accordance with NEN 5740 or a recent report from the municipality's soil records. For you as owner, that investigation has a second function: it records who is responsible for what. A soil investigation when a tenant moves in and out makes contamination attributable to a period and therefore to a party. Without a baseline measurement, it is almost impossible to show after damage that the contamination is new, and the insurer may then dispute cover.
Underground storage of substances in tanks is excluded in the Avéro conditions, even under top cover. Above-ground tanks and silos are covered under extended perils cover, as is the filling of fixed above-ground tanks. Top cover also covers inherent defects due to design, construction or material faults, but for installations, machinery and pipes only if the contamination becomes apparent within five years of installation or renewal, and provided maintenance obligations have been met. If there is still an old underground tank on your site from a previous tenant, have it remediated or removed before you apply for an MSV.
An MSV has short time limits. Under the Avéro conditions, a claim must be submitted within one year of the emission, and after the policy ends there is only cover if the contamination becomes apparent within one year. If you sell a building, cover for that property therefore continues only briefly. The remediation order must be placed within the period set by the insurer; otherwise the right to compensation lapses. For an owner with tenants, this means: agree that tenants report incidents immediately, so that you do not discover only at the end of the lease that something has happened.
Questions property owners ask us about environmental damage.
The duty of care under the Omgevingswet rests with whoever carries out the activity, so as a rule the tenant; the municipality can require that polluter to restore the situation and submit a plan of action. If the tenant cannot pay or no longer exists, you as owner are left with a site that will still need remediation when it comes to letting, financing and sale. An MSV in the owner's name covers those remediation costs, provided use by tenants is included in the cover.
Only partially. Buildings insurance (opstalverzekering) pays clean-up costs after a fire, but soil and groundwater remediation on your own site is usually excluded or limited. Business liability insurance (AVB) only covers damage to third parties. The MSV is supplementary: at Avéro Achmea it applies in excess of other insurance, and the excess on those other policies is not reimbursed.
Basic cover pays for remediation after fire, lightning and explosion. Extended perils cover adds, among other things, storm from 14 metres per second, collision, burglary, vandalism, power surges, breakage of tanks and silos and the loading and unloading of closed containers. Top cover covers all sudden external events and inherent defects. For tenants who use oil, chemicals or fuel, top cover makes sense; for office lettings the extended variant is often sufficient.
Some policies include business interruption cover within the MSV; at Avéro Achmea for up to 52 weeks from the start of remediation. Whether that also includes lost rent for a landlord depends on the policy wording, so we agree this in advance. In addition, mitigation costs to prevent contamination from spreading are covered up to 110 percent of the sum insured per emission.
Set out which activities and which storage of hazardous substances are permitted, that no underground tanks will be installed, that the tenant is liable for contamination during the lease, that incidents are reported to you immediately and that a soil investigation takes place at the start and end. Ask the tenant for its own MSV and a copy of the policy schedule. This strengthens your position for recovery and gives the insurer the baseline situation it asks for.
Every situation is different. For these situations we have a separate page.
Request a quote without obligation. We set out side by side, per insurer, what counts as sudden and what counts as gradual.
Prefer to call? 072 - 509 24 56, weekdays 09:00–17:00.
Claim on the road? Emergency line 06 - 55 20 40 72.
Finass Verzekert is a trading name of Finass Advies B.V. We advise on and arrange non-life insurance on the basis of an objective analysis of several insurers, and receive commission for this from the insurer, which is included in the premium. You pay no separate advice fee. Before you take out cover, we establish your wishes and needs.
You will find our licence, KvK and Kifid details and our complaints procedure at the foot of every page.
This page was compiled by Finass Verzekert (LinkedIn). Last updated on .
The information on this page is general in nature and is not personal advice.
Maandag- Vrijdag: 09:00- 17:00
We use cookies and similar technologies to improve your experience on our website.