

Liability
- Cables and pipes
- Damage to buildings
- Injury to bystanders
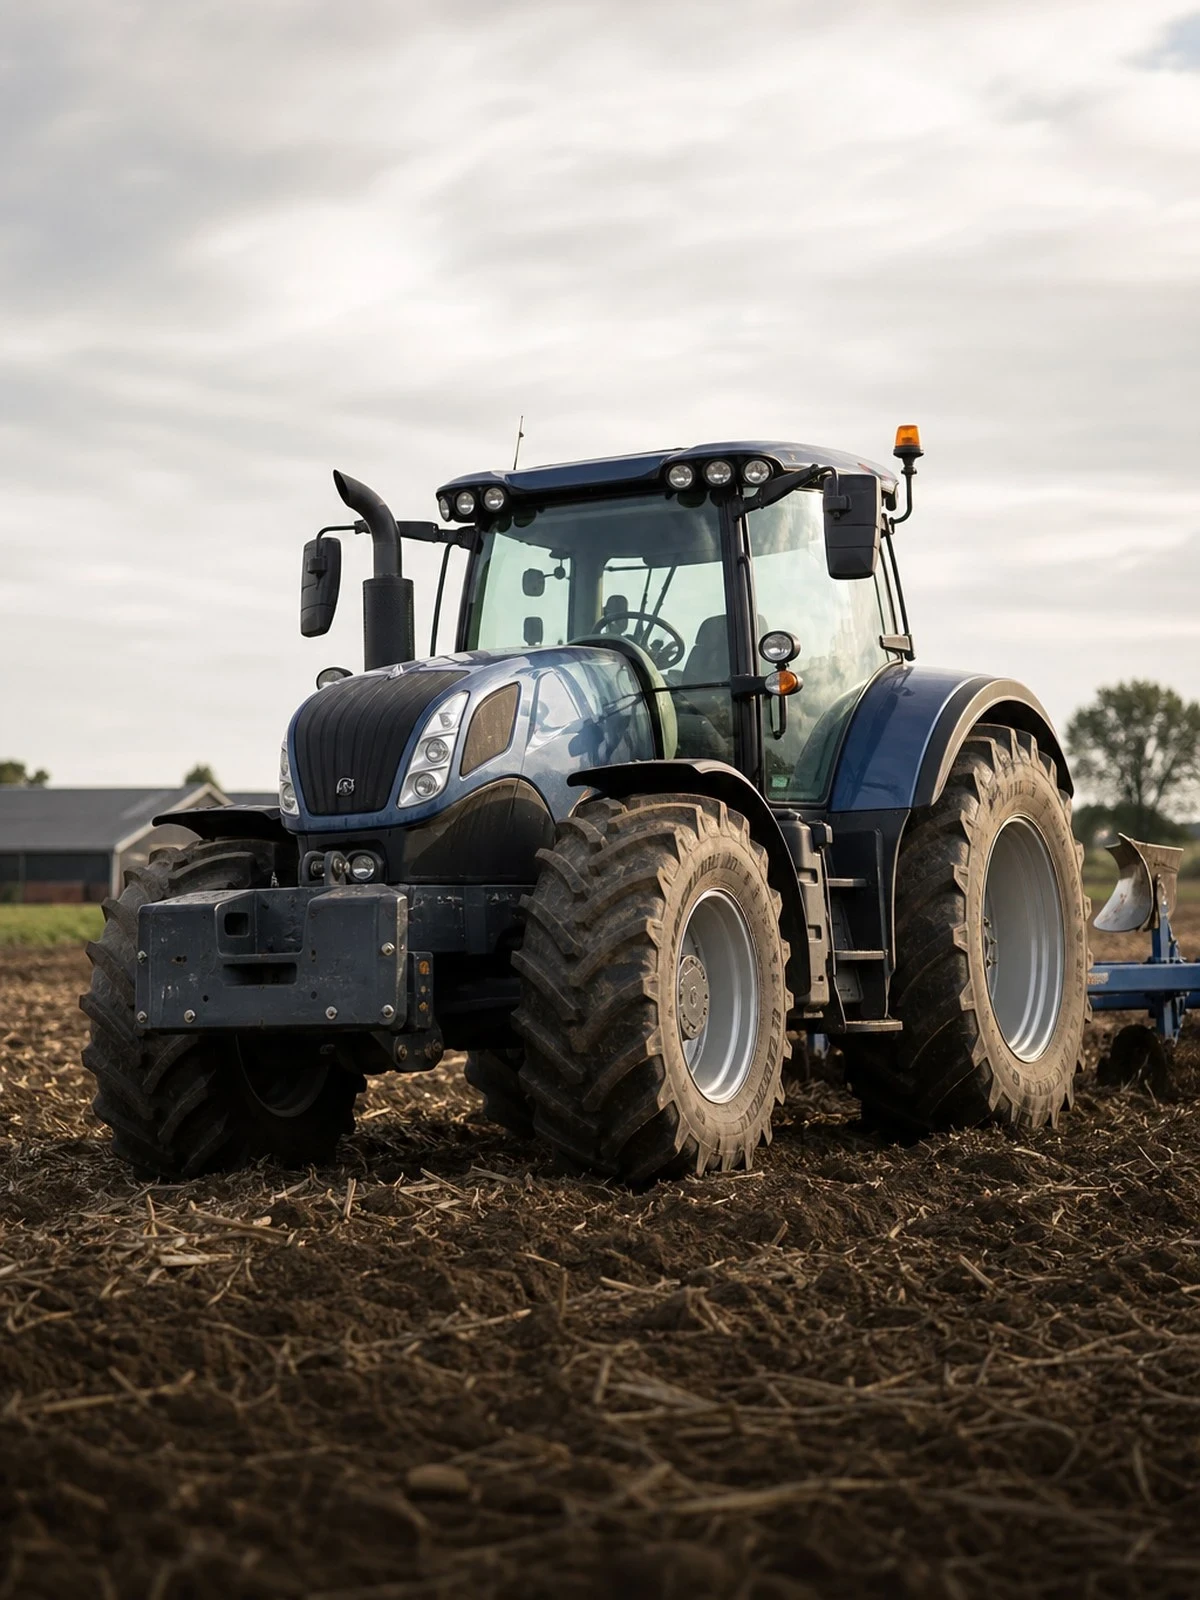
A tractor is the only machine in this series that is subject to registration and at the same time tows an implement behind it that is often worth more than the tractor itself.
This page in another language: Nederlands
The calculator and the quote form below are in Dutch. Prefer to do this in English? Email info@finassverzekert.nl or call 072 - 509 24 56 and we will take it from there.
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
Since agricultural and forestry vehicles have been subject to registration, insuring a tractor is no longer a grey area. If the tractor goes onto the public road, the compulsory liability insurance under Article 2 of the Dutch Motor Insurance Liability Act (WAM)applies, with everything that goes with it: registration, valid insurance and a driver with the right entitlement. On your own yard and on the land that obligation does not apply, but the liability continues as normal.
What does remain grey is what is towed behind. A tipping trailer, slurry tanker, sprayer, forage harvester or baler is generally not automatically insured on the tractor policy. The WAM cover on the tractor extends to damage the combination causes to third parties, but own-damage to the coupled implement itself has to be declared separately. Anyone who runs an expensive combination on a standard policy only discovers that after it overturns in a verge.
The third point is the driver. Driving on the road requires a category T licence, with a minimum age. If someone who was not entitled to drive is at the wheel when an accident happens, the WAM cover towards the victim stands, but the insurer can recover the amount paid from you. Enthusiasts' vehicles have a regime of their own: see insuring a hobby tractor.
We compare your plant and machinery insurance across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
 Plant and machinery insurance
 Compare
 Get covered
The structure of the cover in three parts, with an overview per situation below.
Damage you cause to others with the machine.
Damage, theft and usually inherent defect as well.
What matters besides the machine itself.
What is covered
| Situation | Liability | Own-damage cover |
|---|---|---|
| Damage to a building or installation | Yes | No |
| Theft of the machine | No | Sometimes |
| Fire or storm damage | No | Yes |
| Inherent defect or operating error | No | Sometimes |
| Worn tracks, tyres and teeth | No | No |
| Damage due to deferred maintenance | No | No |
This overview is general in nature and is not personal advice. What is actually covered, including exclusions, limits and the excess, is set out in the policy conditions and the insurance card (verzekeringskaart) of the insurer; you receive both before you take out cover. Taking out cover without advice? Then read what execution only means for you.
Insurers weigh these details differently. That is where your saving is.
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
You call or email someone who knows your file. No menu options, no changing call centres.
We cancel your old policy and align the start date, so you are never a day without cover.
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
Customers rate our service on four aspects: personal service, service delivery, availability and the outcome. The reviews are collected and published by NH1816 and come from customers who have actually taken out a policy with Finass Advies B.V. or reported a claim.
Four points that make the difference between a policy that pays out and one that does not.
A modern sprayer, forage wagon or slurry tanker often represents a larger sum than the tractor. For damage to third parties the combination is generally included under the WAM cover, but own-damage to the implement itself is not. Declare each implement separately with its year of manufacture and value, including seasonal implements that stand under a lean-to for most of the year and are stolen precisely then.
A tractor with a wide combination on a narrow road is taking part in traffic. If you collide with a cyclist or a car, fault is assessed as in a road accident, including the special protection given to non-motorised road users. If you lose load, mud or manure on the road surface and an accident results, that is an unlawful act within the meaning of Article 6:162 of the Dutch Civil Code and not merely an offence.
If you work for third parties, liability arises that does not exist on your own farm: damage to the customer's crop, compaction of fields, incorrectly applied fertiliser or drift of crop protection products onto an adjoining plot. That is often damage to property you were working on and therefore care, custody and control. So declare contract work expressly; a policy based on your own agricultural use does not cover it.
Damage arising because the driver held no valid entitlement can be recovered from you. Wearing parts such as tyres, clutches and blades are excluded. Damage to the crop or the ground being worked falls under care, custody and control. And if you travel on the road with an expired trailer inspection or without proper lighting, that affects the acceptance conditions and the assessment of your own share.
Verge mowing, snow clearing and haulage on the road are separate activities that you have to report.
Tracks, tyres, blades, teeth and cutting edges are wear parts and are not insured anywhere; only sudden damage is covered. Deferred maintenance is also a ground for exclusion. A demonstrable maintenance regime with a logbook is therefore not only good management but also strengthens your position in a claim.
This is what people ask us most.
For taking part in traffic, yes: Article 2 of the Dutch Motor Insurance Liability Act (WAM) requires liability cover for every motor vehicle subject to registration. If the tractor stays exclusively on your own yard and land, that obligation falls away, but not your liability for injury and damage. An uninsured tractor that is subject to registration also produces a register check and a penalty.
For damage to third parties a coupled implement is generally included under the tractor's third-party liability cover. For damage to the implement itself that is not the case: that is an own-damage item in its own right that you have to declare with its value. With expensive sprayers, slurry tankers and forage wagons that is the difference between a manageable loss and an unpaid one.
The injured party is protected by the WAM and has the damage paid. The insurer can then recover the amount paid from the policyholder or the driver, because driving without a valid entitlement is a policy exclusion. So record who may take which vehicle onto the road and check that for seasonal workers.
Yes. Working for third parties brings liability for crop damage, structural damage to soil and incorrectly performed operations, usually as damage to property in your care. A policy taken out on the basis of your own agricultural use does not cover that. Report the activity in advance: concealment affects the duty of disclosure in Article 7:928 of the Dutch Civil Code and with it the payout.
Every situation is different. For these situations we have a separate page.
Request a quote without obligation. We will look at which insurer best matches your activities and your risk.
Prefer to call? 072 - 509 24 56, weekdays 09:00–17:00.
Claim on the road? Emergency line 06 - 55 20 40 72.
Finass Verzekert is a trading name of Finass Advies B.V. We advise on and arrange non-life insurance on the basis of an objective analysis of several insurers, and receive commission for this from the insurer, which is included in the premium. You pay no separate advice fee. Before you take out cover, we establish your wishes and needs.
You will find our licence, KvK and Kifid details and our complaints procedure at the foot of every page.
This page was compiled by Finass Verzekert. Last updated on .
The information on this page is general in nature and is not personal advice.
Maandag- Vrijdag: 09:00- 17:00
We use cookies and similar technologies to improve your experience on our website.