

Third-party liability
- Compulsory under Article 2 of the Dutch Motor Insurance Liability Act (WAM)
- Also personal injury to third parties
- No cover for your own car
- Suitable where the market value is low
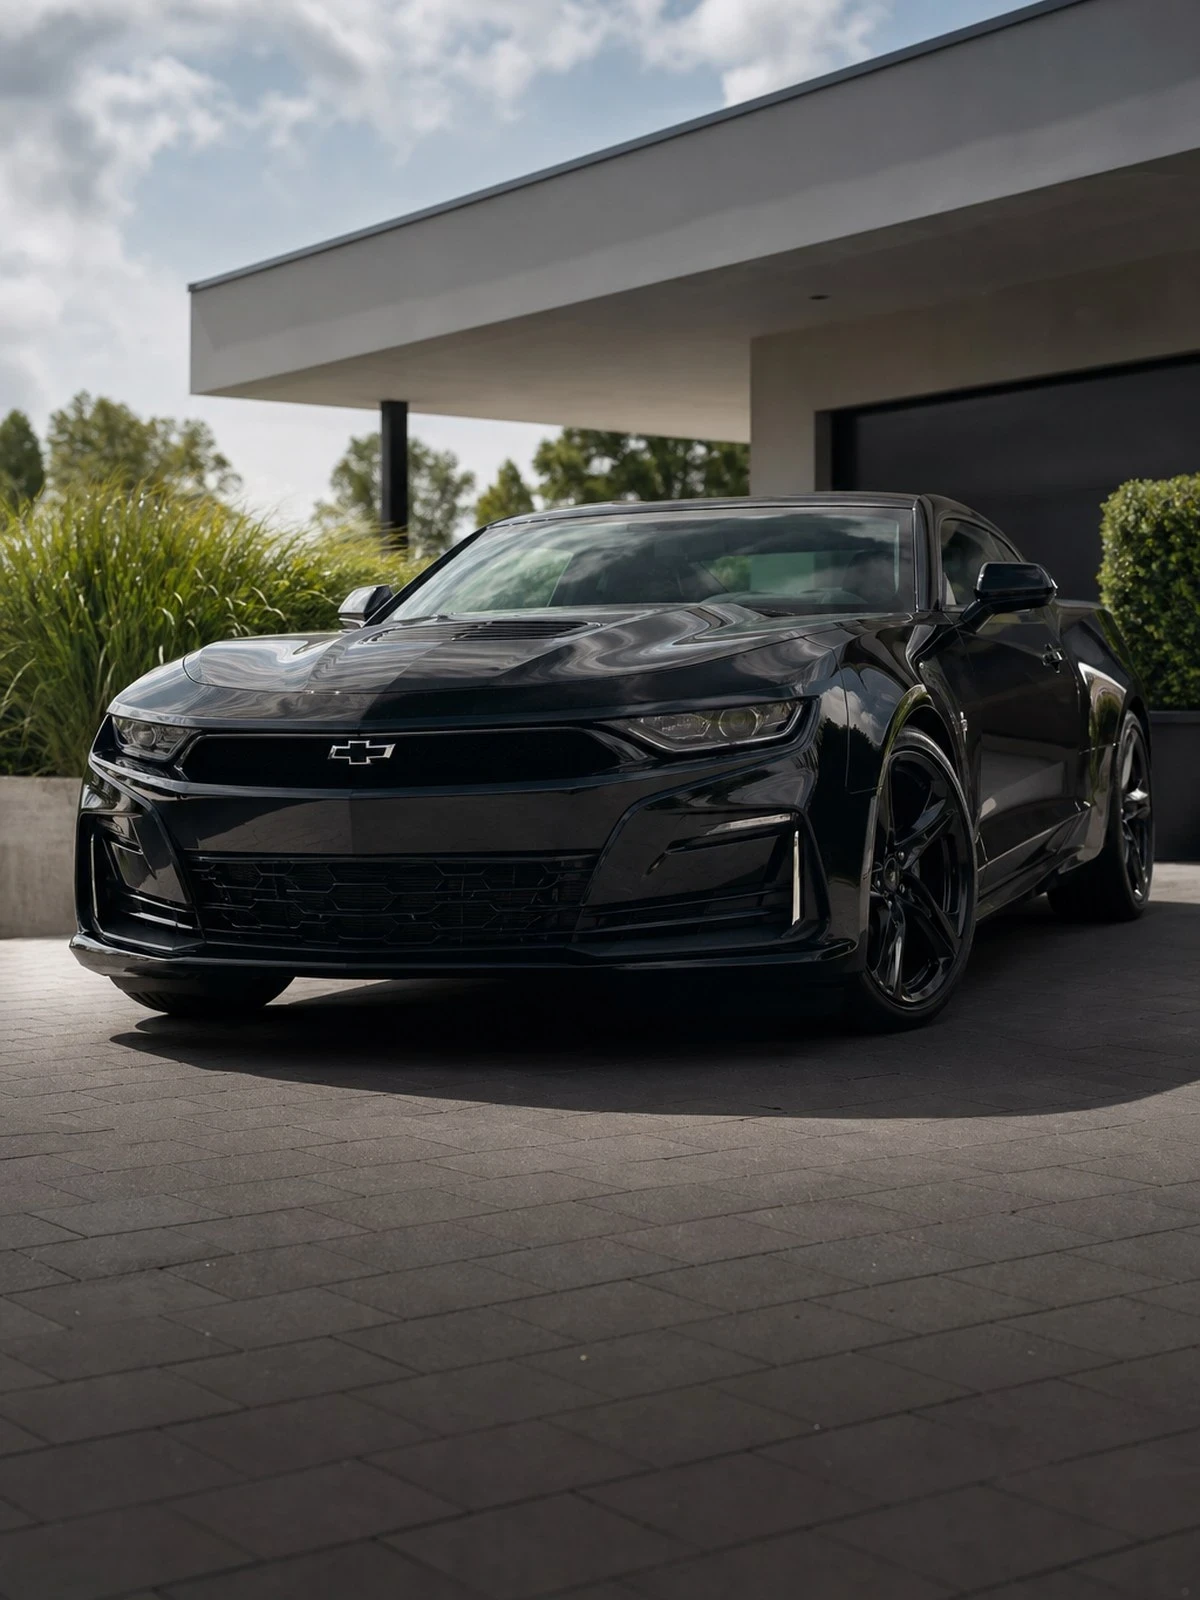
Very different cars sit under one badge: a compact Spark, a Captiva and a Camaro with a V8. For the insurer those are three separate products with their own premium groups.
This page in another language: Nederlands
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
The Chevrolet fleet in the Netherlands consists of two very different groups. The first is the European-supplied range — models such as the Spark, Aveo, Cruze, Orlando and Captiva — which sits close to comparable volume cars in premium group. The second group consists of American models, usually imported: the Camaro, Silverado, Tahoe and older V8 versions. There, list price, power and weight weigh heavily and acceptance varies from insurer to insurer. Insurance is always based on the registration number and the version, not on the badge.
For both groups the supply of partsmatters. Chevrolet has withdrawn from the western European market, so the dealer network here is limited. Parts more often come from abroad and that lengthens repair times. So look at the arrangements for replacement transport and at the maximum period for it, and have it recorded whether you have a free choice of repairer. With older and imported examples, how the value is established on a total loss is at least as important as the premium.
Two practical points come up often with this make. Many V8 versions run on LPG; an installation that has been fitted must be declared and may lead to a loading or additional inspection requirements. And with an import the specification and original list price differ from the Dutch reference, so that price guides give an unreliable picture. A valuation beforehand then fixes the value under Article 7:960 of the Dutch Civil Code. As to the premium, 21% insurance premium tax.
We compare your car insurance across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
 Car insurance
 Compare
 Get covered
The choice depends on the value, the age and the origin of the car.
The legally required cover for damage you cause to others.
A fixed list of events: theft, fire, storm, glass and collision with animals.
Also damage you cause yourself. For imports or youngtimers preferably on an agreed value basis.
What is covered
| Situation | Third-party liability | Comprehensive |
|---|---|---|
| Damage you cause to someone else | Yes | Yes |
| Theft, fire or storm damage | No | Yes |
| Damage to your Chevrolet that you cause yourself | No | Yes |
| Damage to a declared LPG installation | No | Provided that |
| Payment at agreed value on a total loss | No | Provided that |
| Engine damage or wear without a collision | No | No |
What is actually covered, including exclusions, limits and the excess, is set out in the policy conditions and the insurance card (verzekeringskaart) that you receive before you take out cover.
Insurers weigh these details differently. That is where your saving is.
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
You call or email someone who knows your file. No menu options, no changing call centres.
We cancel your old policy and align the start date, so you are never a day without cover.
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
Customers rate our service on four aspects: personal service, service delivery, availability and the outcome. The reviews are collected and published by NH1816 and come from customers who have actually taken out a policy with Finass Advies B.V. or reported a claim.
Four points that regularly lead to discussion among Chevrolet owners.
An example imported from the United States often lacks a Dutch version code with a corresponding list price. The insurer then rates the car manually, with the risk that the power output or the equipment is misjudged. Give the actual specification, engine capacity and options when you apply, and make sure the registration document and the policy match. If there is doubt about the value, a valuation report is the only way to settle that discussion before a loss occurs.
Because of the limited dealer network in the Netherlands, parts more often come from abroad. A repair that is simple in itself can therefore take weeks. Check whether the policy provides replacement transport and for how many days, and whether you may take the car to a repairer of your choice. With older models there is the added point that some parts are only available second-hand; have it recorded how the insurer deals with that.
Outside every motor policy remain: wear and tear and mechanical or electronic defects without a collision, such as a failed transmission or engine damage; taking part in speed, drag or skill events and driving on a circuit, including at a touring event; and driving under the influence or without a valid driving licence. An undeclared LPG installation or increase in power output may lead to refusal, and damage caused by intent or recklessness is excluded under Article 7:952 of the Dutch Civil Code.
An LPG installation, a modified exhaust, different wheels or an increase in power output change the risk. Declare them before the modification: when you take out the policy the duty of disclosure of Article 7:928 of the Dutch Civil Code and a breach can reduce or void the payout (Article 7:930 of the Dutch Civil Codeapplies). For desirable models such as the Camaro, insurers sometimes impose requirements for an alarm or tracking system. If these are not met, theft is not covered. Report a claim as soon as reasonably possible (Article 7:941 of the Dutch Civil Code).
This is what people ask us most.
Not impossible, but more selective. Not every insurer accepts imported models with a large engine, and some impose requirements on age, no-claims years or security. With manual rating the premium also varies considerably between insurers. So have the application put to several insurers rather than relying on one online calculation.
As soon as the value does not follow reliably from price guides: for imports, for youngtimers and classics and for examples that have been restored or modified. The valuation fixes the value for the period stated in the policy, under Article 7:960 of the Dutch Civil Code. Without a valuation the insurer pays market value on a total loss, with all the argument that entails.
Yes, even if it was already fitted when you bought the car. An LPG installation is a change in the risk and must appear in the policy. Some insurers charge a loading or require a valid inspection certificate. Failing to declare it can lead to refusal for fire or explosion damage. Bear in mind too that a fuel surcharge applies to LPG in the vehicle tax.
With many insurers that is possible once the car reaches a certain age, usually combined with conditions: a maximum annual mileage, a second car for daily use, a minimum driver age and sometimes a requirement about where it is kept. In return the premium is lower and the car is more often insured at an agreed value.
Only if that has been agreed. Many policies leave the choice to the insurer or to the repair network it works with, in which case used or alternative parts may be fitted. If you want original parts or a particular repairer, have that expressly included in the policy. With older models this matters more than the difference in premium.
Every situation is different. For these situations we have a separate page.
Request a quote without obligation using your registration number. We will put the import, LPG and valuation to insurers that accept them.
Prefer to call? 072 - 509 24 56, weekdays 09:00–17:00.
Claim on the road? Emergency line 06 - 55 20 40 72.
Finass Verzekert is a trading name of Finass Advies B.V. We advise on and arrange non-life insurance on the basis of an objective analysis of several insurers, and receive commission for this from the insurer, which is included in the premium. You pay no separate advice fee. Before you take out cover, we establish your wishes and needs.
You will find our licence, KvK and Kifid details and our complaints procedure at the foot of every page.
This page was compiled by Finass Verzekert (LinkedIn). Last updated on .
The information on this page is general in nature and is not personal advice.
Maandag- Vrijdag: 09:00- 17:00
We use cookies and similar technologies to improve your experience on our website.