

Liability insurance for a self-employed welder
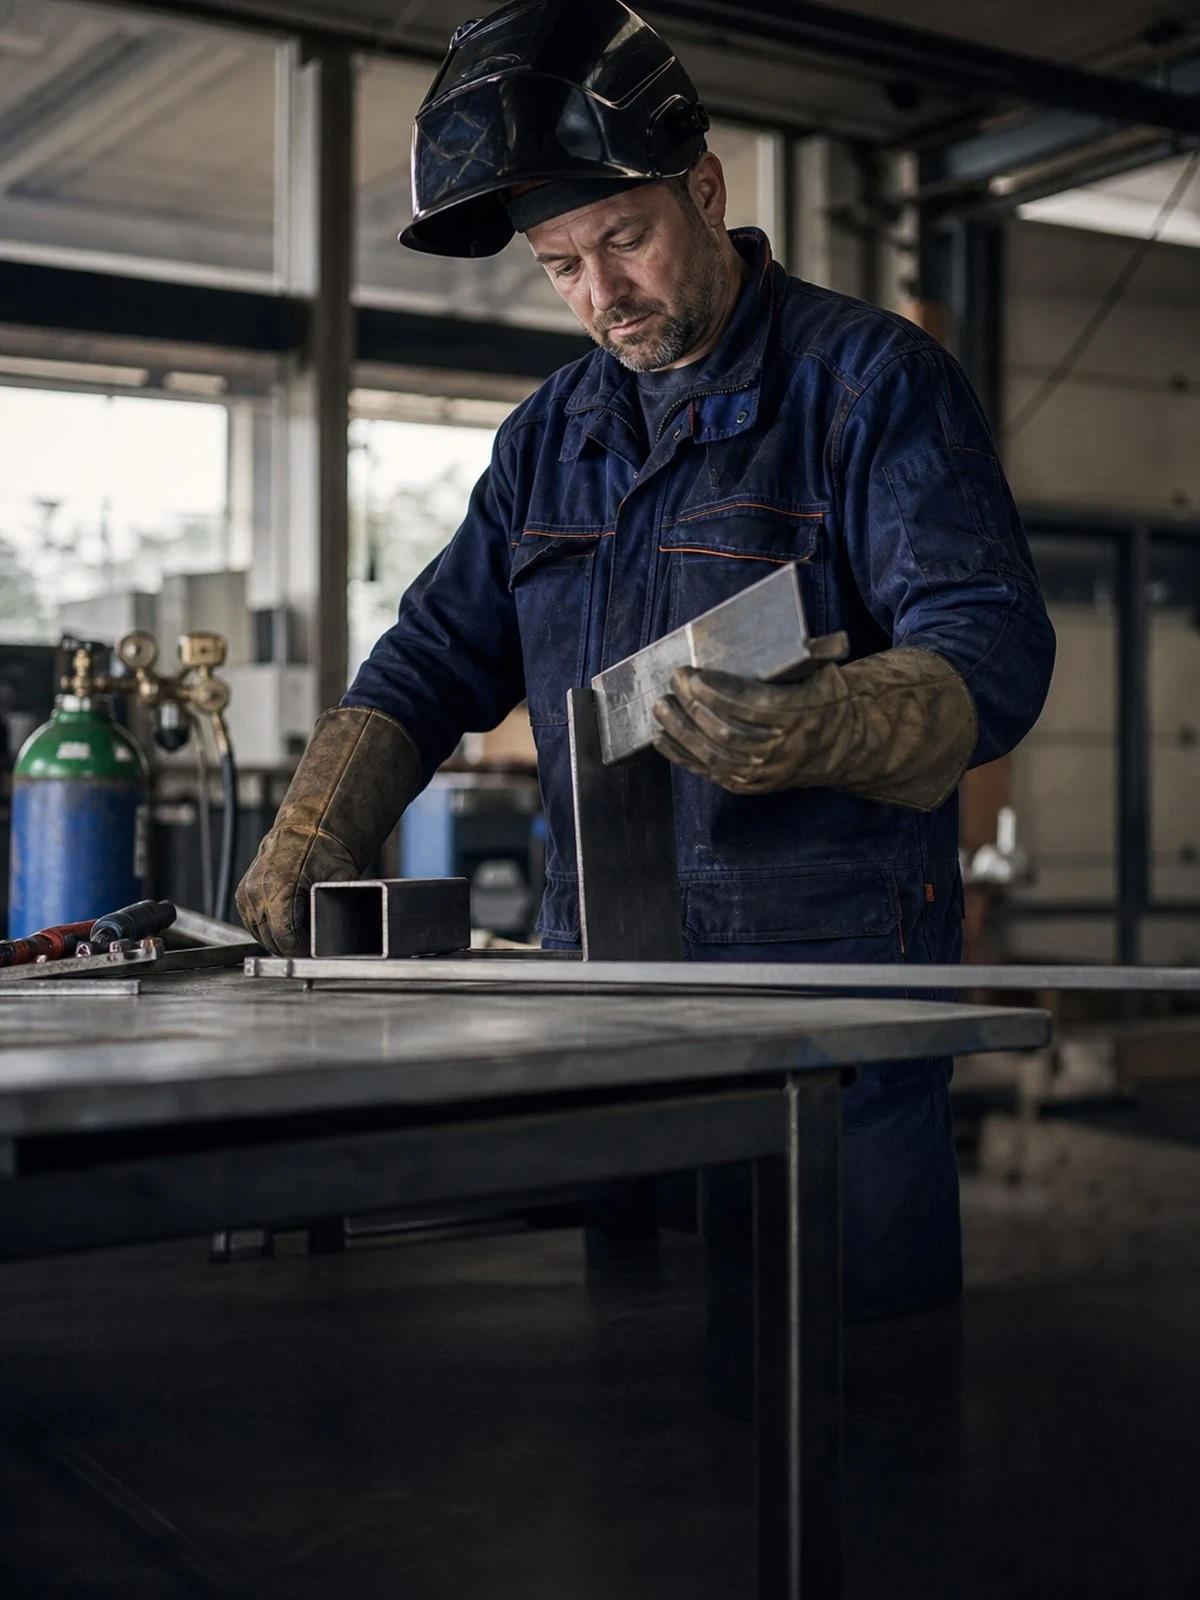
As a self-employed welder you often work alone, in a customer's garage or at the back of a yard. That means no fire watch behind you and no colleague looking over your shoulder, and that is exactly where the insurance conversation lies.
- Several insurers compared objectively
- 9.5 customer rating for a new policy
- AFM licence 12016589
- Personal 072 - 509 24 56, weekdays 9–17
This page in another language: Nederlands
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
- We compare the offerings of several insurers
- An adviser checks whether the cover suits your activities
- We arrange the switch, including cancellation
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
- Independent advice
- Several insurers
- Switching arranged
- Help with claims
In brief
Working without staff takes one section off your policy: employers' liability under Article 7:658 of the Dutch Civil Code does not arise for you. What remains is your liability towards third parties under Article 6:162 of the Dutch Civil Code: the shed that catches fire, the window frame hit, the visitor who trips over your cable. That is what the AVB is intended for. Your own injury does not fall under it. If you cannot work for three months, no liability policy pays for that.
Working alone makes the follow-up check your weak point. A smouldering fire often starts only after you have left, and without a second person there is no one keeping an eye on the surroundings while you weld. Insurers therefore set requirements: screening, extinguishing equipment within reach and a check afterwards. If you cannot organise that on a job, plan the job differently. The exclusion where fire clauses have not been complied with operates at exactly the moment the loss is large.
Three items stay at your expense in any event. Making your own weld again is performance of the contract and not an insured loss. A customer's workpiece standing in your workshop falls under the care, custody and control exclusion. And liability you carry solely by virtue of signed subcontracting conditions is contractual liability and not insured. You insure your own tools and welding equipment separately through tools insurance.
This page deals with one situation. The full overview is on Compare public and employers' liability insurance (AVB).
Independent, personal, sorted quickly
We compare your business liability insurance (AVB) across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
 Business liability insurance (AVB)
 Compare
 Get covered
Why arrange it through Finass Verzekert?
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
Independent
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
One fixed adviser
You call or email someone who knows your file. No menu options, no changing call centres.
Switching without hassle
We cancel your old policy and align the start date, so you are never a day without cover.
Help with claims
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
What to watch when you are alone on the job
Four situations that go wrong more often for a self-employed welder than for a company with a gang.
At private customers' homes
Work on a gate, carport or staircase often takes place close to timber, insulation and stored belongings. Damage to the house may be covered for the customer on his own buildings insurance, but that insurer will recover the loss from you. Without liability cover you receive that recovery claim directly.
The workpiece you take away
If you take a gate, trailer or machine frame to your own workshop, you have someone else's property in your care. Damage during transport or working on it falls under care, custody and control. Cover for property being worked on or transit cover fills that gap; ask about it before you load the first workpiece.
Subcontractor for a main contractor
If you work for a main contractor, there are usually conditions with an indemnity, an insurance requirement and sometimes a penalty for delay. Liability going beyond what the law imposes on you is excluded. Read in advance which sum insured is required, because a limit that is too low means you formally may not carry out the work.
Delay is not property damage
If a haulage company cannot use a trailer for a week because a repair failed, the turnover lost is pure financial loss. That is not an AVB loss. Only where something is damaged and that damage is covered does the injured party's consequential loss come into play.
What does your premium depend on?
- Turnover or days worked: the usual basis for a sole trader
- Share of work done on site: welding at third-party sites weighs more heavily than in your own workshop
- Type of clients: private customers, small businesses or industry
- Property being worked on included: for workpieces you have in your care
- Your own terms of supply: these limit what you take on by contract
- Sum insured and excess: per claim and per insurance year
Insurers weigh these details differently. That is where your saving is.
What is covered
| Situation | Basic | Extended |
|---|---|---|
| Your grinding sparks damage the paintwork of the car on the customer's drive | Yes | Yes |
| A visitor to the building site is injured when a section of fencing that has not yet been fixed falls over | Yes | Yes |
| Three hours after you leave, a smouldering fire breaks out in the cavity of the shed | Provided that | Provided that |
| The customer's gate standing in your workshop distorts through heat | No | Provided that |
| You fall while fitting the ladder and break your wrist | No | No |
| The customer charges the hire of a replacement trailer for the days your repair is being redone | No | No |
Extended means a policy with cover for property being worked on. With fire the outcome still depends on the clause you complied with.
Frequently asked questions
This is what people ask us most.
As a sole trader, am I required to have liability insurance?
Not as a matter of law. In reality almost all business clients require a valid policy schedule before you can start, and private customers ask for it more and more often. The reason behind it matters more: a fire arising from your work easily runs up to an amount a sole trader cannot bear, and you are liable for it with your private assets.
Does the policy cover rewelding a rejected weld?
No. Putting your own work right is performance of the contract, not damage to someone else. Insurers exclude this under the provision on work carried out and goods supplied. What that weld causes elsewhere, injury or damage to other property when the structure failed for instance, can fall within cover.
What if I am injured myself at work?
Public and employers' liability insurance pays nothing then. It is intended for the losses of others. As a self-employed person you have no employer liable under Article 7:658 of the Dutch Civil Code. If you work regularly under a client's direction, subsection 4 of that article can offer a way through, but do not rely on it as an income provision.
Do I have to report that I also work at height or in confined spaces?
Yes. Activities that clearly increase the risk should be declared on your application. Article 7:928 of the Dutch Civil Code places a duty of disclosure on you and Article 7:930 DCC governs what happens if it is not complied with: the insurer can reduce or refuse payment. Report a change during the period of cover as well.
Every situation is different. For these situations we have a separate page.
- Compare public and employers' liability insurance (AVB)The main page
- Liability insurance for a welding companyThe workshop, structures supplied, hot work
- Liability insurance for a self-employed crane operatorSomeone else's machine, hiring in, lifting plans
- Liability insurance for a self-employed mechanicProperty being worked on, call-out service, downtime
- Liability insurance for a pipe fitting companyPrefabrication, spools supplied, subcontracting
- Liability insurance for a self-employed electricianSubcontracting, your own injury, care, custody and control
- Liability insurance for a welder in the petrochemical industryWork permits, downtime, soil
- Public and employers' liability insurance (AVB) for weldersNaked flames, care, custody and control, consequential loss
- Liability insurance for a self-employed professional in the contracting tradeSubcontracting, care, custody and control, indemnity