

What determines the premium for your buildings insurance (opstalverzekering)?
The rebuild value is the basis, but the construction type and the use determine the rate applied to it.
This page in another language: Nederlands
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
- We compare the offerings of several insurers
- An adviser checks whether the cover suits your situation
- We arrange the switch, including cancellation
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
- Independent advice
- Several insurers
- Switching arranged
- Help with claims
The basis
The rebuild value determines the amount the calculation is based on. It follows from a rebuild value tool or a valuation.
What determines the rate
The construction type: masonry with a hard roof covering is more favourable than timber or thatch. A thatched roof puts your home in a considerably higher class.
The the year of construction and the state of repair: old electrics and ageing installations are an underwriting question.
The use: owner occupation, letting, room letting or a practice at home are different risk classes.
The location: in areas prone to flooding or near certain industrial activity, a loading may apply.
What you influence yourself
Your excess: higher means a lower premium, although the benefit with buildings insurance is more limited than with a car because the amounts claimed are larger.
Your extensions: glass, landscaping and inherent defect cost premium but cover real risks.
What not to do
Concealing the use or building work to bring the premium down. That is incorrect information under Article 7:928 of the Dutch Civil Code and costs you the cover when you claim, even where the cause is unrelated.
Independent, personal, sorted quickly
We compare your buildings insurance across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
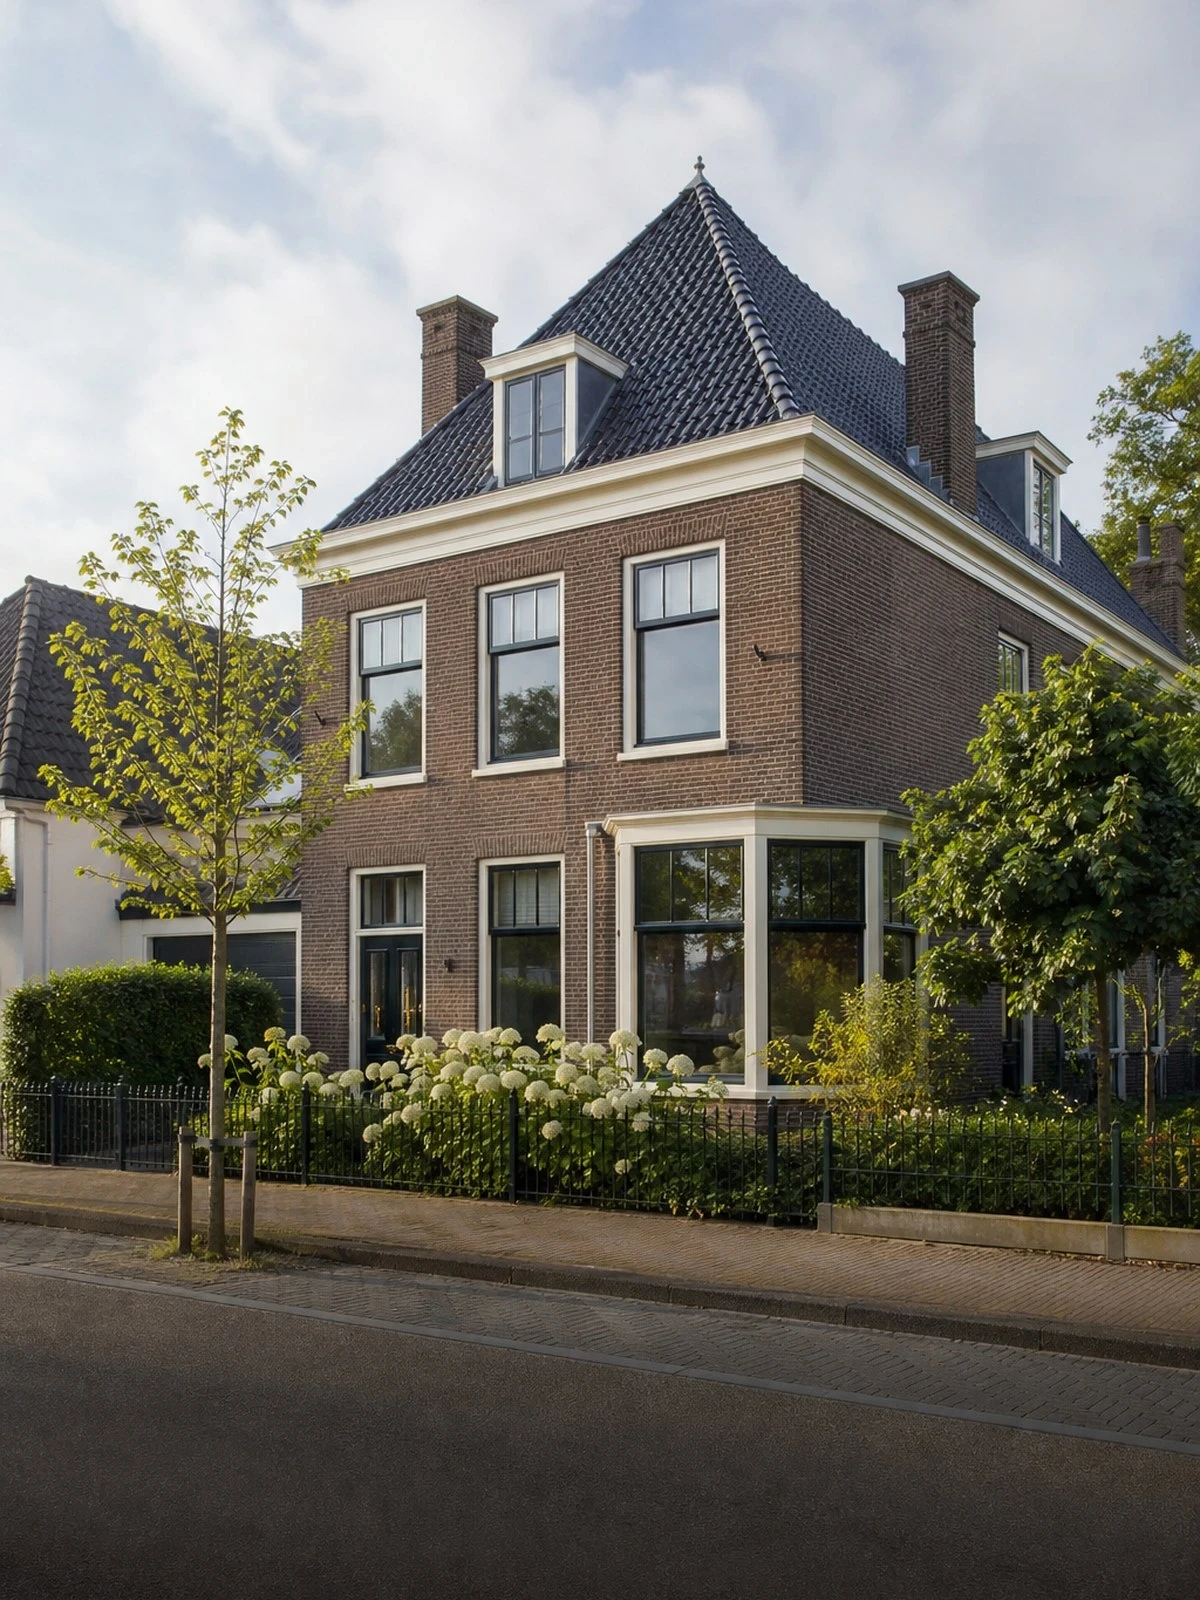 Buildings insurance
 Compare
 Get covered
Read more
Within Opstalverzekering
- Opstalverzekeringthe main page
- Comparing buildings insurance (opstalverzekering) on more than a test score
- Beste opstalverzekering
- Wat beinvloedt de kosten van een eigendomsverzekering ontdek het hier
- Klaverblad opstalverzekering
- De opstalverzekering voor rieten daken bij finass verzekert
- De verschillende categorieen en types opstalverzekeringen van finass verzekert
Similar pages
- What determines the cost of your buildings insurance (opstalverzekering)?
- Comparing buildings insurance (opstalverzekering) on more than a test score
- How high should your buildings insurance (opstalverzekering) be?
- Klaverblad's buildings insurance (opstalverzekering)
- Types of buildings insurance and the properties they are intended for
- What is the best buildings insurance (opstalverzekering) for your home?
- What does buildings insurance (opstalverzekering) cost?
Why arrange it through Finass Verzekert?
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
Independent
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
One fixed adviser
You call or email someone who knows your file. No menu options, no changing call centres.
Switching without hassle
We cancel your old policy and align the start date, so you are never a day without cover.
Help with claims
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
Frequently asked questions
This is what people ask us most.
What determines my premium?
The rebuild value, construction type, year of construction, use and location.
Why is a thatched roof more expensive?
Thatch catches fire from outside and is very hard to put out.
Does a higher excess help?
Something, but with buildings insurance the benefit is more limited than with a car.
Do I have to report a practice at home?
Yes; that is a different risk class.
Can I save by declaring less?
No; that is incorrect information and costs you the cover when you claim.
Does the location count?
Yes; in areas prone to flooding a loading may apply.