

Basic cover
- Fire & lightning strike
- Storm & precipitation
- Explosion & induction
- Smoke & soot damage
The exclusive buildings version from Assicuro works with a valuation agreed in advance and is intended for homes that a standard rebuild value calculator cannot capture.
This page in another language: Nederlands
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
The word exclusive here refers not to service but to the method of valuation. With ordinary buildings insurance (opstalverzekering) you complete a rebuild value calculator and the insurer works from that. With this form, an expert visits the property, describes it and records the rebuild value in a valuation report. That report becomes part of the policy. As long as it is valid, the value is fixed and discussion about underinsurance after a claim no longer arises.
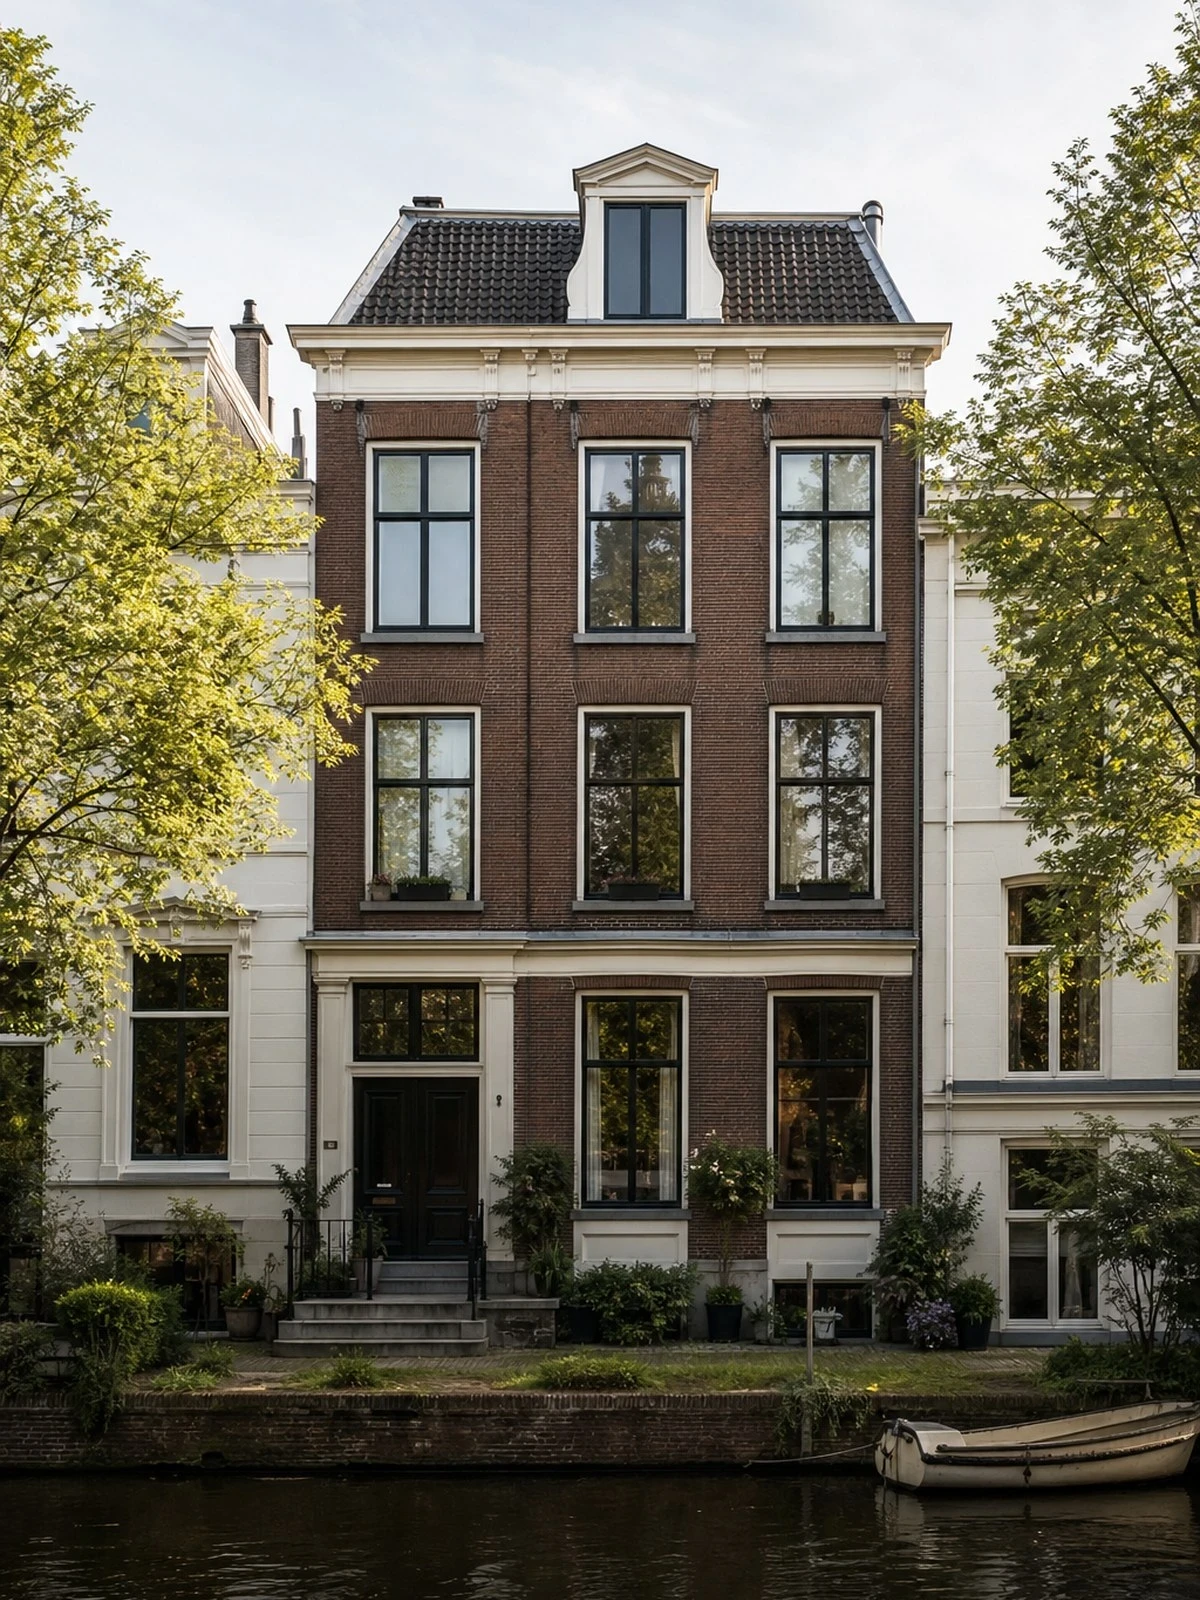
That method is intended for properties where an average per cubic metre says nothing: a listed building, a home with a thatched roof, natural stone, stained glass, craft plasterwork, or a villa with an unusual layout. We also use this version for properties with many outbuildings, a coach house or an orangery. For comparison, see our page on buildings insurance for a villa.
The legal basis is Article 7:960 of the Dutch Civil Code: insurance may not be a source of profit, but the parties may fix the value in advance in a binding way. A valuation by a recognised expert binds the insurer, provided the report meets the requirements the policy sets for it and the period of validity has not expired. It is precisely on those two conditions that things go wrong.
We compare your buildings insurance across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
 Buildings insurance
 Compare
 Get covered
The structure of the cover in three parts, with an overview per situation below.
The basic cover insures the essentials. We show what Assicuro and other insurers offer within it.
As well as fire and storm, also burglary, theft and water damage to your home.
The most complete cover. We compare the extended versions from Assicuro with the market.
What is covered
| Situation | Standard | With extension |
|---|---|---|
| Fire, smoke and lightning strike | Yes | Yes |
| Storm from force 7 upwards | Yes | Yes |
| Water damage from a burst pipe | Yes | Yes |
| Glass breakage | Provided it is declared | Yes |
| Groundwater coming through the floor | No | No |
| Wear and deferred maintenance | No | No |
What we do
| What we do | At Finass | Direct with Assicuro |
|---|---|---|
| Comparison across several insurers | Yes | No |
| Advice based on your own situation | Yes | Sometimes |
| One point of contact for claims | Yes | Sometimes |
| Cancellation with your current insurer arranged | Yes | No |
| We determine whether Assicuro is the best choice | Yes | No |
| Advice fees for you as a customer | No | No |
This overview concerns our service, not the cover. What is actually covered is set out in the policy conditions and on the insurer's insurance card (verzekeringskaart); you receive both before you take out cover.
Insurers weigh these details differently. That is where your saving is.
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
You call or email someone who knows your file. No menu options, no changing call centres.
We cancel your old policy and align the start date, so you are never a day without cover.
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
Customers rate our service on four aspects: personal service, service delivery, availability and the outcome. The reviews are collected and published by NH1816 and come from customers who have actually taken out a policy with Finass Advies B.V. or reported a claim.
Four points that make the difference between a policy that pays out and one that does not.
A valid valuation report takes the discussion about the rebuild value out of claims handling: the insurer works with the recorded amount. That effect is time-limited, however. Policies attach a period of validity to the valuation; once it expires, you fall back on the ordinary way of determining value and underinsurance can still arise. Put the end date in your diary and have the report renewed in good time, certainly after an extension or a major refurbishment.
For a listed building or a property with craft work, restoration means it must be done in the old style again: hand-formed bricks, made-to-measure mouldings, pointing in the right mix. Add to that a permit procedure and sometimes compulsory supervision by the local authority. Check whether the policy promises rebuilding in the original style, or only pays what an ordinary builder would charge for the same volume.
For properties with a thatched roof or an open fire, insurers often include warranty clauses: approved lightning protection, a minimum distance between the chimney and the thatch, periodic inspection of the flue, or spark arresters. These are not recommendations. If such a condition is not met and fire results, there is no cover. We set out those clauses in advance, so you know what you have to demonstrate each year.
Outside cover: damage from an inherent defect or a construction fault in the property itself, gradual influences such as wet rot, dry rot and rising damp, and damage caused by vermin or woodworm in joists. Intent and recklessness are also excluded under Article 7:952 of the Dutch Civil Code. A valuation does not widen the cover. It only fixes the value used to settle a covered claim.
This is what people ask us most.
A valuation by a recognised expert binds both parties to the recorded value. That follows from Article 7:960 of the Dutch Civil Code: the value is fixed, so that after a claim a lower rebuild value cannot be used after all. The insurer can escape it only if the report does not meet the policy requirements, if the period of validity has expired, or if incorrect information was provided when it was drawn up.
The policy names a period during which the agreed value is binding. Once that period expires, the insurance continues but the value is assessed afresh at the time of a claim, with the risk of underinsurance. Have the report renewed well before the end date, and always after an extension, a roof replacement or a refurbishment that changes the volume or the finish.
Only if they are described in the valuation report and on the policy. A coach house, a brick garden wall, a gate or a built-in swimming pool are regularly forgotten, after which the owner discovers following a storm that they are not insured. Walk round the whole plot during the valuation and have the expert name each structure separately in the report.
Yes. A refurbishment changes both the value and the risk: building materials are on site, scaffolding gives access to the upper floors and there is work involving naked flames. Report the work in advance, so the insurer can confirm cover during the building period and the valuation can be adjusted. Without notification, damage during or after the refurbishment may fall outside cover.
Every situation is different. For these situations we have a separate page.
Request a quote without obligation. We will look at which insurer best matches your activities and your risk.
Prefer to call? 072 - 509 24 56, weekdays 09:00–17:00.
Claim on the road? Emergency line 06 - 55 20 40 72.
Finass Verzekert is a trading name of Finass Advies B.V. We advise on and arrange non-life insurance on the basis of an objective analysis of several insurers, and receive commission for this from the insurer, which is included in the premium. You pay no separate advice fee. Before you take out cover, we establish your wishes and needs.
You will find our licence, KvK and Kifid details and our complaints procedure at the foot of every page.
This page was compiled by Finass Verzekert (LinkedIn). Last updated on .
The information on this page is general in nature and is not personal advice.
Maandag- Vrijdag: 09:00- 17:00
We use cookies and similar technologies to improve your experience on our website.