

Vehicle
- Collision and theft
- Fire, storm and hail
- Often a replacement-value-as-new arrangement
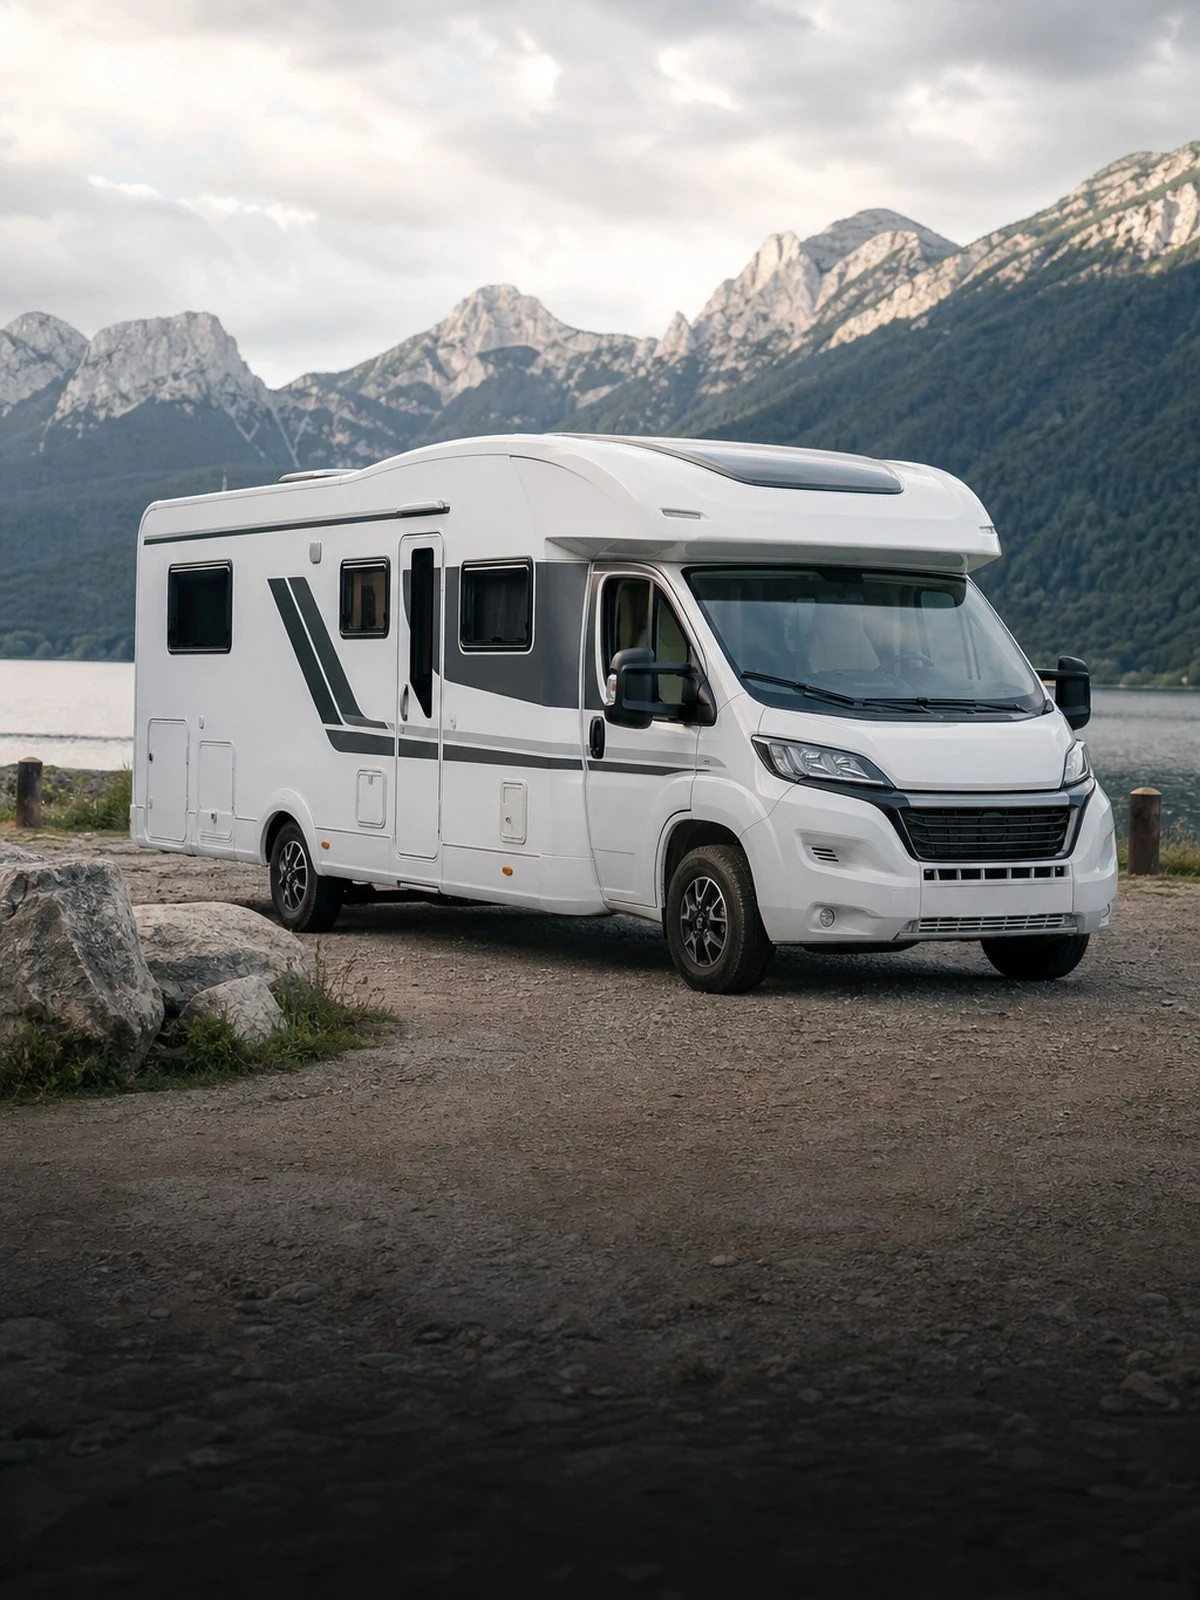
Adria sells van conversions, overcab models and low-profile models under one brand name. The insurer does not work with that brand but with the type, the weight and the body stated on your registration document.
This page in another language: Nederlands
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
The brand name tells the insurer little. What counts is which type you drive: a compact van conversion on a panel van base, an overcab model with a tall body, or a low-profile model with its own living area above the cab. Those three differ in weight, in construction and in the way damage is repaired, and are therefore assessed differently for acceptance and pricing.
Adria sits in the mid-market. A purchase price or replacement-value-as-new arrangement runs out after a time, after which market value applies, while repairing a damaged body remains labour-intensive. That combination means damage is written off as an economic total loss sooner than the owner expects. Wear, rust and deferred maintenance also fall outside every own-damage cover.
If the declared type does not match the registration document, that is not an administrative detail. Article 7:928 of the Dutch Civil Code requires you to give correct information on the application; under Article 7:930 DCC the insurer may reduce or refuse the payout where it would have set different terms had the information been correct. See also the general motorhome insurance.
We compare your motorhome insurance across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
 Motorhome insurance
 Compare
 Get covered
The structure of the cover in three parts, with an overview per situation below.
Third-party liability is compulsory. Also, third-party, fire and theft or comprehensive cover.
Everything you take with you and fit to it.
Breakdown and repatriation of the motorhome and its occupants.
What is covered
| Situation | Third-party liability | Third-party, fire and theft | Comprehensive |
|---|---|---|---|
| Collision with another vehicle | Yes | Yes | Yes |
| Theft of the motorhome | No | Yes | Yes |
| Hail damage during storage | No | Yes | Yes |
| Damage you cause yourself on the campsite | No | No | Yes |
| Contents and accessories | No | Sometimes | Sometimes |
| Frost damage from not draining down | No | No | No |
This overview is general in nature and is not personal advice. What is actually covered, including exclusions, limits and the excess, is set out in the policy conditions and the insurance card (verzekeringskaart) of the insurer; you receive both before you take out cover. Taking out cover without advice? Then read what execution only means for you.
Insurers weigh these details differently. That is where your saving is.
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
You call or email someone who knows your file. No menu options, no changing call centres.
We cancel your old policy and align the start date, so you are never a day without cover.
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
Customers rate our service on four aspects: personal service, service delivery, availability and the outcome. The reviews are collected and published by NH1816 and come from customers who have actually taken out a policy with Finass Advies B.V. or reported a claim.
Four points that make the difference between a policy that pays out and one that does not.
Adria supplies van conversions on a panel van base, overcab models and low-profile models. For the insurer those are three different risks, because the height, the weight and the body construction differ. So enter what is stated in part I of the registration document, not what you read in the brochure or the advertisement. If the declaration differs from reality, the insurer can rely on Article 7:930 DCC when a claim is made and reduce or refuse the payout entirely.
Several models sit close to the maximum permitted weight of 3,500 kilograms and sometimes exceed it when fully loaded. That affects your entitlement to drive and your cover at the same time. Driving without the required licence is excluded from own-damage cover on almost every policy, and where there is injury or damage to third parties the liability insurer will pay the victim but can recover that from you. Weigh the camper van loaded and declare the actual weight.
A purchase price or replacement-value-as-new arrangement runs out after a number of years. After that the insurer pays the market value. On a mid-market camper van that value falls faster than the cost of repairing the body, because panels, furniture modules and sandwich panels remain labour-intensive to replace. The result is that damage which is technically repairable is nevertheless settled as a total loss. Ask at each renewal how long the arrangement still has to run.
Seams, roof penetrations and the joint around the overcab are the places where water gets in. The policy covers sudden and unforeseen damage from outside; damp entering slowly, rotted panels and mould growth fall outside that and count as deferred maintenance. Have the watertightness checked periodically and keep the reports. If a leak demonstrably arises in one go, for example through hail impact or a collision, the assessment is different.
Add up what is really in it: crockery, pans, bedding, clothing, bicycles on the carrier, a TV and the awning. In a well-equipped motorhome that adds up to several thousand euros. You insure that separately; the vehicle's own-damage cover does nothing with it.
Draining the water or keeping a minimum temperature is a condition on almost every policy. Burst pipes and a boiler ruined by frost are not sudden damage from outside but the result of an omission, and are not paid for.
This is what people ask us most.
Yes. The insurer assesses type, weight and body construction, not the brand name. A van conversion on a panel van base, an overcab model and a low-profile model therefore get a different rate and sometimes different acceptance terms. Declare the type as it appears in part I of the registration document; a declaration that differs leads to discussion about the size of the payout when you claim.
Then you need a category C1 licence, and the vehicle also changes category for the insurer. Driving without the required entitlement is excluded from own-damage cover, and where there is damage to third parties the liability insurer will pay the victim but can recover that amount from you. Weigh the camper van fully loaded and declare the actual weight.
After that the insurer works with market value. For a mid-market camper van that means substantial damage to the body is settled as a total loss sooner than repaired, because the repair remains labour-intensive while the value falls. Ask at renewal how long the arrangement still has to run and whether a valuation makes sense in your situation.
Only where it is sudden damage from outside, for example after hail impact or a collision. Water that slowly enters via seams and roof penetrations, resulting in rotted panels or mould, counts as deferred maintenance and is excluded. Have the watertightness checked periodically and keep the reports of that check.
Every situation is different. For these situations we have a separate page.
Request a quote without obligation. We will look at which insurer best matches your activities and your risk.
Prefer to call? 072 - 509 24 56, weekdays 09:00–17:00.
Claim on the road? Emergency line 06 - 55 20 40 72.
Finass Verzekert is a trading name of Finass Advies B.V. We advise on and arrange non-life insurance on the basis of an objective analysis of several insurers, and receive commission for this from the insurer, which is included in the premium. You pay no separate advice fee. Before you take out cover, we establish your wishes and needs.
You will find our licence, KvK and Kifid details and our complaints procedure at the foot of every page.
This page was compiled by Finass Verzekert (LinkedIn). Last updated on .
The information on this page is general in nature and is not personal advice.
Maandag- Vrijdag: 09:00- 17:00
We use cookies and similar technologies to improve your experience on our website.