

Third-party liability for plant and machinery
- Compulsory on public roads
- Also during work
- Cables and pipes separately
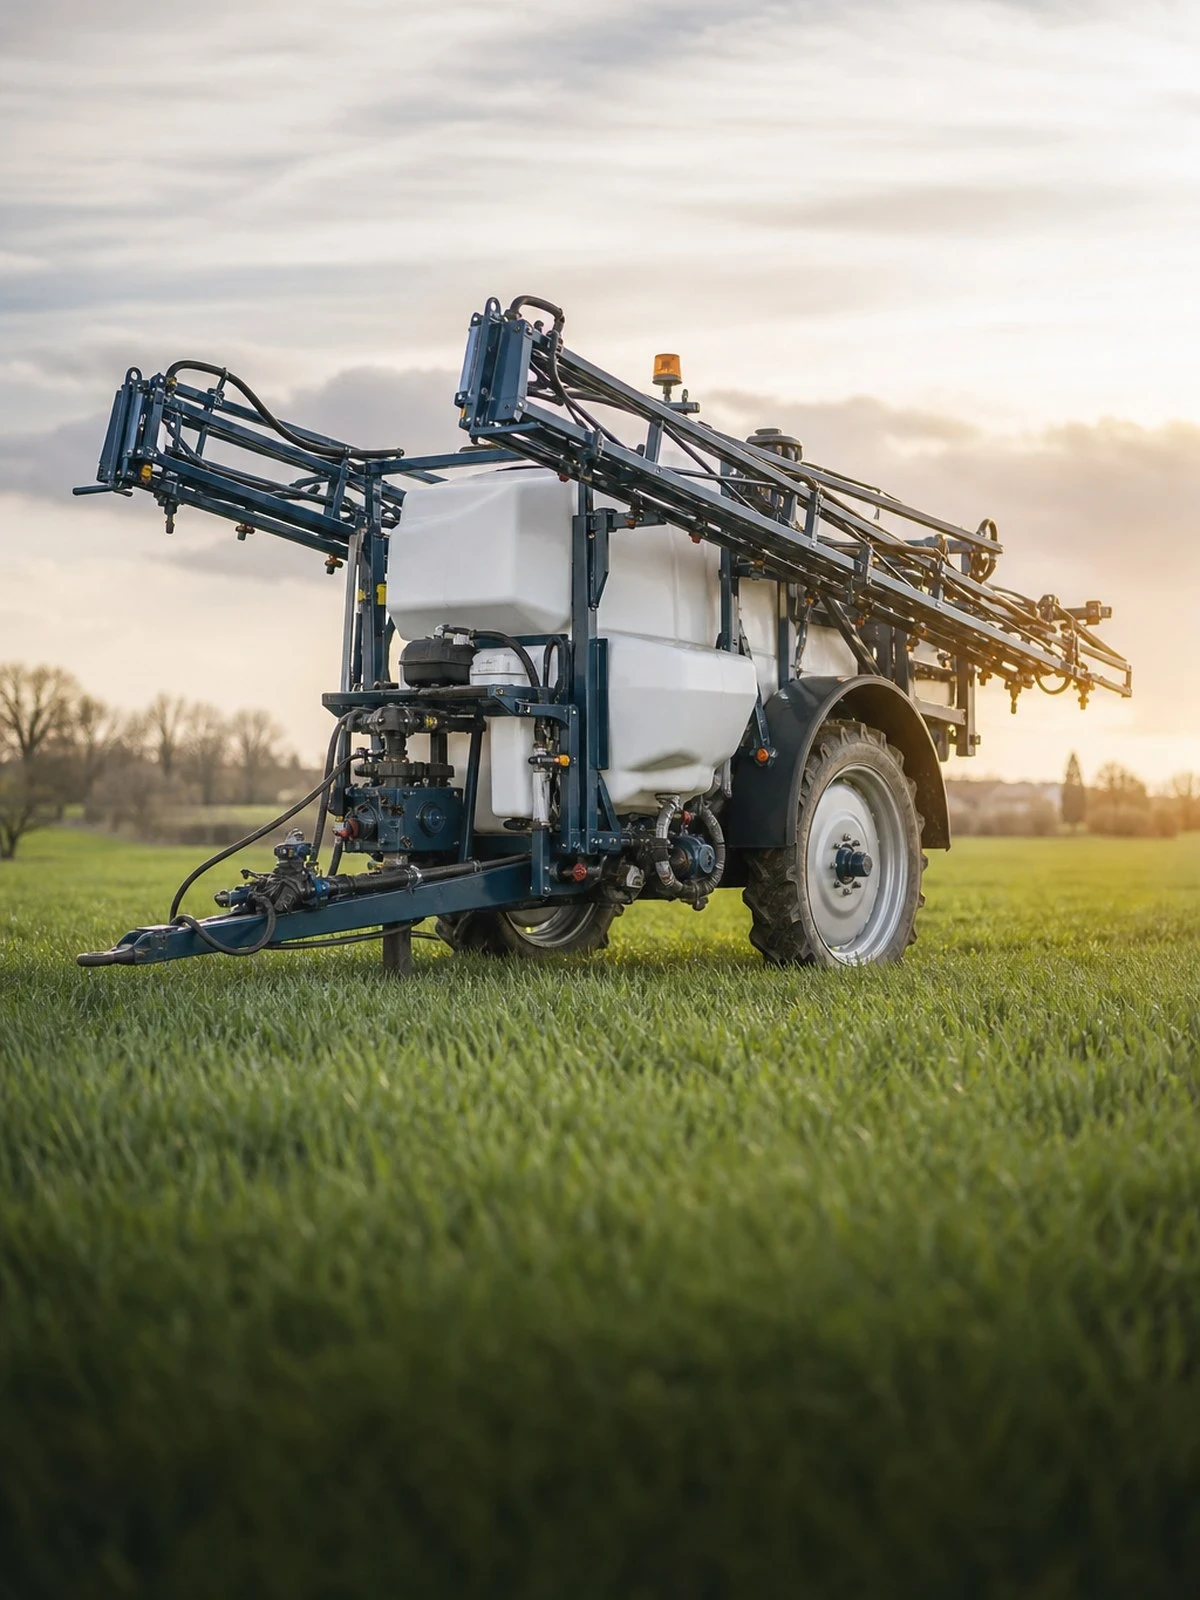
With a sprayer the most expensive loss rarely occurs to the machine itself, but on the plot or in the ditch next to it.
This page in another language: Nederlands
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
A field sprayer applies a substance intended to kill or inhibit something. If that substance drifts across to an adjoining plot, an ornamental garden or an organic crop, the result is property damage to someone else and the insurer assesses your liability under Article 6:162 of the Dutch Civil Code. That makes your spraying records, the wind force at the time and the nozzle technology used the actual file for the claim.
There is also a second track that is separate from drift: contamination of soil and surface water. That happens more often during filling, rinsing and washing down in the yard than during spraying itself. Clean-up costs do not fall under ordinary liability cover; environmental damage cover is needed for that, and gradual contamination is usually excluded there too.
The machine itself is the third track. The spray boom is the most vulnerable part, and the tank, pump, nozzles and filters are in permanent contact with aggressive substances. For how the cover is built up, see the plant and machinery insurance.
We compare your plant and machinery insurance across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
 Plant and machinery insurance
 Compare
 Get covered
The structure of the cover in three parts, with an overview per situation below.
Damage you cause to others with the machine.
Damage to the machine, the body and the attachments.
What you add separately.
What is covered
| Situation | Third-party liability for plant and machinery | Own-damage cover |
|---|---|---|
| Damage to a building or a parked car next to the site | Yes | No |
| Theft of the machine from the building site | No | Provided that |
| Fire and storm damage | No | Yes |
| Inherent defect in the hydraulics or the engine | No | Provided that |
| Damage to the item you are working on with the machine | No | No |
| Wear and deferred maintenance | No | No |
Mobile plant is a motor vehicle within the meaning of the WAM and needs third-party liability insurance on public roads; non-mobile plant does not. Damage to cables and pipes is generally only covered if the excavation notification has been made and the trial trenches have been dug. The item you work on with the machine falls under the care, custody and control exclusion.
This overview is general in nature and is not personal advice. What is actually covered, including exclusions, limits and the excess, is set out in the policy conditions and the insurance card (verzekeringskaart) of the insurer; you receive both before you take out cover. Taking out cover without advice? Then read what execution only means for you.
Insurers weigh these details differently. That is where your saving is.
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
You call or email someone who knows your file. No menu options, no changing call centres.
We cancel your old policy and align the start date, so you are never a day without cover.
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
Customers rate our service on four aspects: personal service, service delivery, availability and the outcome. The reviews are collected and published by NH1816 and come from customers who have actually taken out a policy with Finass Advies B.V. or reported a claim.
Four points that make the difference between a policy that pays out and one that does not.
Product drifting across makes a neighbouring crop unsaleable or costs an organic plot its certification. That is property damage to a third party and runs through your liability cover. Your defence consists of records for each application: product, dose, time, wind direction and wind force, plus the drift-reducing nozzles used and the crop-free zone observed. If you sprayed contrary to the label or outside the statutory rules, that is a ground for exclusion and that defence falls away.
If you apply the wrong product or the wrong dose on your client's plot, that is an error in carrying out your assignment. The cost of re-treatment and the loss of yield are pure financial loss and fall outside the property damage cover of a liability insurance. That calls for separate cover for errors in performance. For contractors this is the loss that most often turns out to be uninsured.
Spillage at the mixing point, discharging residual liquid and washing down on a floor that is not liquid-tight put a strain on soil and surface water. Clean-up costs for your own land and for someone else's are not included in ordinary liability cover; environmental damage insurance is needed for that. There too, contamination that has arisen gradually and discharges contrary to a permit condition remain outside the cover. A liquid-tight filling and washing area is the first question.
A boom extended over many metres strikes a post, a fence or a road sign when turning on the headland. That is sudden damage and generally covered. Attack on the tank, pipework and pump diaphragms by chemicals and limescale is not: that falls under gradual action. Nozzles, filters and hoses also count as wear parts. A trailed or mounted field sprayer should be declared separately and is not included in the tractor cover.
This is what people ask us most.
Damage to someone else's crop is property damage and runs through your liability cover, provided you worked within the label and the statutory rules. If product also ended up in the ditch or the soil, that is contamination and falls under environmental damage cover, not under ordinary liability. Your spraying records are the evidence in both cases.
This is not property damage caused by an accident but an error in carrying out your assignment. Re-spraying, remedial measures and lost yield are pure financial loss and fall outside standard property damage cover. Contractors need separate cover for errors in performance for this; have it checked in advance whether your policy provides it.
No. A mounted or trailed field sprayer is an independent implement with its own value and should be listed separately on the policy. If it is not declared, there is no cover for the sprayer itself in the event of fire, theft or own damage. Give the boom width and the year of construction as well. Those help determine the valuation.
No. Corrosion, chemical attack and limescale arise gradually and therefore fall under the exclusion for gradual action. Nozzles, filters, hoses and pump diaphragms also count as wear parts. Only sudden damage qualifies, such as a boom striking an obstacle or frost damage to a tank that has not been drained where the conditions allow it.
Every situation is different. For these situations we have a separate page.
Request a quote without obligation. We will look at which insurer best matches your activities and your risk.
Prefer to call? 072 - 509 24 56, weekdays 09:00–17:00.
Claim on the road? Emergency line 06 - 55 20 40 72.
Finass Verzekert is a trading name of Finass Advies B.V. We advise on and arrange non-life insurance on the basis of an objective analysis of several insurers, and receive commission for this from the insurer, which is included in the premium. You pay no separate advice fee. Before you take out cover, we establish your wishes and needs.
You will find our licence, KvK and Kifid details and our complaints procedure at the foot of every page.
This page was compiled by Finass Verzekert (LinkedIn). Last updated on .
The information on this page is general in nature and is not personal advice.
Maandag- Vrijdag: 09:00- 17:00
We use cookies and similar technologies to improve your experience on our website.