

Liability insurance for an installation company
An installation company delivers work that can still cause trouble years after handover, often in buildings where people other than the client live or work. That calls for different arrangements from a one-off job.
- Several insurers compared objectively
- 9.5 customer rating for a new policy
- AFM licence 12016589
- Personal 072 - 509 24 56, weekdays 9–17
This page in another language: Nederlands
The calculator and the quote form below are in Dutch. Prefer to do this in English? Email info@finassverzekert.nl or call 072 - 509 24 56 and we will take it from there.
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
- We compare the offerings of several insurers
- An adviser checks whether the cover suits your activities
- We arrange the switch, including cancellation
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
- Independent advice
- Several insurers
- Switching arranged
- Help with claims
In brief
An installation company brings disciplines together: water, gas, heating, cooling, air handling and increasingly electrical and control engineering. A fault in one of those systems affects third parties who are not party to your contract: tenants, visitors or neighbours. Injury and property damage from that belong on the public and employers' liability insurance. For the project risk during construction itself there is also cover for installation and assembly work.
The distinguishing point for a company is the timeline. Guarantee periods in commercial construction run for years, and a claim about an air handling system or a leaking pipe in a riser often comes long after handover. On a policy working on a claims-made basis basis, the date of the claim counts and not the date of the work. Arrange retroactive cover when you switch and a run-off period when you cancel, otherwise you are uninsured for your own past.
The second point is the chain. You contract out demolition, chasing, insulation or electrical work and remain liable to the client for the whole. Check whether subcontractors are insured themselves and whether your policy covers work by third parties. On the staff side, Article 7:658 of the Dutch Civil Codeapplies, with subsection 4 for hired-in engineers. For injury to staff travelling between projects there is the separate cover under WEGAS and WEGAM.
This page deals with one situation. The full overview is on Compare public and employers' liability insurance (AVB).
Independent, personal, sorted quickly
We compare your business liability insurance (AVB) across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
 Business liability insurance (AVB)
 Compare
 Get covered
Why arrange it through Finass Verzekert?
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
Independent
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
One fixed adviser
You call or email someone who knows your file. No menu options, no changing call centres.
Switching without hassle
We cancel your old policy and align the start date, so you are never a day without cover.
Help with claims
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
What to look out for
Four points that weigh more heavily at an installation company than for a single engineer.
Design alongside execution
If you take on engineering, capacity calculations or a performance guarantee, you are selling more than assembly. A system that does not achieve the agreed temperature or air quality costs money without anything being broken: pure financial loss, excluded on the AVB and belonging on professional indemnity insurance.
Contract conditions and penalties
If you work under a contractor's or investor's purchasing conditions, they contain penalty clauses, reductions for late completion and indemnities. Liability you above the statutory accept is not covered, nor are penalties. Have contracts assessed. For the dispute that follows, legal expenses insurance can offer a way through.
Appliances supplied and recalls
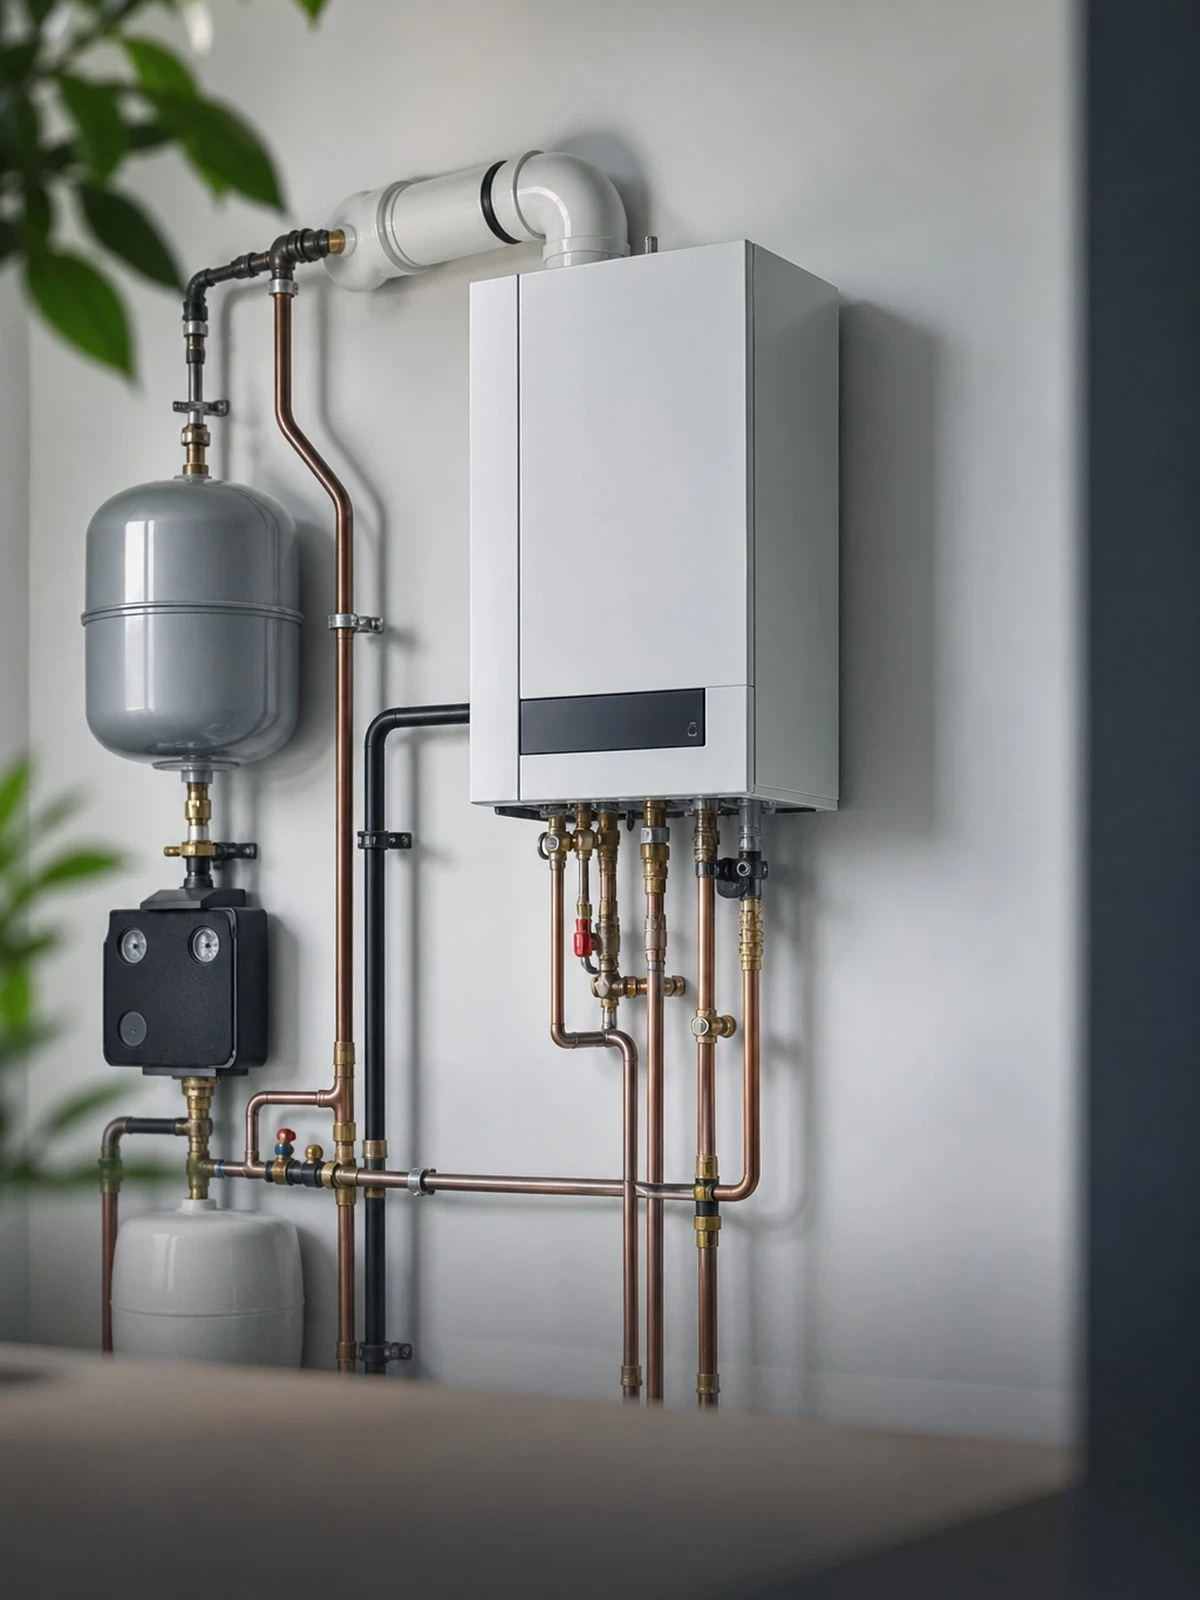
If you supply boilers, heat pumps or air handling units, product liability applies to them. Damage such an appliance causes can be covered; the the costs of retrieving, replacing and refitting almost never are. There is separate recall cover for that.
Work in occupied and operating buildings
In a care institution, hotel or data centre the consequential loss of an outage is greater than the job itself. Record which systems may be switched off and when. Environmental damage from leaking refrigerant or spilt oil is moreover covered only if the pollution is sudden and unforeseen; there is environmental damage insurance.
What does your premium depend on?
- Turnover and payroll: the yardstick for size and employers' liability
- Mix of disciplines: gas, cooling and electrical work weigh more heavily than sanitary work
- New build, refurbishment or maintenance: work in operating buildings increases consequential loss
- Work put out to others: the extent of your subcontracting counts
- Run-off and retroactive periods: important where guarantee periods are long
- Sum insured and excess: per claim and per insurance year
Insurers weigh these details differently. That is where your saving is.
What is covered
| Situation | AVB | BAV |
|---|---|---|
| An engineer from your subcontractor leaves a coupling loose and the shop below floods | Yes | No |
| One of your own engineers falls off a scaffold on a commercial project | Yes | No |
| Refrigerant suddenly leaks from a cooling installation in a supermarket | Provided that | No |
| The air handling in a care home never achieves the agreed temperature | No | Yes |
| During commissioning a data centre goes down for an hour and the client claims its loss | No | Provided that |
| The client charges the contractual penalty for late completion | No | No |
Work by third parties counts as your work when a claim comes in, so check what your policy says about it.
Frequently asked questions
This is what people ask us most.
An installation we handed over three years ago is leaking. Are we still covered?
With claims-made cover, what matters is whether your policy is in force at the moment the claim comes in. If you have switched since, retroactive cover is needed for work from the earlier period. The damage to the building and to users' belongings can fall within cover; replacing your own pipework does not.
A subcontractor causes damage on our project. Who pays?
Towards the client you remain liable for the whole. Your insurer will then seek recovery from the subcontractor or his insurer. If he has no cover, the loss in fact stays with you. Check the policy of every party you engage before the work starts, therefore, and whether your own conditions include work by third parties.
An engineer is injured while installing a unit. What applies?
Article 7:658 of the Dutch Civil Code places on you the burden of proving that you complied with your duty of care: lifting aids, instruction, supervision and an up-to-date risk assessment. Subsection 4 brings agency workers and hired-in self-employed people within it. Employers' liability must be included as a separate section, otherwise there is no cover for this type of claim.
Are reductions for late completion insured?
No. Penalties, reductions and liability accepted by contract going beyond what the law imposes are excluded on almost every liability policy. Administrative fines fall outside it as well, because they are a punishment and not compensation. What remains insurable is the damage your mistake causes to people or property.
Every situation is different. For these situations we have a separate page.
- Compare public and employers' liability insurance (AVB)The main page
- Liability insurance for an electrical contractorInstallation fires, inspection, outages
- Liability insurance for a flange assembly companyTurnarounds, records, contract requirements
- Liability insurance for a pest control firmFumigation, confined spaces, contract conditions
- Liability insurance for a plumbing companyGas installations, key holding, service vans
- Liability insurance for a window cleaning firmFacade installations, teams, maintenance contracts
- Liability insurance for an air conditioning firmRefrigerant, condensate drainage, certification
- Public and employers' liability insurance (AVB) through a.s.r.Staff, hired-in workers, occupational illness
- Liability insurance for a solar panel firmRecourse after a fire, supplier, working at height