

Buildings
- Fire, storm and water
- Burglary damage
- Outbuildings and swimming pool
For a Dutch holiday home, the designated use in the zoning plan and the operating agreement with the park often matter more for cover than the building itself.
This page in another language: Nederlands · Deutsch
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
A holiday home in the Netherlands differs fundamentally on one point from a second home abroad: here the use is fixed in law. The zoning plan determines whether the property may be occupied for recreation, and most parks prohibit permanent occupation. If you nevertheless live there permanently, the use differs from what was declared and the insurer can rely on the duty of disclosure when you claim, Articles 7:928 and 7:930 of the Dutch Civil Code.
The second point is the park itself. If the property stands on a site with an operator, the infrastructure, the roads, the pipework and sometimes the structure itself are already insured somewhere. Read the operating or park agreement before you take out a buildings policy yourself: double insurance is more common here than a gap.
Then there are the two classic Dutch risks: water and frost. An outer-dyke location and flooding from the regional water system are handled very differently from one insurer to another, and an unheated chalet in January is a frost damage claim in the making. See also the holiday home and chalet insurance.
We compare your holiday home insurance across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
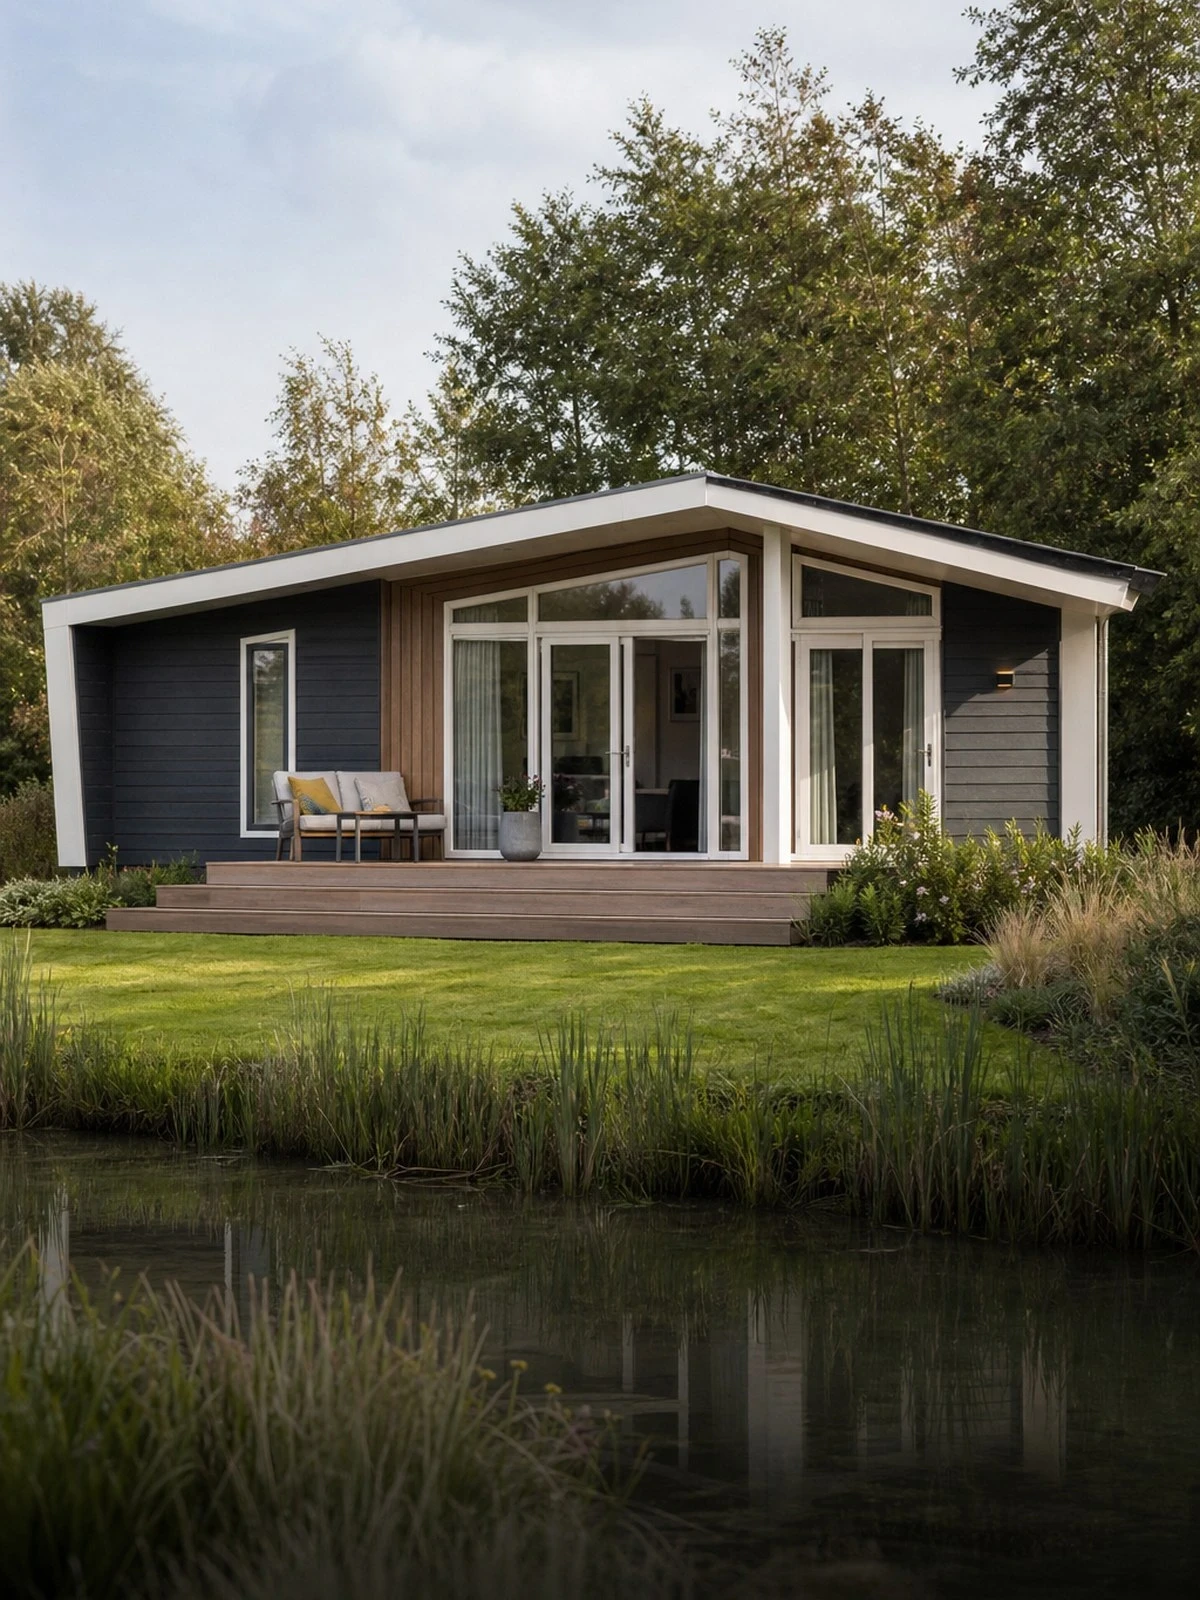 Holiday home insurance
 Compare
 Get covered
The structure of the cover in three parts, with an overview per situation below.
The home at rebuild value, based on local building costs.
Furniture and equipment you leave there permanently.
Your liability for the building and towards tenants.
What is covered
| Situation | Covered |
|---|---|
| Fire or storm damage to the home | Yes |
| Water damage while the property is occupied | Yes |
| Water damage during a long period of vacancy | No |
| Damage caused by a tenant | Sometimes |
| Theft of your home contents while the property is let | Sometimes |
| Deferred maintenance and frost damage | No |
This overview is general in nature and is not personal advice. What is actually covered, including exclusions, limits and the excess, is set out in the policy conditions and the insurance card (verzekeringskaart) of the insurer; you receive both before you take out cover. Taking out cover without advice? Then read what execution only means for you.
Insurers weigh these details differently. That is where your saving is.
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
You call or email someone who knows your file. No menu options, no changing call centres.
We cancel your old policy and align the start date, so you are never a day without cover.
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
Customers rate our service on four aspects: personal service, service delivery, availability and the outcome. The reviews are collected and published by NH1816 and come from customers who have actually taken out a policy with Finass Advies B.V. or reported a claim.
Four points that make the difference between a policy that pays out and one that does not.
A holiday home is intended for recreational stays. If you go and live there permanently, the use differs from what the policy states and the municipality may also take enforcement action. Insurers ask about this expressly. If the situation changes, for example through letting to migrant workers or because someone registers at the address, report it at once. Otherwise, when you claim, the duty of disclosure under Article 7:928 of the Dutch Civil Code up.
On a park with an operator, roads, drainage, communal facilities and sometimes the structure of the homes run through the operator or the association. Your own policy has to fit around that. Check who bears the foundations, terrace, shed and extension, because that is usually where the gap lies. The park rules on electricity, gas cylinders and wood burners also feed through into what the insurer accepts.
Flooding from the sea or the major rivers after a primary flood defence gives way is not insurable. For that there is the government compensation scheme, which gives no right to full compensation. Flooding from the regional water system is covered by some insurers, with their own limits. If the property lies outside the dykes or on a flood plain, have it recorded in writing which of the two you have.
Most winter losses are frost losses: a burst pipe in an unheated chalet. The policy normally requires draining or a minimum temperature. Also excluded are: deferred maintenance to the roof and roof covering, damage from subsidence of the ground under a timber chalet, and theft during letting where the letting has not been declared. Intent and recklessness fall under Article 7:952 of the Dutch Civil Code.
If you let through a platform, say so. Without notification, damage during the letting period falls outside the cover.
For most destinations you can choose. A Dutch policy means Dutch conditions, Dutch law and claims handling in Dutch: worth a great deal in the event of a large claim in a country whose language you do not speak. A local policy sometimes fits regional natural hazards better.
This is what people ask us most.
That depends on the zoning plan and the park rules, and usually it is not permitted. For insurance purposes what matters most is that the actual use matches what you have declared. If that changes, report it; otherwise the insurer can rely on the duty of disclosure under Articles 7:928 and 7:930 of the Dutch Civil Code when you claim.
Partly. A breach of a primary flood defence along the sea or the major rivers is not insurable. For that there is a government compensation scheme that gives no right to full compensation. Water from the regional system, such as a ditch, canal or pumping station, is covered by some insurers. Have it recorded in writing what applies to your address.
Often the infrastructure, roads, drainage and communal buildings, and on some parks the structure of the homes as well. Ask for the operating agreement and the policy before you take out anything yourself. The gaps are usually in the foundations, terrace, shed and extension, and in your own contents and your liability as owner.
By doing exactly what the policy requires: drain the water pipes and empty the system, or maintain a minimum temperature and be able to prove it. Record who checks the property in winter and how often. Without those measures, a burst pipe in an unheated chalet is an excluded loss, whatever its size.
Every situation is different. For these situations we have a separate page.
Request a quote without obligation. We will look at which insurer best matches your activities and your risk.
Prefer to call? 072 - 509 24 56, weekdays 09:00–17:00.
Claim on the road? Emergency line 06 - 55 20 40 72.
Finass Verzekert is a trading name of Finass Advies B.V. We advise on and arrange non-life insurance on the basis of an objective analysis of several insurers, and receive commission for this from the insurer, which is included in the premium. You pay no separate advice fee. Before you take out cover, we establish your wishes and needs.
You will find our licence, KvK and Kifid details and our complaints procedure at the foot of every page.
This page was compiled by Finass Verzekert (LinkedIn). Last updated on .
The information on this page is general in nature and is not personal advice.
Maandag- Vrijdag: 09:00- 17:00
We use cookies and similar technologies to improve your experience on our website.