

Liability insurance for a bricklaying firm
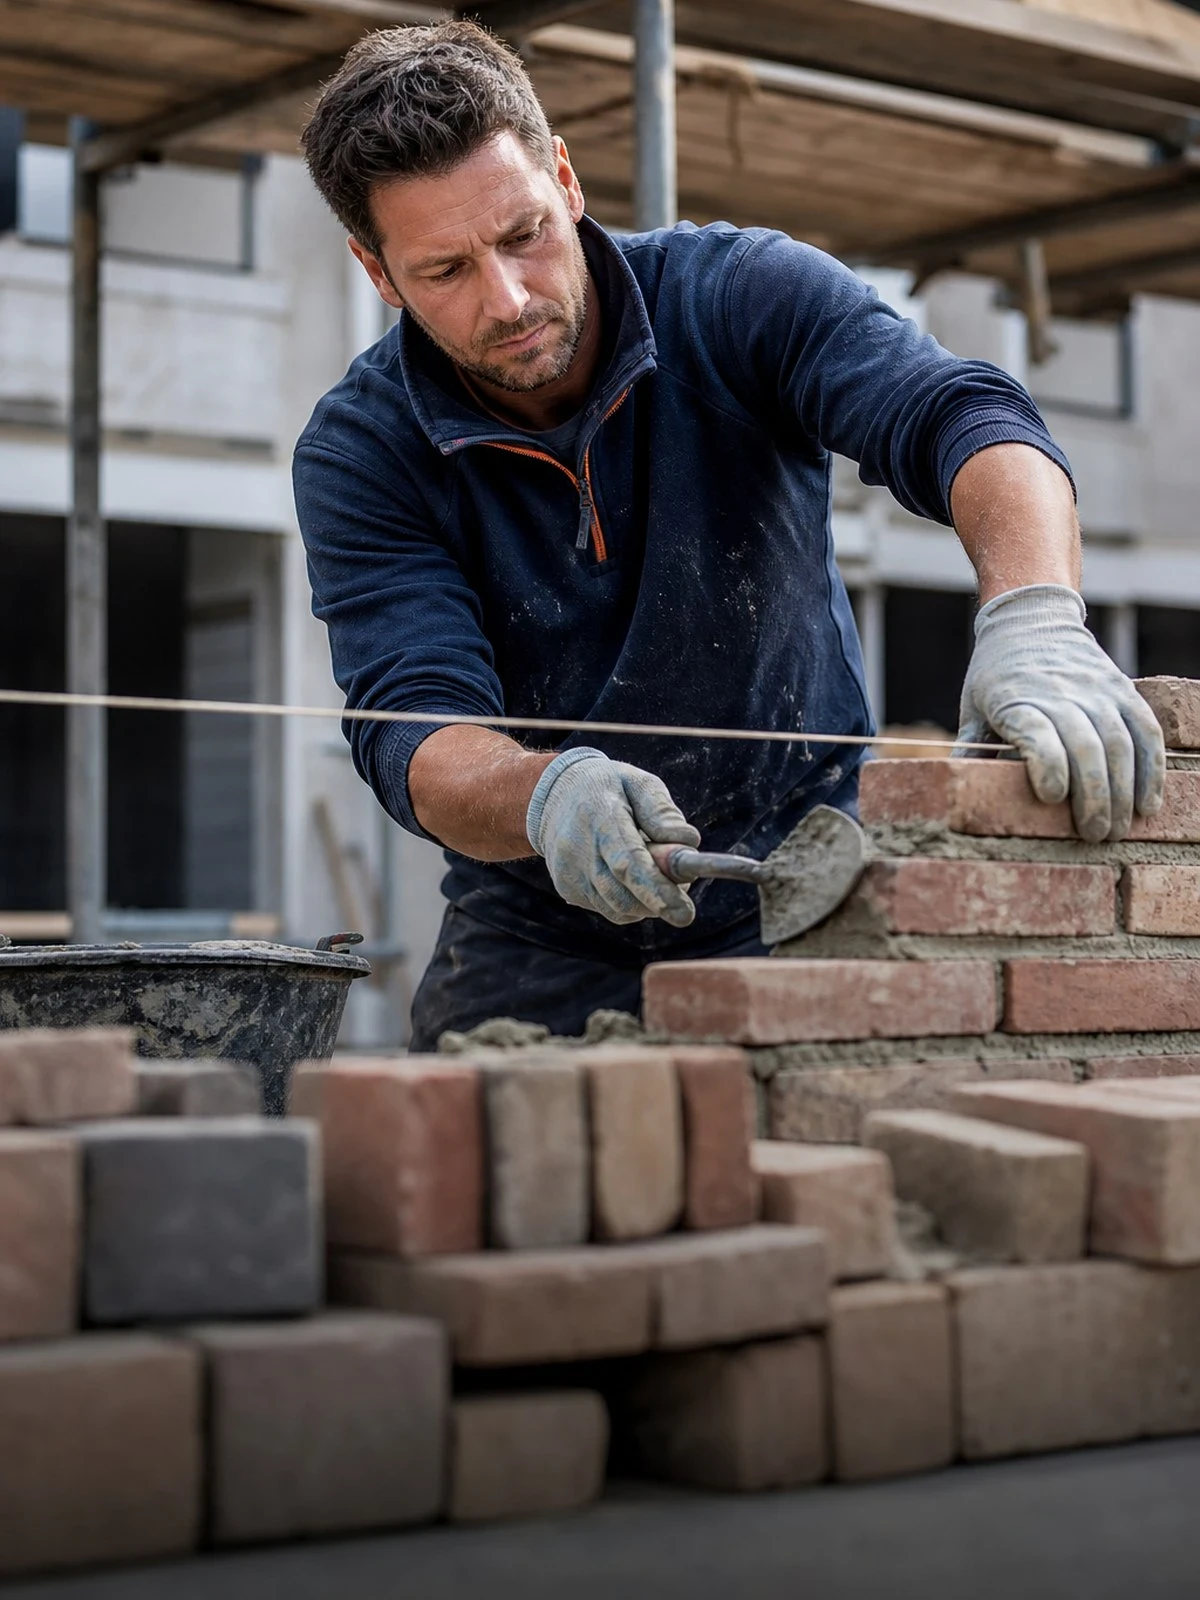
A bricklaying company puts gangs on scaffolds and works on facades that are often already standing. The risk then lies less in the new brick than in the existing building around it.
- Several insurers compared objectively
- 9.5 customer rating for a new policy
- AFM licence 12016589
- Personal 072 - 509 24 56, weekdays 9–17
This page in another language: Nederlands
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
- We compare the offerings of several insurers
- An adviser checks whether the cover suits your activities
- We arrange the switch, including cancellation
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
- Independent advice
- Several insurers
- Switching arranged
- Help with claims
In brief
With a gang on the scaffold, employers' liability is the heaviest section. Falls from height, lifting complaints and eye injuries from grinding dust are the usual claims here. Article 7:658 of the Dutch Civil Code reverses the burden of proof: you must show that guard rails, toe boards, inspection of the scaffolding material, instruction and supervision were in order. Under subsection 4 that applies equally to agency workers and bricklayers hired in, even though their contract lies elsewhere.
The second focal point is damage to existing work. In refurbishment, retrofitted insulation, pointing and restoration work you touch parts that are not yours but that you are working on. Cleaning with acid that damages window frames or natural stone, a joint raked out too deeply, a lintel bearing that is struck: that damage runs into the care, custody and control exclusion and into the provision on work carried out. Ask expressly about cover for property being worked on and about its limit.
Three cost items stay outside. Rebuilding or repointing your own work is performance of the contract. Damage to the works under construction belongs on the project's Construction all risks (CAR) insurance and not on the AVB. And loss due to delay a main contractor puts on you with nothing broken is pure financial loss. Equipment such as scaffolding, mixers and telehandlers has a policy of its own. If that telehandler travels on the public road, Article 2 of the Dutch Motor Insurance Liability Act (WAM) applies and not the AVB.
This page deals with one situation. The full overview is on Compare public and employers' liability insurance (AVB).
Independent, personal, sorted quickly
We compare your business liability insurance (AVB) across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
 Business liability insurance (AVB)
 Compare
 Get covered
Why arrange it through Finass Verzekert?
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
Independent
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
One fixed adviser
You call or email someone who knows your file. No menu options, no changing call centres.
Switching without hassle
We cancel your old policy and align the start date, so you are never a day without cover.
Help with claims
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
What a bricklaying company is assessed on
Four subjects that weigh more heavily at a company with staff than for a self-employed person.
Scaffolding: managed in-house or bought in
If you erect it yourself, you are responsible for the erection and the inspection. If you buy it in, record who releases it for use and who does the weekly check. If it collapses, those records determine whether the loss lies with you or with the scaffolding company, and whether your insurer can seek recovery.
Baseline surveys of adjoining buildings
With work in a terrace of buildings, claims come in about cracks from neighbours that have nothing to do with you. A baseline survey with photographs and a date is the only practical answer. Include the cost of it in the contract price. It is lower than one rejected defence.
Facade cleaning and the use of acid
Cleaning agents damage glass, aluminium and soft natural stone, and rinsing water can damage plants and paving. Insurers see this as a separate risk and sometimes set conditions. If the product runs into the soil or the drain, you enter the territory of environmental damage insurance.
Bricklayers hired in
At peak times you hire in self-employed people or gangs. For your client you remain the party carrying out the work, and your duty of care applies to them as well. Ask for their policy schedule in advance and report the hiring in to your insurer, because the premium basis is often the total payroll including hired-in workers.
What does your premium depend on?
- Payroll and number of bricklayers: the basis for employer's liability
- Share of refurbishment and restoration: existing work brings more causes of loss with it
- Working height and use of scaffolding: decisive for the risk of falls and falling material
- Facade cleaning in the package: chemical cleaning is a separate risk
- Hiring in staff: this counts towards the duty of care and the premium basis
- Sum insured and excess: per claim and per insurance year
Insurers weigh these details differently. That is where your saving is.
What is covered
| Situation | AVB | BAV |
|---|---|---|
| An employed bricklayer suffers an eye injury from grinding dust with no goggles issued | Yes | No |
| A pallet of bricks falls off the telehandler on the site and hits one of the contractor's staff | Yes | No |
| While raking out joints, the lintel bearing of the listed building is damaged | Provided that | No |
| Your telehandler knocks over a lamp post on the public road | No | No |
| Two years after handover, efflorescence appears across the whole facade and the pointing has to be done again | No | No |
| Your work planner miscalculates the number of wall ties and the facade has to be rebuilt | No | Yes |
Work on existing facades calls for an express arrangement about property being worked on.
Frequently asked questions
This is what people ask us most.
Is damage to the existing facade we are working on covered?
Usually not without an additional arrangement. The facade is property you have in your care and are working on, so the care, custody and control exclusion applies. Separate cover for property being worked on can solve that, with its own limit and excess. With restoration work on a listed building that limit is often the heart of the conversation.
What if an employee falls off the scaffold?
That is a claim under the employers' liability section, provided it is included. The insurer assesses whether you complied with the duty of care under Article 7:658 of the Dutch Civil Code: inspected equipment, edge protection, instruction and supervision. Keep inspection reports and toolbox talk records; with injury claims that is the material on which the defence stands or falls.
Are fines from the labour inspectorate covered?
No. Administrative fines and penalty payments are excluded because they are a sanction and not compensation. They also often come together with an injury claim, and then the penalty report is useful evidence for the other side. Put right the shortcoming identified in a demonstrable way, therefore, and document it.
Do we have to report changes in the type of work?
Yes. If you move from housebuilding to restoration, high-rise or facade cleaning, the risk changes. Article 7:928 of the Dutch Civil Code requires an accurate declaration on your application and Article 7:930 DCC governs what happens if it is not accurate: payment can be reduced or refused. Report strong growth in turnover as well.
Every situation is different. For these situations we have a separate page.
- Compare public and employers' liability insurance (AVB)The main page
- Liability insurance for a plumbing companyGas installations, key holding, service vans
- Liability insurance for a painting and decorating firmOccupied buildings, key management, risk of falls
- Liability insurance for a window cleaning firmFacade installations, teams, maintenance contracts
- Liability insurance for a landscaping companyMachinery injuries, maintenance contracts, public green space
- Liability insurance for a plastering companyDust exposure, spray work, external facades
- Liability insurance for a self-employed bricklayerFalling material, mortar splashes, your own wall
- Liability insurance for a contracting firmChain liability, duty of care, environment
- Liability insurance for a chimney sweeping companyFire, roofs, asbestos