

Liability insurance for a self-employed bricklayer
Bricklaying produces two kinds of damage: something that falls down and something that gets dirty or goes out of true. The first is usually covered, the second almost never.
- Several insurers compared objectively
- 9.5 customer rating for a new policy
- AFM licence 12016589
- Personal 072 - 509 24 56, weekdays 9–17
This page in another language: Nederlands
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
- We compare the offerings of several insurers
- An adviser checks whether the cover suits your activities
- We arrange the switch, including cancellation
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
- Independent advice
- Several insurers
- Switching arranged
- Help with claims
In brief
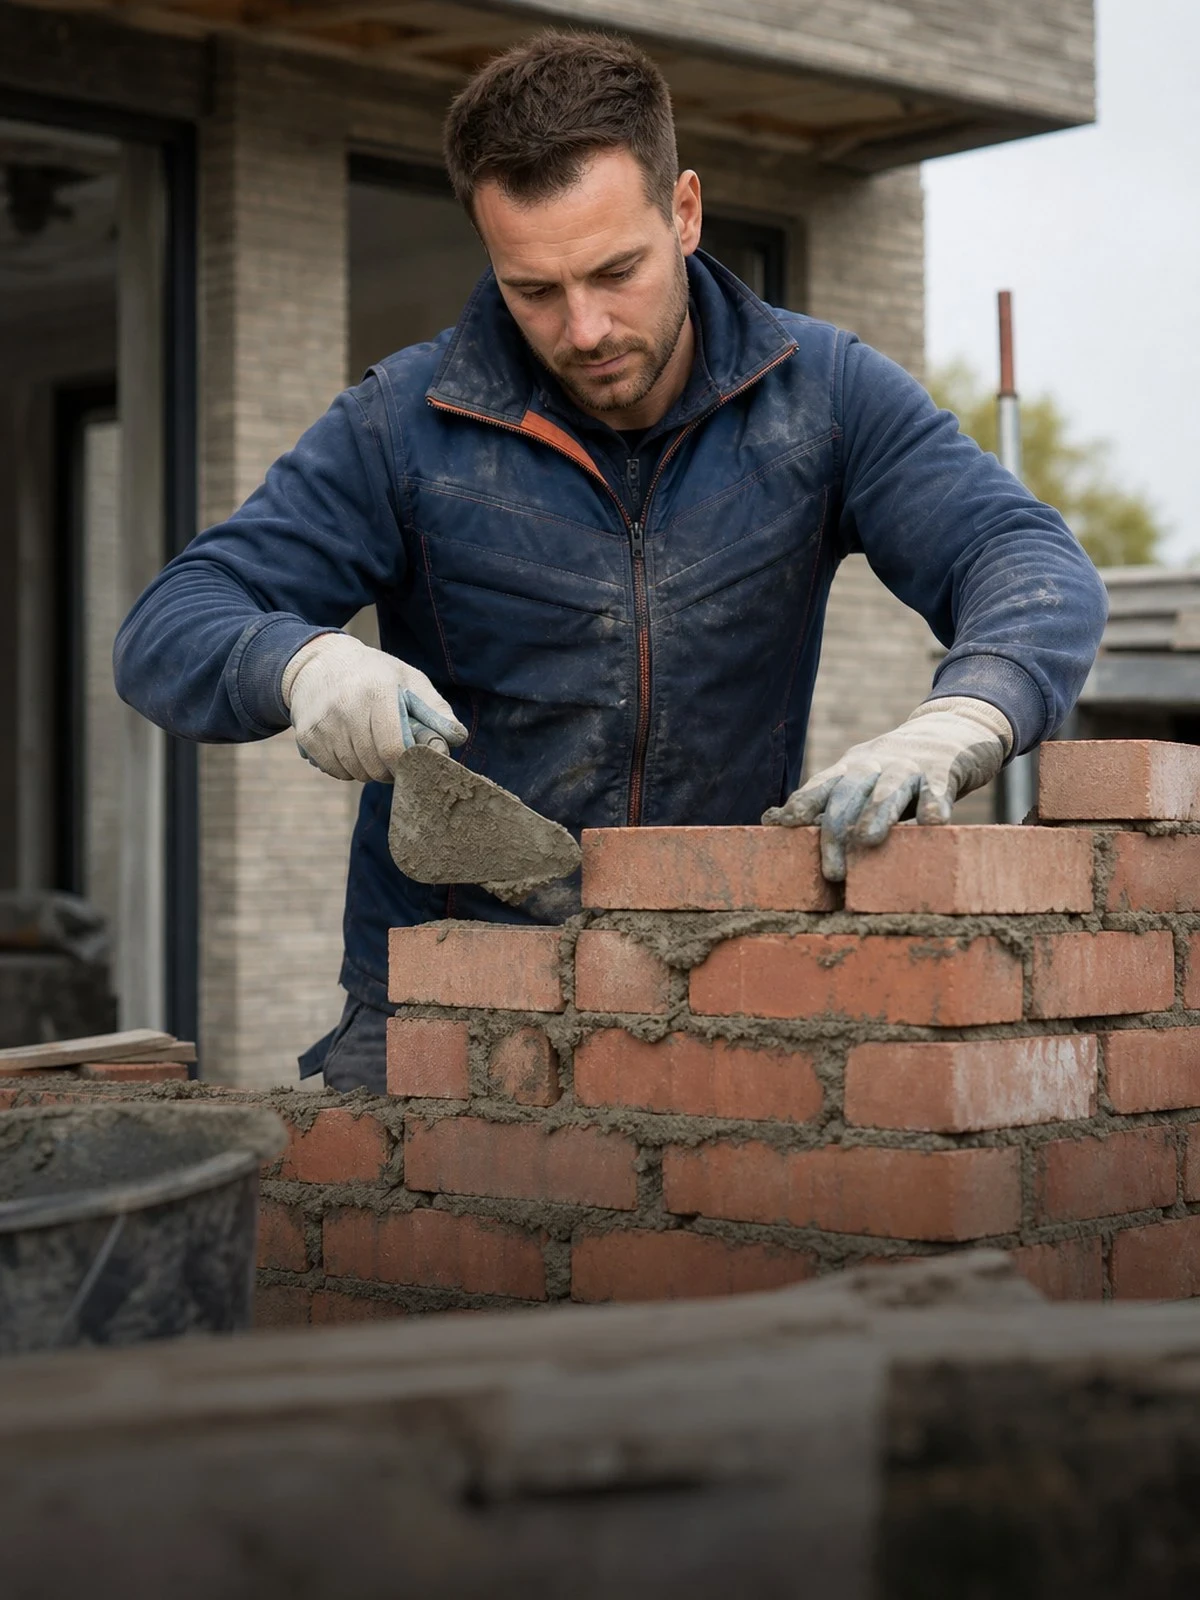
The first risk is falling material. A brick, a wheelbarrow or a bucket of mortar coming off a scaffold hits a parked car, a passer-by or the neighbours' roof. That is classic injury and property damage under Article 6:162 of the Dutch Civil Code and for that the AVB is intended for. If you work above a public road, an insurer looks at barriers, netting and the way material is taken up.
The second risk is the soiling. Mortar on new window frames, splashes on glass, cement haze on paving or on the resident's car: the damage is modest but the cleaning costs mount up. Insurers pay this as damage to other people's property, provided it is not part of the work you are delivering yourself. If it concerns the wall you are building, it falls under care, custody and control or under the exclusion for work carried out.
And that is the heart of the third category. Efflorescence, colour differences, a wall that is not flat, mortar chosen wrongly or insufficient cavity ventilation are defects in your own performance. Rebuilding, cutting out and putting right is performance of the contract and not insured. If such a defect causes damage to other parts of the building, moisture penetrating to the interior for instance, the liability cover does come into play. Damage to the works under construction itself falls under the project's Construction all risks (CAR) insurance.
This page deals with one situation. The full overview is on Compare public and employers' liability insurance (AVB).
Independent, personal, sorted quickly
We compare your business liability insurance (AVB) across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
 Business liability insurance (AVB)
 Compare
 Get covered
Why arrange it through Finass Verzekert?
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
Independent
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
One fixed adviser
You call or email someone who knows your file. No menu options, no changing call centres.
Switching without hassle
We cancel your old policy and align the start date, so you are never a day without cover.
Help with claims
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
What facade work runs into
Four points that make the difference in bricklaying between covered and paying yourself.
Working above people
An injury claim from a falling brick is the heaviest claim in this trade and can run on for decades where there is permanent injury. Make sure the sum insured is set accordingly and that you can show the measures taken: barriers, netting, and material not left loose on the edge.
Cleaning against replacement
Cement haze on glass sometimes cannot be removed without damaging the glass. The argument is then about cleaning or replacement costs. Report this straight away and have the damage assessed before anyone experiments with acid. A failed cleaning attempt makes both the damage and your position worse.
Someone else's scaffold
If you stand on a scaffold the main contractor had erected, that scaffold is property you use but do not own. If you damage it, the care, custody and control provisioncomes into play. If the scaffold collapses because of a defect, the question is who is liable as possessor or user; record who released the scaffold for use.
Cracks and settlement
Cracking in an existing facade after adjoining brickwork or after demolition nearby often leads to a claim from the neighbours. A a pre-works survey with photographs of the existing cracks is then the only defence that works. Without a baseline survey you effectively carry the burden of proof.
What does your premium depend on?
- Turnover or days worked: the usual basis for a sole trader
- Working at height: facade work above a public road weighs more heavily
- New build or refurbishment: existing work brings more causes of loss with it
- Restoration and listed buildings: higher repair costs for the same mistake
- Your own terms of supply: these determine what you accept by contract
- Sum insured and excess: per claim and per insurance year
Insurers weigh these details differently. That is where your saving is.
What is covered
| Situation | AVB | BAV |
|---|---|---|
| Cement haze settles on the car of the resident parked beside your scaffold | Yes | No |
| A brick falls off the scaffold through the roof of the neighbours' conservatory | Yes | No |
| Moisture penetration damages the plasterwork inside because the cavity was insufficiently ventilated | Yes | No |
| Cutting out and rebuilding a wall with a visible colour difference in the mortar | No | No |
| A storm blows over brickwork under construction that has not yet cured | No | No |
| The client follows your advice on materials and the joints are destroyed by frost in the first winter | No | Yes |
Rebuilding your own brickwork is performance of the contract. The damage arising around it is not.
Frequently asked questions
This is what people ask us most.
Is rebuilding a rejected wall covered?
No. What you have to rebuild is the performance you were paid for, and that is not damage to a third party. Insurers exclude this under the provision on work carried out. If the defect causes damage to other parts of the building or to the contents, that consequential loss is insured in principle.
Who pays for the car hit by a falling brick?
If you are liable, the damage to that car falls on your liability insurance. The owner's own-damage insurer often pays first and then recovers the loss from you. Report the incident yourself as well, even if no one has claimed yet; Article 7:941 of the Dutch Civil Code calls for notification as soon as you are reasonably aware.
Am I covered under the main contractor's CAR insurance?
Sometimes as a joint insured, but that policy covers damage to the works under construction and not your liability towards third parties. Ask in writing whether you are on the project policy and what excess applies. Do not assume that cover replaces your own public and employers' liability insurance; clients almost always require both side by side.
What if I cause damage on a site I was not allowed to enter?
Liability simply continues to exist, but cover can come under pressure if the policy sets requirements about how you work or if there is wilful recklessness. Article 7:952 of the Dutch Civil Code excludes damage caused with intent or through recklessness. Keep to the barriers and to the site manager's instructions.
Every situation is different. For these situations we have a separate page.
- Compare public and employers' liability insurance (AVB)The main page
- Liability insurance for a bricklaying firmGangs at height, facade cleaning, baseline surveys
- Liability insurance for a roofing companyCare, custody and control, hot work, leaks
- Liability insurance for a self-employed professional in the contracting tradeSubcontracting, care, custody and control, indemnity
- Liability insurance for a self-employed glazierBreakage, care, custody and control, safety glass
- Liability insurance for a self-employed welderWorking alone, follow-up checks, the workpiece
- Liability insurance for a self-employed mechanicProperty being worked on, call-out service, downtime
- Liability insurance for a plastering companyDust exposure, spray work, external facades
- Liability insurance for a self-employed rooferOpen roof, torch, care, custody and control