

Extended cover
- Fire, smoke and lightning strike
- Storm from force 7 upwards
- Water damage and leakage
- Burglary damage
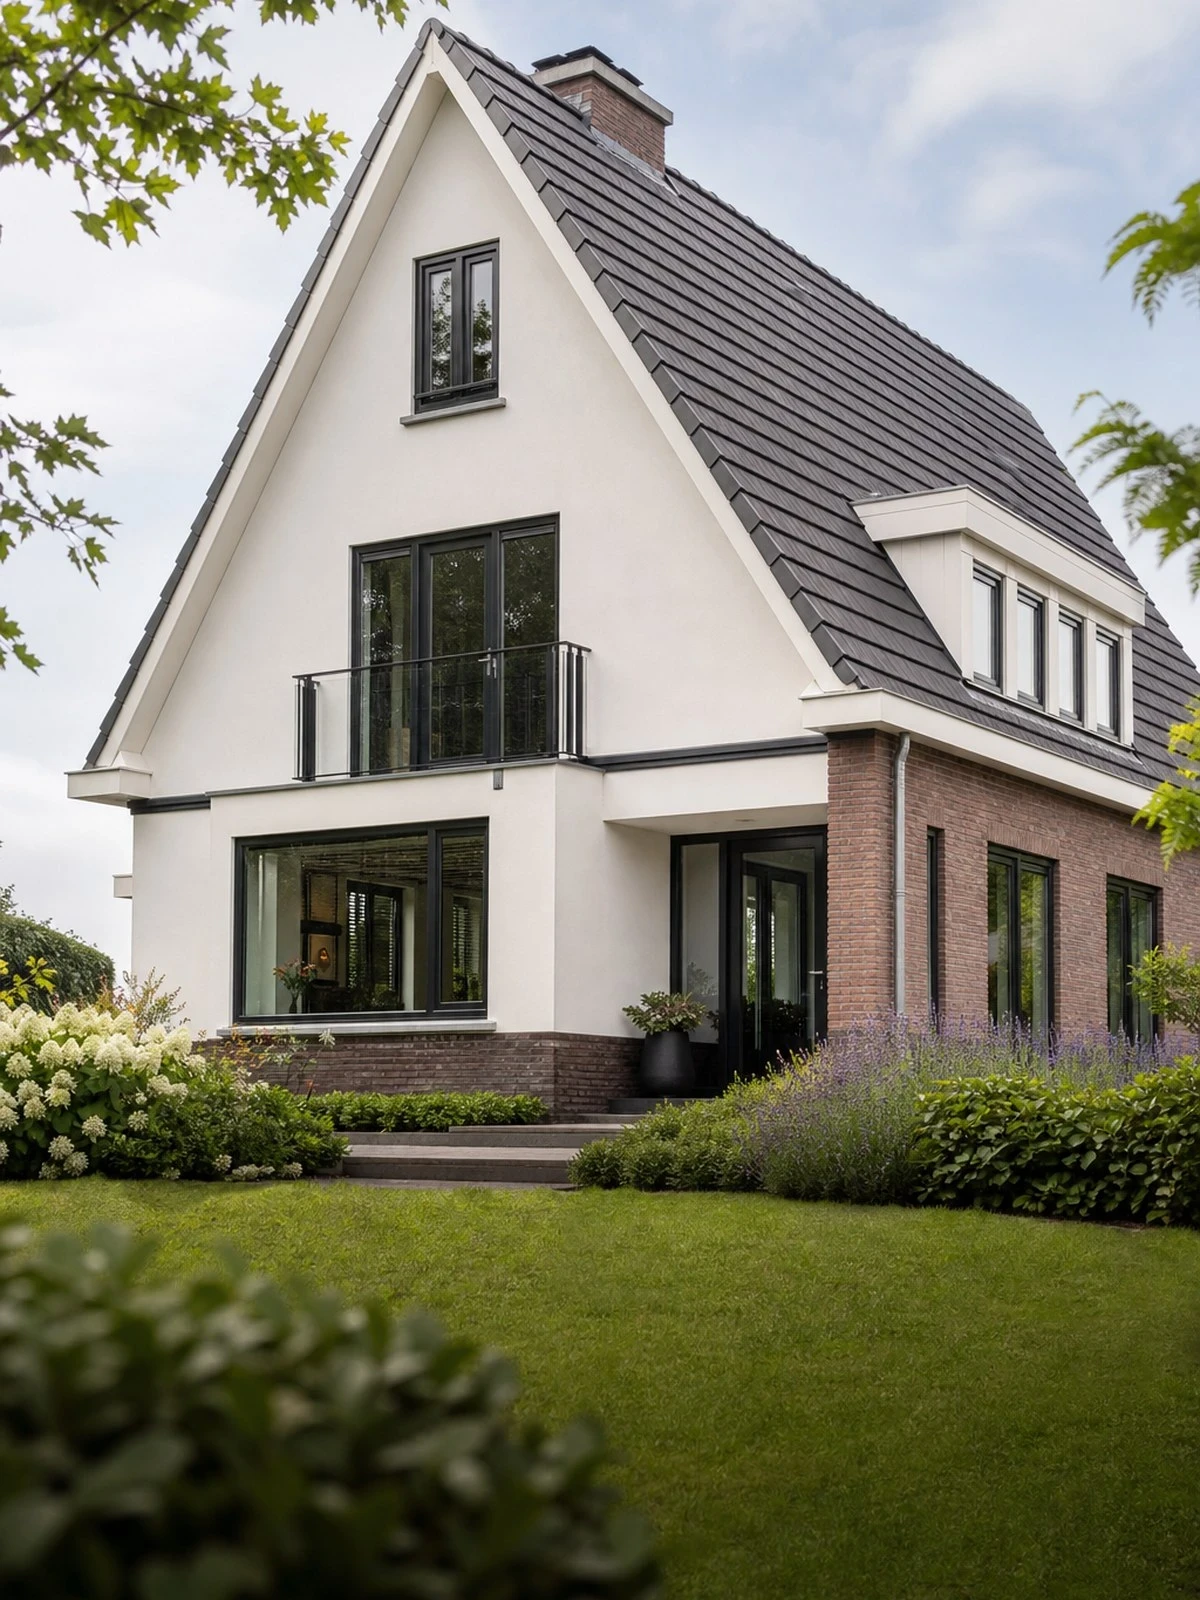
Building detached means four external walls, a roof entirely of your own and a plot on which everything is yours. That form determines both the rebuild value and the pattern of claims.
This page in another language: Nederlands · Deutsch
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
A detached house has more facade and more roof area per cubic metre of living space than a house in a terrace. With a mid-terrace house the neighbours carry two walls; with an end-terrace house one of them. Here the entire envelope is on your policy. So complete the rebuild value tool with the actual roof form, all extensions and additions and the actual roof covering, and not with a rounded estimate of the floor area.
The second difference lies in the plot. Trees, boundary fencing, the drive, external lighting and the pipes and cables running from the boundary across your own land are your responsibility, as are the shed, garage or carport. They are also often a short distance from the main building, so that a fire can spread within your own grounds without any neighbouring property being involved.
Finally, the location counts. Outside built-up areas the response time is longer, open water for firefighting is sometimes lacking and nobody sees the smoke or a break-in. If your concern is not the form of construction but a high-end finish, read buildings insurance for a villa. If the house is not permanently occupied, see buildings insurance for a second home.
We compare your buildings insurance across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
 Buildings insurance
 Compare
 Get covered
The structure of the cover in three parts, with an overview per situation below.
The named perils: fire, storm, water, burglary and collision.
All sudden and unforeseen damage from outside, unless excluded.
Rebuild value with a guarantee against underinsurance, or a valuation.
What is covered
| Situation | Extended | Comprehensive |
|---|---|---|
| Fire, smoke and lightning damage | Yes | Yes |
| Storm damage from force 7 upwards | Yes | Yes |
| Water damage from a burst pipe | Yes | Yes |
| Burglary damage to doors and frames | Yes | Yes |
| Drilling through a pipe while doing DIY | No | Yes |
| Subsidence, pile rot and deferred maintenance | No | No |
This overview is general in nature and is not personal advice. What is actually covered, including exclusions, limits and the excess, is set out in the policy conditions and the insurance card (verzekeringskaart) of the insurer; you receive both before you take out cover. Taking out cover without advice? Then read what execution only means for you.
Insurers weigh these details differently. That is where your saving is.
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
You call or email someone who knows your file. No menu options, no changing call centres.
We cancel your old policy and align the start date, so you are never a day without cover.
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
Customers rate our service on four aspects: personal service, service delivery, availability and the outcome. The reviews are collected and published by NH1816 and come from customers who have actually taken out a policy with Finass Advies B.V. or reported a claim.
Four points that make the difference between a policy that pays out and one that does not.
With nothing adjoining, the wind acts on every side and on the full roof surfaces. Ridge tiles, roof tiles, chimneys and dormer windows are therefore the most common storm claims with this type of house. Cover only starts at force 7; if the wind is weaker, you pay yourself. Damage that can be traced back to aged or loose roof covering also falls under the exclusion for poor maintenance, and a tree that blows over is not paid for itself.
A shed, garage, garden house, carport and canopy do not automatically fall under the buildings cover, or only up to a low maximum. Give the floor area and construction type for each outbuilding: a timber garden house is assessed differently from a brick garage, and the distance to the main building determines the chance of fire spreading within your own grounds. Boundary fencing, paving and external lighting also often have a sub-limit of their own.
If the house stands on an unmade road, far from the village or without a hydrant or open water nearby, firefighting takes longer and the damage grows. Insurers ask about this on the application. An incorrect or incomplete answer touches the duty of disclosure under Article 7:928 of the Dutch Civil Code and can lead to the payout being reduced or refused under Article 7:930 of the Dutch Civil Code.
With a detached house, the connections for water, gas, electricity and drainage often run along a long route of your own, sometimes with a well, a propane tank or your own treatment plant. A leak or break in that section is your risk and not the network operator's. Damage caused by groundwater, flooding from outside and settlement remains excluded; for the last of these, see buildings insurance and foundations.
With a detached house these are more often present. Declare them with a value; they are not always insured as standard.
If you fill in the insurer's rebuild value calculator correctly, you will usually receive a guarantee against underinsurance: in the event of a claim the actual amount is paid, even if the sum insured turns out to be too low. Your policy schedule states whether you have that guarantee. Without it, the proportionality rule applies, and that also affects small claims.
This is what people ask us most.
Because you pay for the whole envelope yourself. A mid-terrace house shares two walls with the neighbours and has part of a continuous roof. A detached house has four elevations of its own, a complete roof of its own and usually a roof form with more corners. So considerably more has to be rebuilt per cubic metre of living space.
No. Outbuildings fall outside the cover, or are covered up to a limited maximum, for as long as you do not declare them. Report for each outbuilding the floor area, the construction type and whether there is an electricity connection. A timber canopy against the facade is assessed differently from a free-standing brick garage, partly because of the risk of fire spreading.
The damage to the roof and the structure falls under the storm cover, provided the wind was strong enough. The tree itself is not paid for and many policies apply a separate maximum to clearing and removing it. If the tree was visibly dead or diseased, the insurer can attribute the damage to poor maintenance.
Yes. A longer response time and the absence of a hydrant or open water mean that a fire burns for longer before it is put out. Insurers ask about this on the application and reflect it in the underwriting and the premium. Give the situation honestly; incorrect information can affect the payout in a later fire.
Every situation is different. For these situations we have a separate page.
Request a quote without obligation. We will look at which insurer best matches your activities and your risk.
Prefer to call? 072 - 509 24 56, weekdays 09:00–17:00.
Claim on the road? Emergency line 06 - 55 20 40 72.
Finass Verzekert is a trading name of Finass Advies B.V. We advise on and arrange non-life insurance on the basis of an objective analysis of several insurers, and receive commission for this from the insurer, which is included in the premium. You pay no separate advice fee. Before you take out cover, we establish your wishes and needs.
You will find our licence, KvK and Kifid details and our complaints procedure at the foot of every page.
This page was compiled by Finass Verzekert (LinkedIn). Last updated on .
The information on this page is general in nature and is not personal advice.
Maandag- Vrijdag: 09:00- 17:00
We use cookies and similar technologies to improve your experience on our website.