

Comprehensive worldwide
- Loss and disappearance
- Theft from the wrist
- Damage from falls and knocks
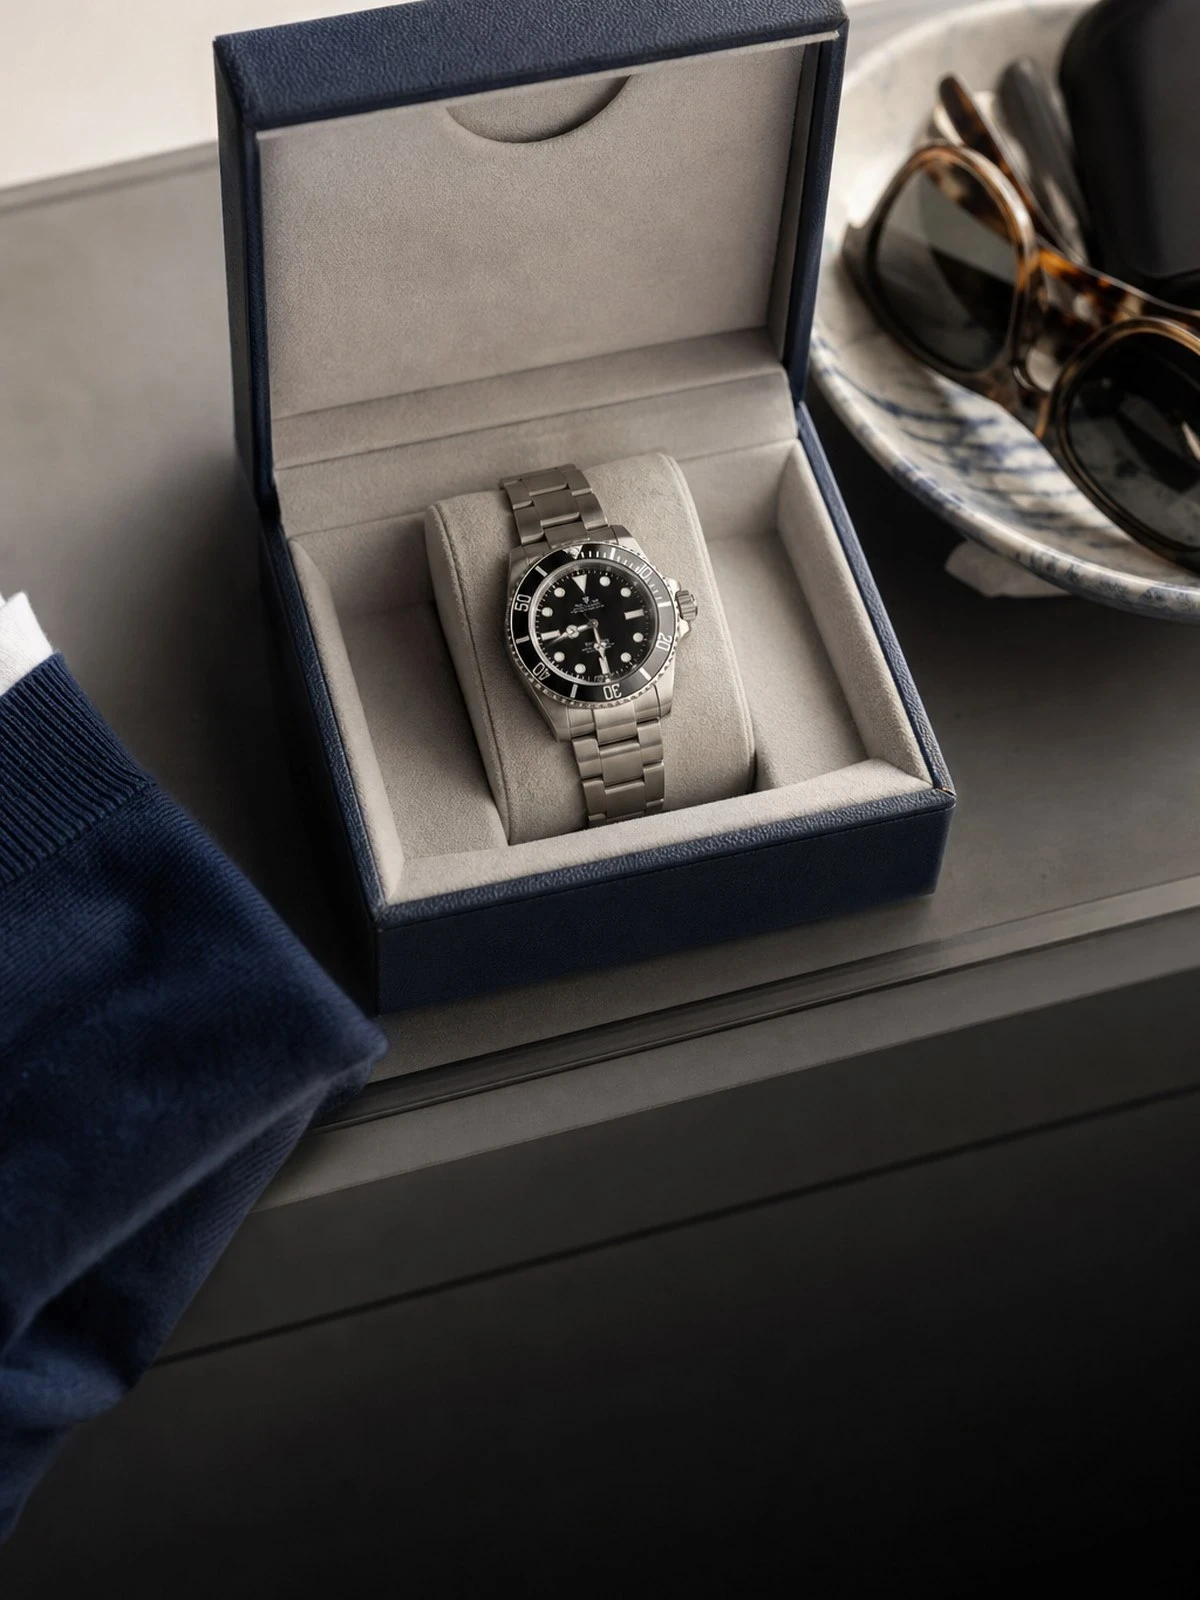
With Rolex the problem is not the movement but the saleability: a watch everyone recognizes and that can be sold anywhere straight away is stolen differently and valued differently.
The calculator and the quote form below are in Dutch. Prefer to do this in English? E-mail info@finassesures.nl or call 072 - 509 24 56 and we will take it from there.
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
A premium indication, not Personal advice. Prefer to talk it through? Call 072 - 509 24 56.
Rolex is the make that appears most often on a Valuables insurance, and there is one reason for that: the second-hand market is deep and liquid. A stolen example is sold on within a day, including abroad. So the risk here is not falling down the stairs but targeted theft, in the street, at a pavement cafe or on arriving home. home contents insurance barely covers that away from the home, and covers loss nowhere.
The second peculiarity is how the value moves. With sought-after references the market value moves out of step with the original purchase price, and a Valuation report a few years old then no longer matches what replacement costs. So have a new Valuation carried out when the Valuation period ends and have the report drawn up as intended in Article 7:960 of the Dutch Civil Code; only then is the amount fixed for the term of the policy.
The third point is identification. A Rolex can be traced unambiguously by its reference and serial number, which helps with the police report, with registration in stolen-property registers and with showing that the Watch existed. Record those numbers together with the purchase invoice, the warranty card and photographs of the case, bracelet and clasp, and keep that file away from the home.
We compare your Valuables insurance across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
 valuables insurance
 Compare
 Get covered
The structure of the cover in three parts, with an overview per Situation below.
Loss, theft and damage, wherever you are.
A recognized valuer records the value, usually for three to five years.
Provisions that determine when you are covered.
What is covered
| Situation | Valuables | Home contents |
|---|---|---|
| A Rolex lost on holiday | Yes | No |
| Stolen from the wrist in the street | Yes | No |
| Theft at Home during a burglary | Yes | Sometimes |
| Damage through your own actions | Yes | No |
| Not in the safe when it should have been | No | No |
| Wear and loss of value | No | No |
This overview is general in nature and is not personal advice. What is actually covered, including exclusions, limits and the excess, is set out in the policy conditions and the Insurance card (insurance card) of the insurer; you receive both before you take out Cover. Taking out Cover without advice? Then read what Execution only means for you.
Insurers weigh these details differently. That's where your saving is.
We look at the terms as well as the premium, and stay your point of Contact when there is a claim.
We are not tied to one insurer and Compare on the basis of an objective analysis of several companies.
You call or email someone who knows your file. No menu options, no changing call centers.
We cancel your old policy and align the start date, so you are never a day without Cover.
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
Customers rate our service on four aspects: personal service, service delivery, availability and the outcome. The reviews are collected and published by NH1816 and come from customers who have actually taken out a policy with Finass Advies BV or reported a claim.
Four points that make the difference between a policy that pays out and one that does not.
Anyone wearing a Rolex is wearing a make that can be recognized from a distance. Insurers know that and translate it into wearing and safe clauses: above a certain amount the watch is in the safe when you are not wearing it, sometimes with an alarm connected to a monitoring center. That is not small print but the heart of the theft cover, and it is the most common reason why a claim is refused.
A Valuation within the meaning of Article 7:960 of the Dutch Civil Code binds the insurer to the amount established for as long as the report is valid. If it expires and the loss happens after that, you fall back on market value and the argument becomes what the watch is worth now. With a make whose market value moves, having a new Valuation carried out in time is the difference between replacing and paying in.
After a loss or theft the first question is which Watch it was exactly and what it was worth. Without an invoice, warranty card and serial number that becomes a reconstruction after the event. Photograph the case, dial, bracelet and clasp and keep everything digitally away from the home, so that it does not disappear along with the Watch after a burglary or fire. Report theft to the police at once; that report is a condition under Article 7:941 of the Dutch Civil Code.
A fall in the value of the reference is not damage and is paid nowhere. Wear of the bracelet, clasp and glass goes with use. Theft while the watch was outside the safe when the clause requiring it to be inside is excluded. And a repair outside the authorized network with non-original parts depresses the valuation amount. The difference that creates is not an assured loss but your own choice.
Rolex is the make most often stolen from the wrist; insurers work here with wearing and safe clauses. Above a certain amount it almost always applies that the watch is in the safe when you are not wearing it, sometimes with a requirement for an alarm connected to a monitoring center. After a theft that is the first thing you will be asked about, and it is the most common reason for refusal.
Servicing by an authorized service center maintains the value. A non-original repair depresses the valuation amount. Also keep the invoice, the box, the papers and the serial number, and photograph everything. After a loss the first question is whether the watch existed and what it was worth; keep that file digitally and not only at home.
This is what people ask us most.
At home often up to a low sub-limit for jewelery and watches, away from home almost never, and loss is not covered anywhere. With this make it precisely away from the home that the loss arises. A valuables policy is comprehensive, applies worldwide and covers loss and unexplained disappearance as well; that last point is the decisive difference between the two policies.
A Valuation report is usually valid for three to five years. With Rolex that period is also relevant in practice, because the market value of sought-after references can shift within it. Have the report renewed before the expiry date: if the loss happens after it expires, you fall back on market value and lose the protection of Article 7:960 of the Dutch Civil Code.
That is theft with violence and is in principle covered on a Valuables policy, provided you were wearing the watch as the policy allows. Report it to the police at once and notify the insurer as soon as possible; Article 7:941 of the Dutch Civil Code requires immediate notification. Pass on the serial number, so that the Watch can be entered in the stolen-property registers.
You may, but it has consequences. Servicing by an authorized service center with original parts maintains the valuation amount; replaced dials, aftermarket parts or an over-polished case depress that value. It becomes visible at a later revaluation, and the difference in value that this creates is not an assured loss.
Every Situation is different. For these situations we have a separate page.
Request a Quote without obligation. We will look at which insurer best matches your activities and your risk.
Prefer to call? 072 - 509 24 56, weekdays 09:00–17:00.
Claim on the road? Emergency line 06 - 55 20 40 72.
Finass Verzekert is a trading name of Finass Advies BV We advise on and arrange non-life insurance on the basis of an objective analysis of several insurers, and receive commission for this from the insurer, which is included in the premium. You pay no separate advice fee. Before you take out cover, we establish your wishes and needs.
You will find our license, Chamber of Commerce and Kifid details and our complaints procedure at the foot of every page.
This page was compiled by Finass Insures (LinkedIn). Last updated on .
The information on this page is general in nature and is not Personal advice.
Monday-Friday: 09:00-17:00
We use cookies and similar technologies to improve your experience on our website.