

Liability
- Collision and jetty damage
- No legal obligation
- Often required by the marina
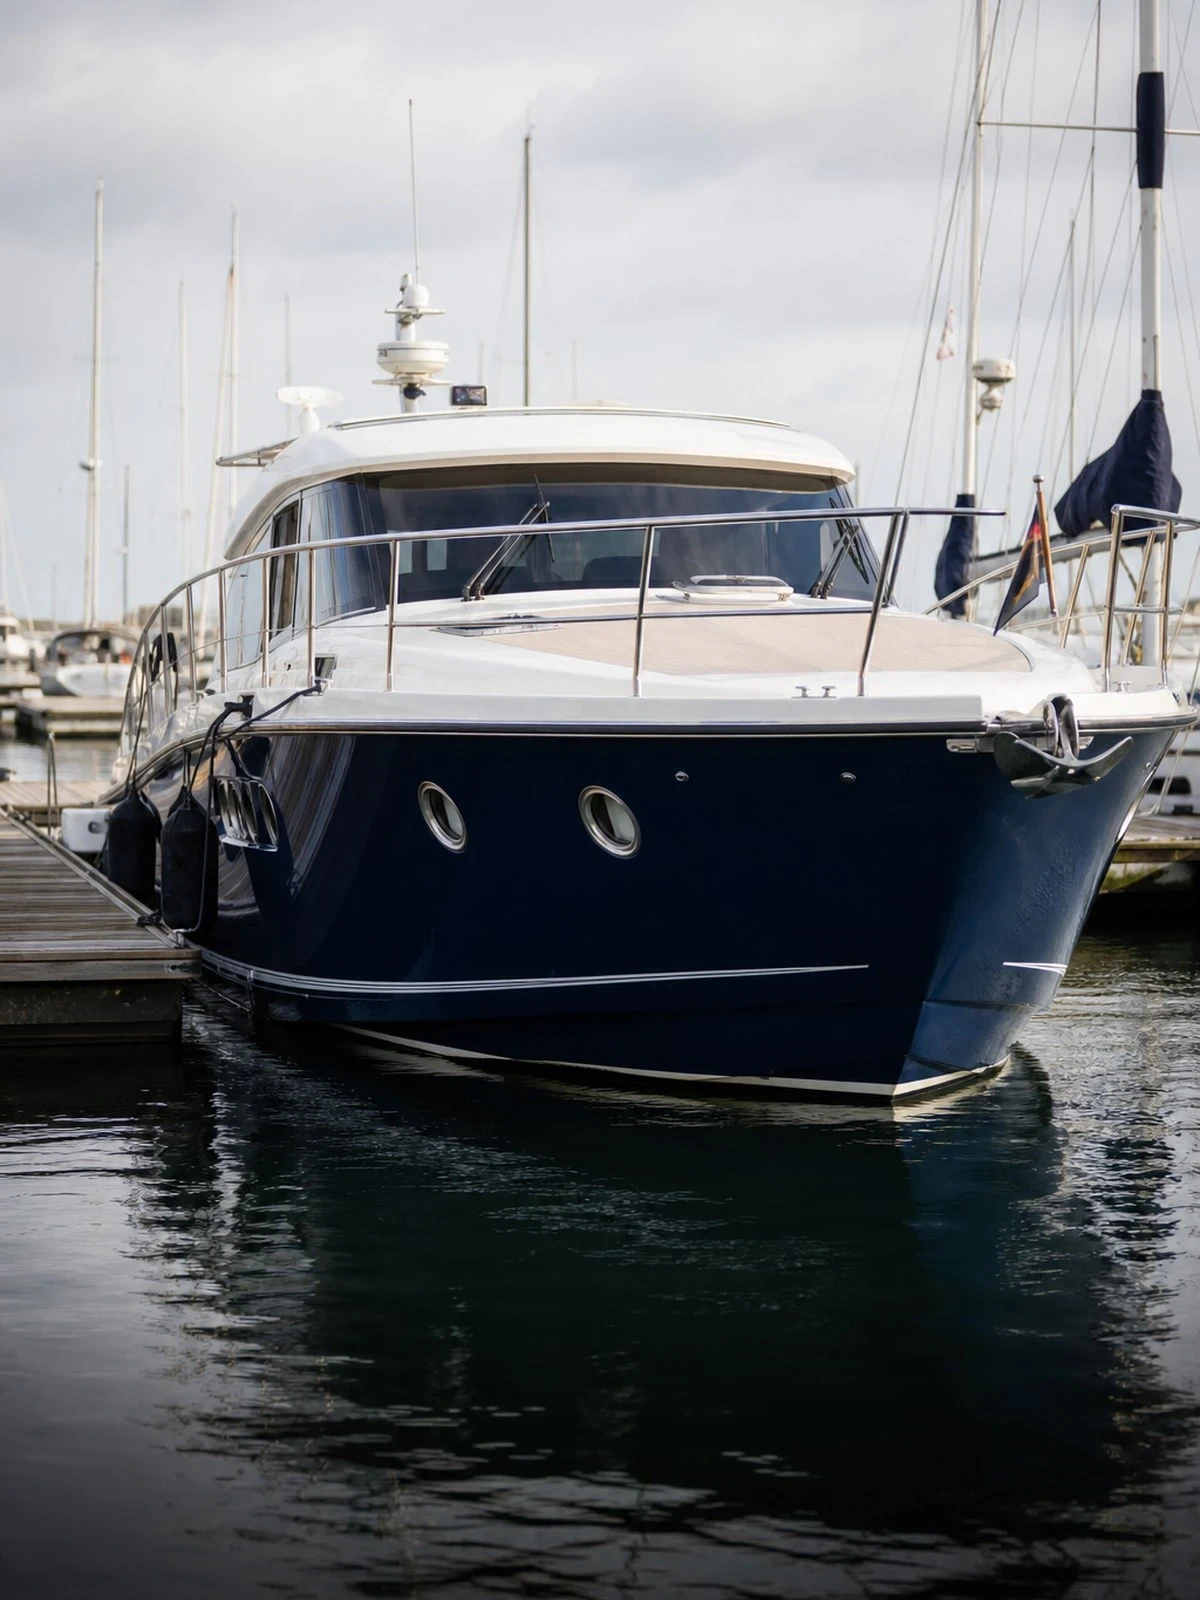
On a larger yacht the policy is no longer a product but a file: where do you sail, who sails, where does the vessel lie in winter, and who is liable if the yard makes a mistake.
This page in another language: Nederlands
The calculator and the quote form below are in Dutch. Prefer to do this in English? Email info@finassverzekert.nl or call 072 - 509 24 56 and we will take it from there.
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
Larger yachts are insured on agreed value. On a vessel with an unusual refit, a bespoke interior or a documented history, that is the only figure that holds up in the event of a total loss; market value does not do it justice.
The sailing area is the decisive policy condition. Inland waters, coastal waters, the North Sea, the Mediterranean and ocean passages are separate categories. If you sail outside the stated area, there is no cover. Not even in fine weather.
Where crew and work are involved, liability comes into play: towards those on board, towards paid crew and towards the yard. The last of these matters above all during lifting, masting and time ashore.
We compare your pleasure craft insurance across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
 Pleasure craft insurance
 Compare
 Get covered
The structure of the cover in three parts, with an overview per situation below.
Damage you cause to others with the vessel.
Damage to the boat, the engine and the fixed equipment.
What you add separately.
What is covered
| Situation | Liability | Own-damage cover |
|---|---|---|
| Damage to another vessel or a jetty | Yes | No |
| Theft of the boat or the outboard motor | No | Provided that |
| Fire and storm damage in the berth or ashore | No | Yes |
| Sinking through a leak or through rainwater | No | Provided that |
| Salvage and removal of the wreck | Provided that | Provided that |
| Osmosis, wear and deferred maintenance | No | No |
There is no statutory insurance requirement for pleasure craft. The WAM applies only to motor vehicles. Marinas, harbours and hire companies do generally require liability cover. Pay attention to the sailing area described and to the lay-up or winter storage period: outside the sailing area or during undeclared storage, cover may lapse.
This overview is general in nature and is not personal advice. What is actually covered, including exclusions, limits and the excess, is set out in the policy conditions and the insurance card (verzekeringskaart) of the insurer; you receive both before you take out cover. Taking out cover without advice? Then read what execution only means for you.
Insurers weigh these details differently. That is where your saving is.
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
You call or email someone who knows your file. No menu options, no changing call centres.
We cancel your old policy and align the start date, so you are never a day without cover.
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
Customers rate our service on four aspects: personal service, service delivery, availability and the outcome. The reviews are collected and published by NH1816 and come from customers who have actually taken out a policy with Finass Advies B.V. or reported a claim.
Four points that make the difference between a policy that pays out and one that does not.
If the vessel sinks in a navigation channel or a harbour, the authority can require it to be salvaged: and those costs can exceed the value of the vessel. Check whether wreck removal is separately included and up to what amount. It is not automatic and on larger vessels it mounts up quickly.
Lifting, masting, transport by road and time ashore are classic moments for damage. The yard often covers this through its own policy, but not always and not in full. Ask the yard for evidence of insurance and record from what moment the risk passes; otherwise you end up with two insurers pointing at each other.
If a skipper or a maintenance engineer sails with you for payment, that is employment or hiring in, not guests on board. Liability for injury to crew does not automatically fall under a pleasure craft policy; declare it and have it recorded how it is arranged.
A new engine, an interior refit or new navigation electronics change the value considerably. Without a revaluation you are carrying an out-of-date figure. Have it recorded as soon as the work is finished, invoice included. On a total loss that is the file on which payment is based.
This is what people ask us most.
Because market value does not do justice to refits, bespoke work and history. With a valuation the amount is fixed and there is no discussion on a total loss. Have the vessel revalued after major investments.
Then there is no cover. Sailing areas are sharply defined. For a one-off crossing or trip you apply for a temporary extension.
Not automatically. Check whether it has been separately included and up to what amount. On larger vessels those costs can exceed the value.
Often the yard, but not always and not in full. Ask for evidence of insurance and record from what moment the risk passes.
Not automatically. If people work on board for payment, employers' or hirers' liability comes into play and a separate arrangement is needed.
No. Osmosis, wear and deferred maintenance count as gradual processes and fall outside every policy.
Every situation is different. For these situations we have a separate page.
Request a quote without obligation. We will look at which insurer best matches your activities and your risk.
Prefer to call? 072 - 509 24 56, weekdays 09:00–17:00.
Claim on the road? Emergency line 06 - 55 20 40 72.
Finass Verzekert is a trading name of Finass Advies B.V. We advise on and arrange non-life insurance on the basis of an objective analysis of several insurers, and receive commission for this from the insurer, which is included in the premium. You pay no separate advice fee. Before you take out cover, we establish your wishes and needs.
You will find our licence, KvK and Kifid details and our complaints procedure at the foot of every page.
This page was compiled by Finass Verzekert. Last updated on .
The information on this page is general in nature and is not personal advice.
Maandag- Vrijdag: 09:00- 17:00
We use cookies and similar technologies to improve your experience on our website.