

High-end new build
- Bespoke work and natural stone in the finish
- Home automation, climate and swimming pool plant
- Security requirements at underwriting
- Rebuild value through a valuation
A villa or country house does not fit the standard model of buildings insurance. The sum insured, the underwriting requirements and the outbuildings all call for a tailored approach.
This page in another language: Nederlands
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
For an ordinary house, the insurer calculates the sum insured with a rebuild value calculator. With a villa or country house that instrument no longer works: the tool works with standard prices per cubic metre and knows nothing of natural stone, craft brickwork, high ceilings, cellars, a thatched roof or heritage detailing. The figure it produces is structurally too low, and you only notice that in a large claim.
For this type of property a valuation by an expert is therefore used. Have it drawn up under Article 7:960 of the Dutch Civil Code, with the additional provision that the report establishes the rebuild value. Such a valuation fixes the value for an agreed period; within that period the insurer cannot rely on underinsurance. Make sure the report states the rebuild value and not just the market value: with a country house those two are far apart, usually to the owner's disadvantage.
A country house is also rarely a single building. A coach house, stables, an orangery, garden walls, fencing, a driveway and the landscaping itself are structures in their own right that belong separately on the policy schedule. Also read buildings insurance for villas and how high the sum insured should be.
We compare your buildings insurance across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
 Buildings insurance
 Compare
 Get covered
Both call for a valuation, but the risk profile differs on three points.
A modern volume with an expensive finish and installations, usually in or near a built-up area.
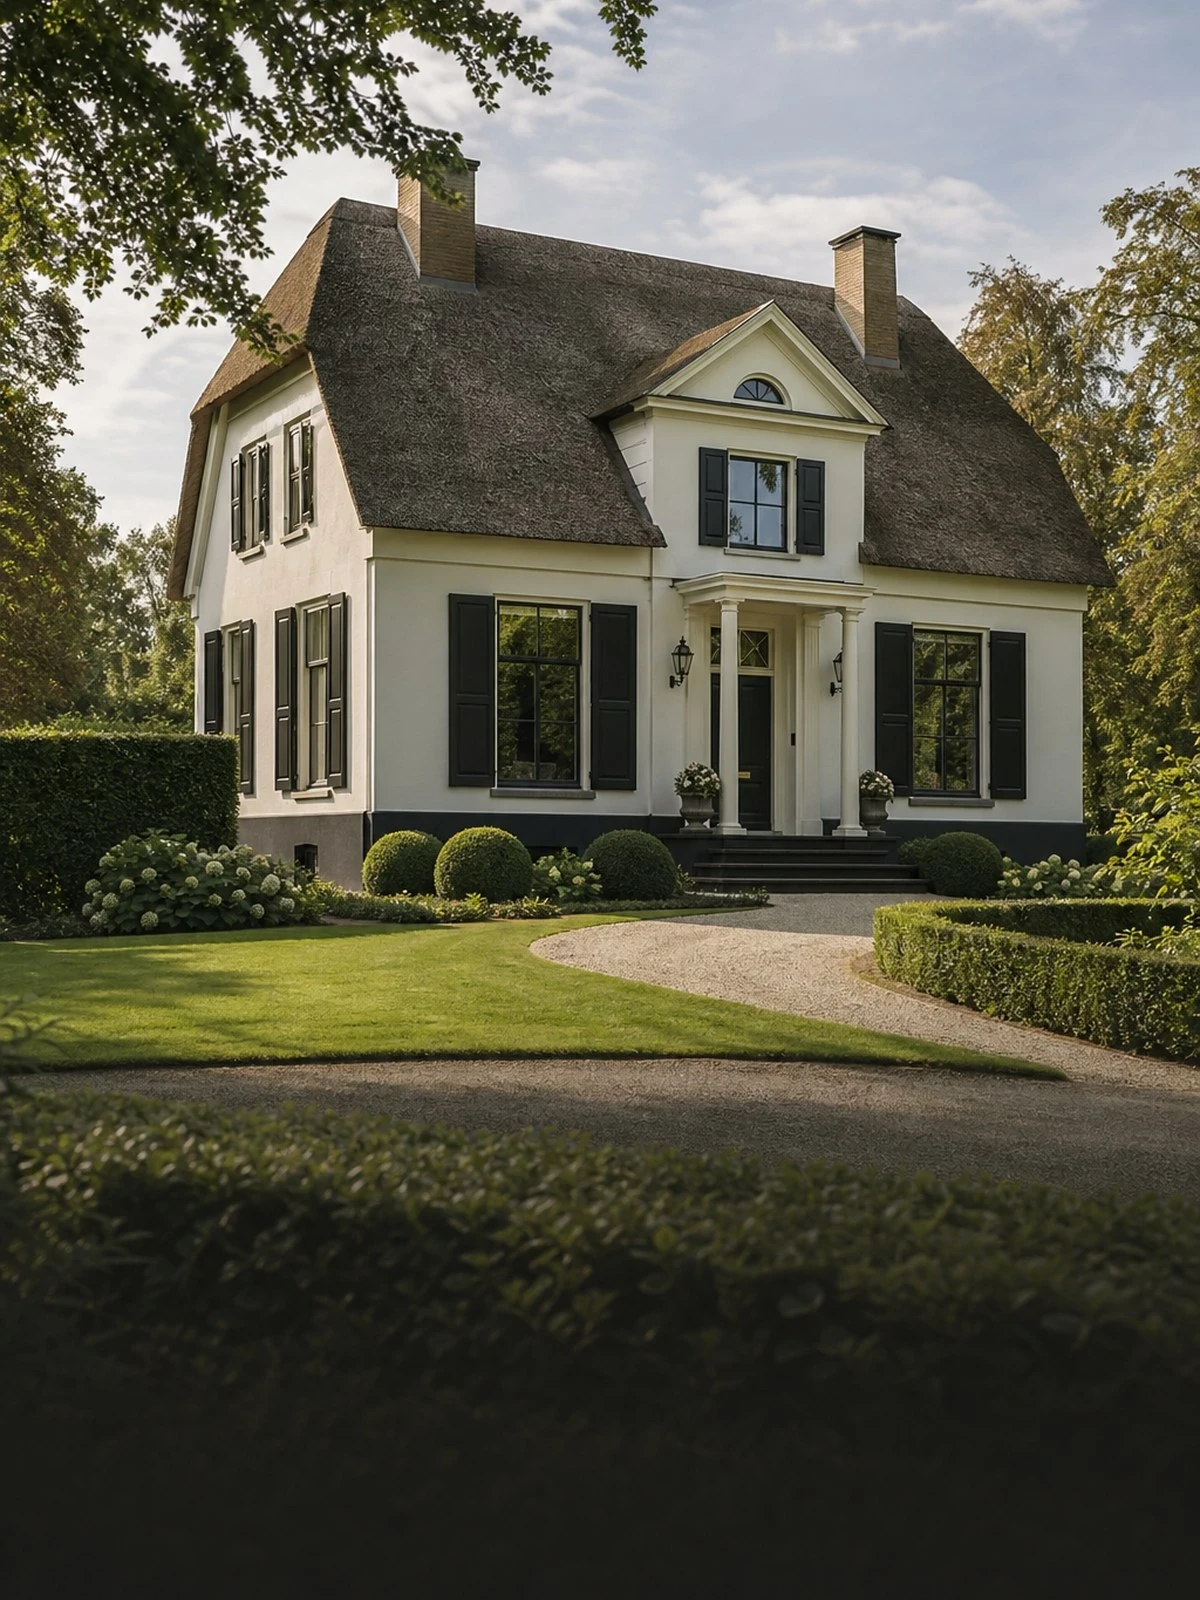
An older property, often with thatch, listed status and several outbuildings.
Everything outside the main building does not automatically count towards the sum insured.
What is covered
| Situation | Standard policy | Villa or country house |
|---|---|---|
| The sum insured through a rebuild value tool | Yes | No |
| Valuation with the effect of Article 7:960 of the Dutch Civil Code | No | Yes |
| A thatched roof and listed status | No | Provided that |
| Coach house, stables and other outbuildings | Provided that | Yes |
| Landscaping, fencing and the driveway | No | Provided that |
| Subsidence, foundation damage and pile rot | No | No |
What is actually covered, including exclusions, limits and the excess, is set out in the policy conditions and the insurance card (verzekeringskaart) that you receive before you take out cover.
Insurers weigh these details differently. That is where your saving is.
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
You call or email someone who knows your file. No menu options, no changing call centres.
We cancel your old policy and align the start date, so you are never a day without cover.
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
Customers rate our service on four aspects: personal service, service delivery, availability and the outcome. The reviews are collected and published by NH1816 and come from customers who have actually taken out a policy with Finass Advies B.V. or reported a claim.
Where a villa or country house departs from the standard policy, and why that matters.
Valuation tools are calibrated for ordinary house building and stop at a certain volume or level of finish. With a villa or country house the tool produces a sum that is too low. So work with a valuation report which, under Article 7:960 of the Dutch Civil Code establishes the rebuild value. Within the term of that report, underinsurance does not arise. If the period expires or you carry out major building work, have the valuation done again.
A a thatched roof increases the fire load; insurers set requirements for the flue, the chimney, the distance to naked flames and sometimes for lightning protection. With a listed building repair costs are higher because of prescribed materials and permits, and repairs take longer. Not every insurer accepts these properties. Both features should appear expressly in the valuation report and on the policy schedule.
A coach house, stable, orangery, garden wall or driveway does not automatically fall within the sum insured for the main building. Have each structure stated with its floor area, construction type and use. For garden layout and planting a maximum amount and a limited set of covered causes usually apply, with storm, frost and drought damage to planting falling outside the cover. If you keep animals or vehicles in an outbuilding, report that use as well.
A wider policy does not make the exclusions smaller. Outside the cover remain subsidence, foundation damage and pile rot, damage caused by deferred maintenance, wear and tear and construction or material faults, and damage caused by vermin, woodworm, mould and slowly penetrating damp. With older properties that matters: an attacked roof structure or rotted woodwork is maintenance, not damage. Intent and recklessness are excluded under Article 7:952 of the Dutch Civil Code.
This is what people ask us most.
The tool works with standard prices per cubic metre for ordinary house building. Craft brickwork, natural stone, high ceilings, cellars, a thatched roof and heritage detailing do not appear in that model. The result is structurally too low. Insurers therefore almost always accept a country house only on the basis of a valuation report by an expert.
Market value is what a buyer pays for the property, including the land and the location. Rebuild value is what it costs to build a similar property again on the same site to the applicable standards, excluding the land. With a listed country house the rebuild value is often higher than the market value, because prescribed materials and techniques are expensive and labour-intensive.
Yes, but the choice of insurers is smaller and the premium higher. Thatch increases the fire load, so requirements apply to the flue, the chimney, the distance to naked flames and sometimes to a lightning protection system. Those requirements appear as a clause on your policy. If you do not meet them when a fire occurs, the insurer can reduce the payout.
Only if they have been declared separately. Outbuildings are structures in their own right with their own construction type, floor area and use, and they are not automatically in the sum for the main building. If you use an outbuilding for animals, storage or an activity with a different risk profile, report that too; it can affect the underwriting and the premium.
Largely not. For landscaping a maximum amount and a limited set of causes usually apply, generally fire, explosion and impact. Storm, frost and drought damage to planting is in general outside that. Paving, garden walls and fencing can be insured, provided they are stated on the policy schedule.
Report that in advance. During a long absence or vacancy, many policies limit the cover to fire, storm and lightning and the cover for burglary and water damage lapses. Some conditions require the property to be kept heated or the water supply to be turned off. The duty of disclosure under Article 7:928 of the Dutch Civil Code applies to changes of use as well.
Every situation is different. For these situations we have a separate page.
Request a quote without obligation. We will arrange the valuation and assess the thatch, listed status and outbuildings.
Prefer to call? 072 - 509 24 56, weekdays 09:00–17:00.
Claim on the road? Emergency line 06 - 55 20 40 72.
Finass Verzekert is a trading name of Finass Advies B.V. We advise on and arrange non-life insurance on the basis of an objective analysis of several insurers, and receive commission for this from the insurer, which is included in the premium. You pay no separate advice fee. Before you take out cover, we establish your wishes and needs.
You will find our licence, KvK and Kifid details and our complaints procedure at the foot of every page.
This page was compiled by Finass Verzekert (LinkedIn). Last updated on .
The information on this page is general in nature and is not personal advice.
Maandag- Vrijdag: 09:00- 17:00
We use cookies and similar technologies to improve your experience on our website.