

Premises liability insurance
As the owner of a building you are liable for loss caused by defects in that building, even where you did nothing wrong. That is strict liability, and it is separate from your buildings insurance.
- several insurers compared objectively
- 9.5 customer rating for a new policy
- AFM licence 12016589
- Personal 072 - 509 24 56, weekdays 9–17
This page in another language: Nederlands
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
- We compare the offerings of several insurers
- An adviser checks whether the cover suits your activities
- We arrange the switch, including cancellation
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
- Independent advice
- Several insurers
- Switching arranged
- Help with claims
In brief
The law places on the owner of a building a strict liability: if the structure is defective and loss arises as a result, you are liable. Fault does not have to be proved.
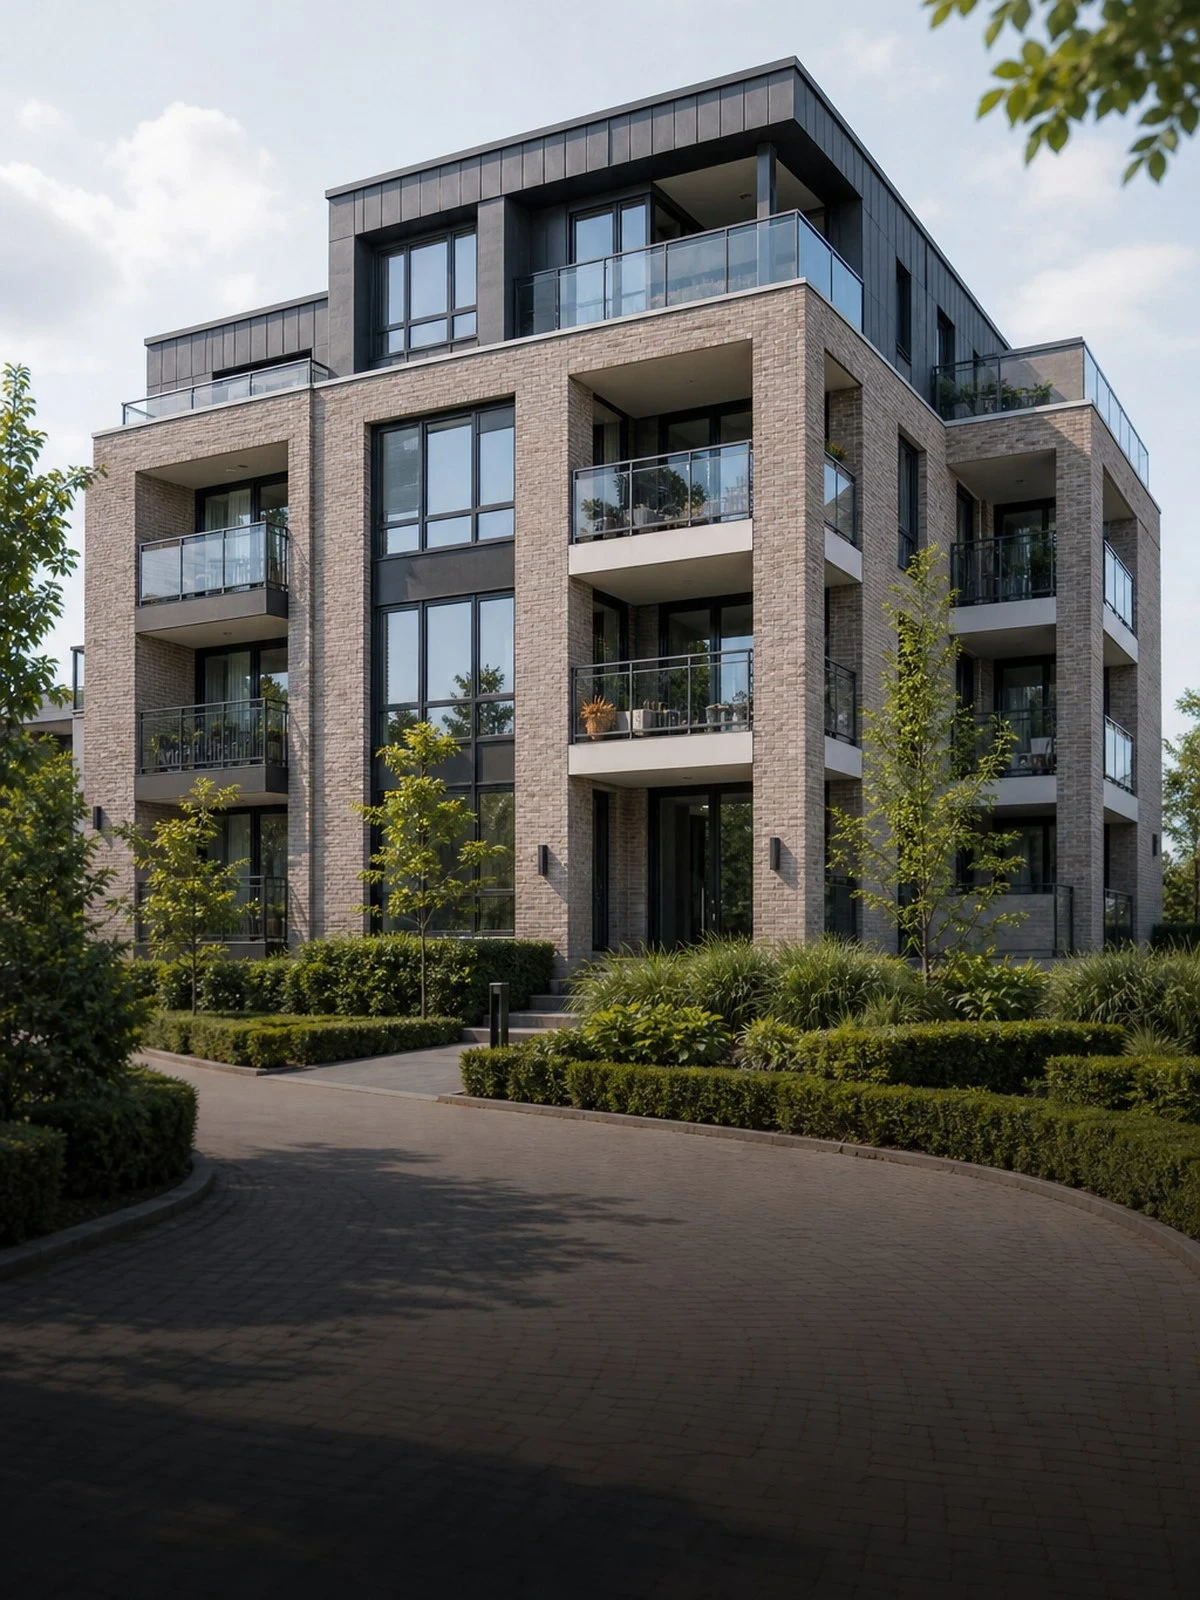
Think of a facade panel that comes loose, a defective balcony, a slippery entrance or a tree falling on your grounds. You cover that risk with property owners' liability insurance, not with the buildings policy.
This page deals with one part. The overview of all parts is on the main page on property insurance.
Independent, personal, sorted quickly
We compare your personal liability insurance (AVP) across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
 Personal liability insurance (AVP)
 Compare
 Get covered
Why arrange it through Finass Verzekert?
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
Independent
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
One fixed adviser
You call or email someone who knows your file. No menu options, no changing call centres.
Switching without hassle
We cancel your old policy and align the start date, so you are never a day without cover.
Help with claims
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
Customers rate our service on four aspects: personal service, service delivery, availability and the outcome. The reviews are collected and published by NH1816 and come from customers who have actually taken out a policy with Finass Advies B.V. or reported a claim.
What to look out for
Buildings cover and liability are two different things
Buildings insurance (opstalverzekering) pays for damage to the building. This policy covers the loss the building causes to others.
Maintenance is your defence
A maintenance plan that has demonstrably been carried out limits liability and helps in handling a claim.
Even when you let, you remain the owner
If you let the building, owner's liability stays with you. The tenant is liable for their own use.
Grounds, trees and car park
What stands outside the building on your grounds is also your responsibility. Include it in the cover.
What determines the premium
- Number and type of objects
- Total rebuild value or rental income
- State of maintenance and long-term maintenance plan
- Use: residential, office, retail or hospitality
- Sum insured per event
This information is general in nature and is not personal advice. What is actually covered, including exclusions and the excess, is set out in the policy conditions and the insurance card (verzekeringskaart) of the insurer; you receive both before you take out cover.
Frequently asked questions
What is owner's liability?
The liability in law of the owner of a structure for loss caused by a defect in that structure. Fault is not required for it.
Does my buildings insurance not cover this?
No. That pays for damage to the building itself. Loss the building causes to others is a liability risk.
Do I remain liable if I let?
Yes, as the owner you remain liable for defects in the building. The tenant is responsible for their own use.
Do the grounds count?
Yes, trees, paving and parking facilities on your grounds are also your responsibility. Include them in the cover.
Every situation is different. For these situations we have a separate page.
- Compare personal liability insurance (AVP)The main page
- VvE liability insuranceBuilding liability, visitors, caretaker
- Liability insurance for business premises and homes: choosing the coverArticle 6:174 of the Dutch Civil Code, letting, injury and property damage
- Liability insurance for the hospitality sectorGuests, food safety, terrace
- Liability insurance for care and welfareTreatment relationship, injury, disciplinary proceedings
- Liability risks in property: how insurance protects you6:174 DCC, tenants and visitors, letting
- Insuring a car without no-claims yearsStarting position, building up, alternatives
- Insuring a second carNo-claims years, second-car arrangement, regular driver