

Liability
- Falling tools
- Injury to passers-by
- Damage in the street
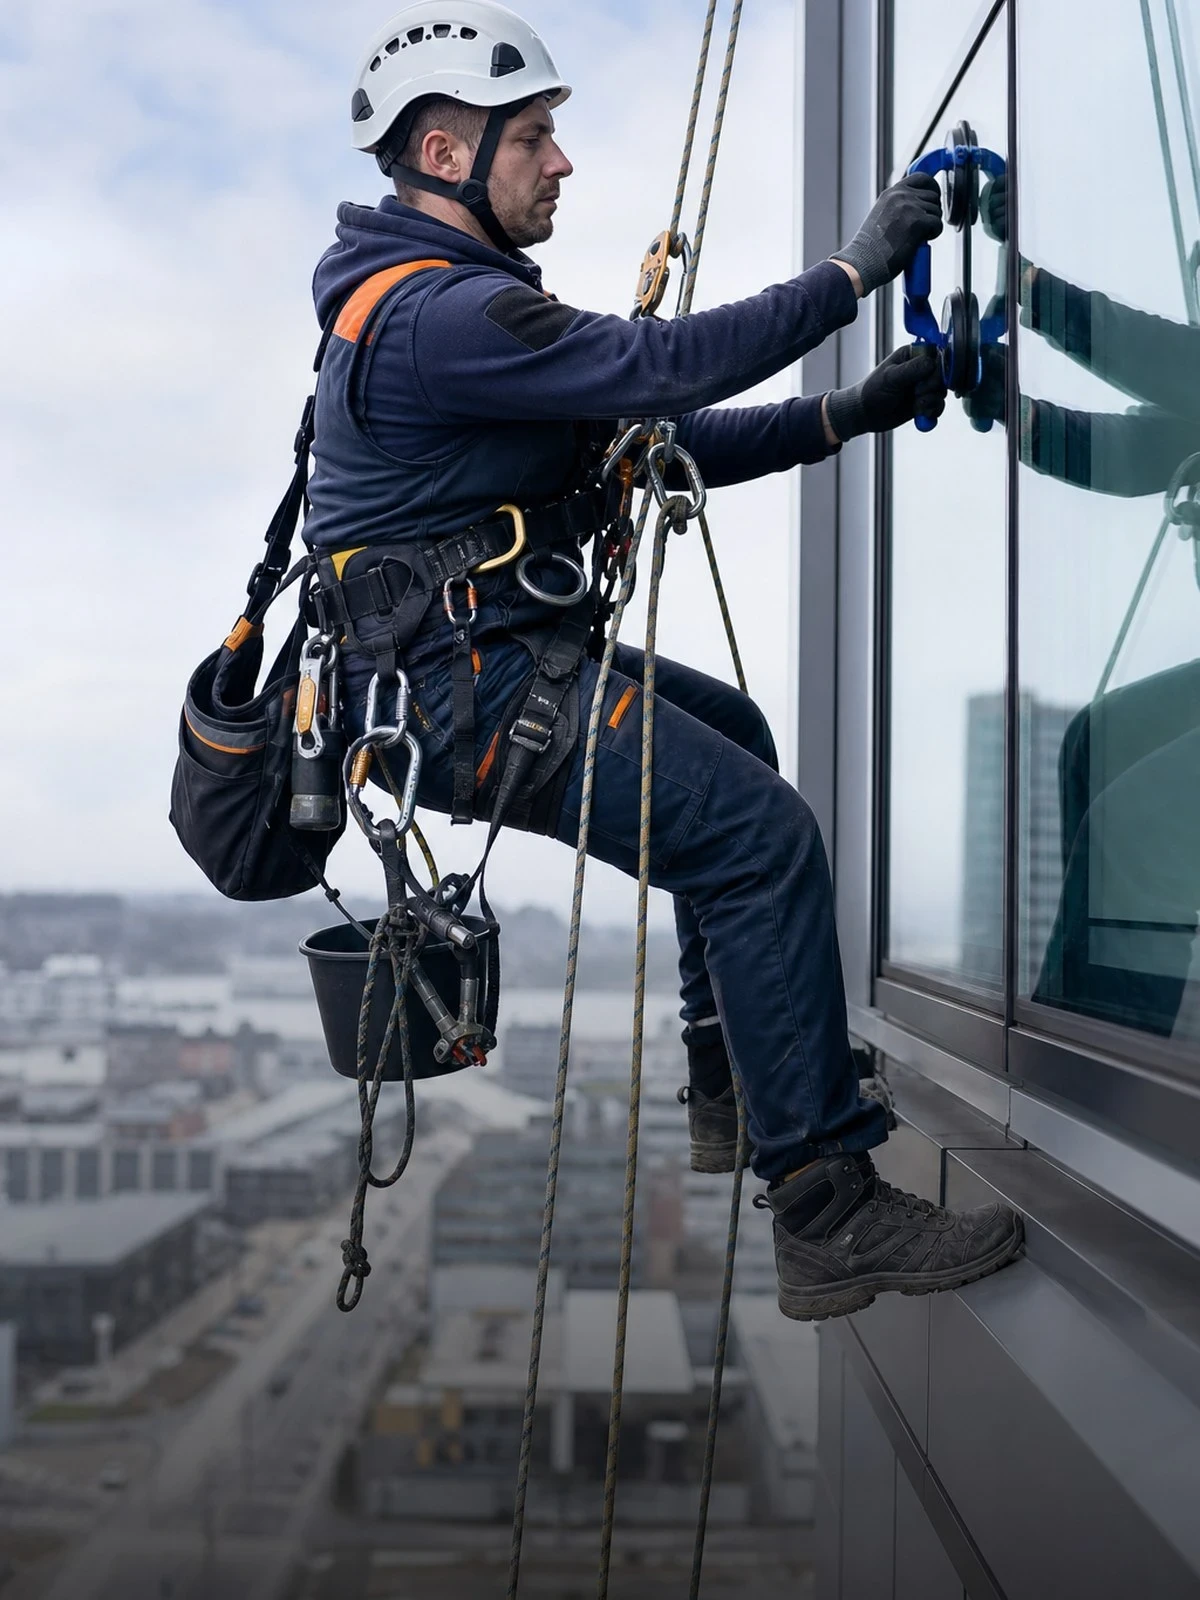
In rope access your biggest risk does not hang from the rope but lies below it: tools that fall, onto a roof, a street or an installation.
This page in another language: Nederlands
The calculator and the quote form below are in Dutch. Prefer to do this in English? Email info@finassverzekert.nl or call 072 - 509 24 56 and we will take it from there.
Work out for yourself what it would cost.
Enter your details; you will receive a proposal within one working day.
A premium indication, not personal advice. Prefer to talk it through? Call 072 - 509 24 56.
Rope access technicians work on facades, wind turbines, bridges, tanks and installations, suspended from a rope system. The AVB covers the damage and injury you cause to others in doing so.
Certification is not a formality here but the basis of the underwriting. Insurers ask about IRATA or SPRAT certification, the composition of the team and the rescue plan. Without those documents almost nobody will accept the risk.
We compare your personal liability insurance (AVP) across dozens of insurers, explain where the real differences lie, and arrange the switch from start to finish — without you having to chase it yourself.
 Personal liability insurance (AVP)
 Compare
 Get covered
The structure of the cover in three parts, with an overview per situation below.
Damage and injury caused by work on ropes.
The object you work on: facade, tank or turbine.
No valid certificates, no cover.
What is covered
| Situation | AVB | With care, custody and control |
|---|---|---|
| A falling tool damages a car | Yes | Yes |
| Injury to a passer-by | Yes | Yes |
| Damage to the facade you are working on | No | Yes |
| Damage to the turbine during maintenance | No | Yes |
| Work on offshore wind turbines | No | No |
| An expired IRATA or SPRAT certificate | No | No |
This overview is general in nature and is not personal advice. What is actually covered, including exclusions, limits and the excess, is set out in the policy conditions and the insurance card (verzekeringskaart) of the insurer; you receive both before you take out cover. Taking out cover without advice? Then read what execution only means for you.
Insurers weigh these details differently. That is where your saving is.
We look at the terms as well as the premium, and stay your point of contact when there is a claim.
We are not tied to one insurer and compare on the basis of an objective analysis of several companies.
You call or email someone who knows your file. No menu options, no changing call centres.
We cancel your old policy and align the start date, so you are never a day without cover.
We report the claim and monitor how it is handled. In urgent cases you can reach us on the emergency line.
Customers rate our service on four aspects: personal service, service delivery, availability and the outcome. The reviews are collected and published by NH1816 and come from customers who have actually taken out a policy with Finass Advies B.V. or reported a claim.
Four points that make the difference between a policy that pays out and one that does not.
Falling tools are the most common loss. Work with tool tethering and a cordon below the work zone, and record that you do.
IRATA or SPRAT certification and a rescue plan for each project are underwriting conditions. Without current certificates the cover lapses.
If you work on the facade, tank or turbine, damage to it falls under care, custody and control. That is excluded as standard.
Work on turbines at sea and on installations outside territorial waters falls outside a regular AVB.
This is what people ask us most.
Falling tools. The damage to what lies below and the risk of injury weigh more heavily than damage to the object itself.
IRATA or SPRAT, with proof for each technician, plus a rescue plan for each project. That is an underwriting condition at virtually every insurer.
Not as standard; that is a care, custody and control loss. Ask for care, custody and control cover if you work on the object itself.
Only if that is insured expressly. Offshore work is excluded on a regular AVB.
That is set out in the contract or specification and varies widely by sector. In industry and petrochemicals it is often several million per claim. Ask for the requirement before you tender.
The AVB covers damage to property and injury to people. The BAV covers pure financial loss: financial disadvantage caused by an error, without anything being broken or anyone being injured. In downtime and delay claims, that is the difference that counts.
Every situation is different. For these situations we have a separate page.
Request a quote without obligation. We will look at which insurer best matches your activities and your risk.
Prefer to call? 072 - 509 24 56, weekdays 09:00–17:00.
Claim on the road? Emergency line 06 - 55 20 40 72.
Finass Verzekert is a trading name of Finass Advies B.V. We advise on and arrange non-life insurance on the basis of an objective analysis of several insurers, and receive commission for this from the insurer, which is included in the premium. You pay no separate advice fee. Before you take out cover, we establish your wishes and needs.
You will find our licence, KvK and Kifid details and our complaints procedure at the foot of every page.
This page was compiled by Finass Verzekert. Last updated on .
The information on this page is general in nature and is not personal advice.
Maandag- Vrijdag: 09:00- 17:00
We use cookies and similar technologies to improve your experience on our website.